30-year mortgage rate
Warning
7.28%
up from 6.66% a month ago, near its highest in the past year.
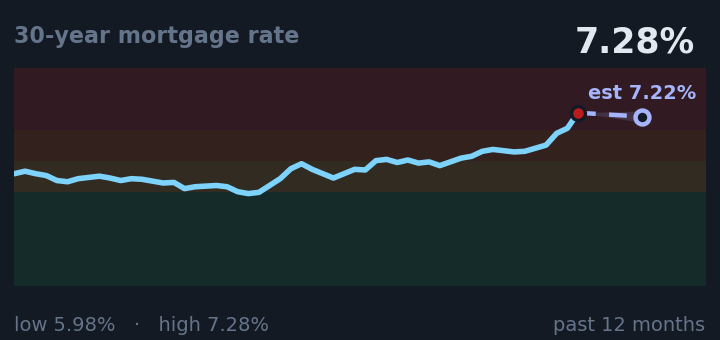
The 30-year mortgage rate at 7.28% determines the monthly cost of owning a home and what you can afford to borrow.
Source: FRED
10-year Treasury rate
Warning
5.24%
up from 4.79% a month ago, near its highest in the past year.
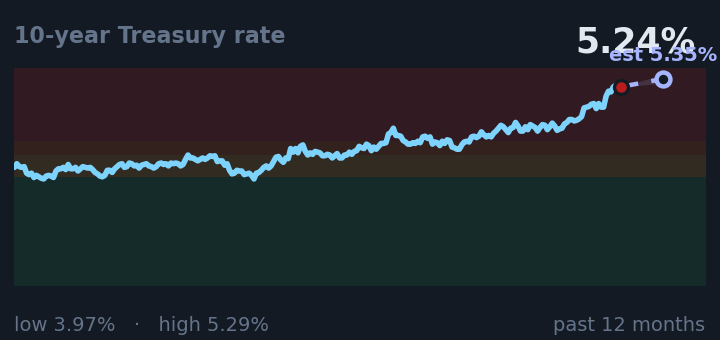
The 10-year Treasury rate at 5.24% is in the bond vigilante pressure zone, a level that historically forces policy reversals affecting trade and tariff decisions.
Connects to: Morgan Stanley IPO Lead Underwriter
Source: FRED
Gas at the pump
Watch
$4.46/gal
up from $4.08/gal a month ago, near its highest in the past year.
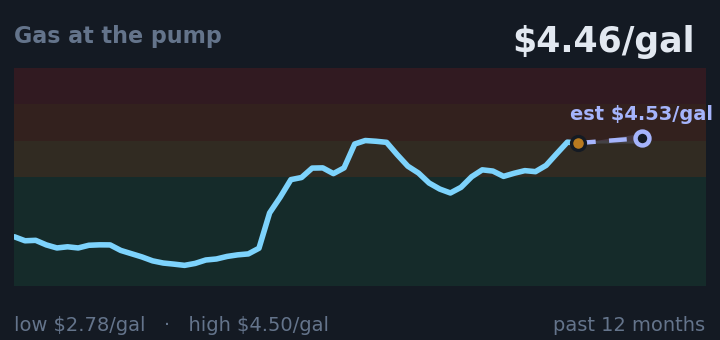
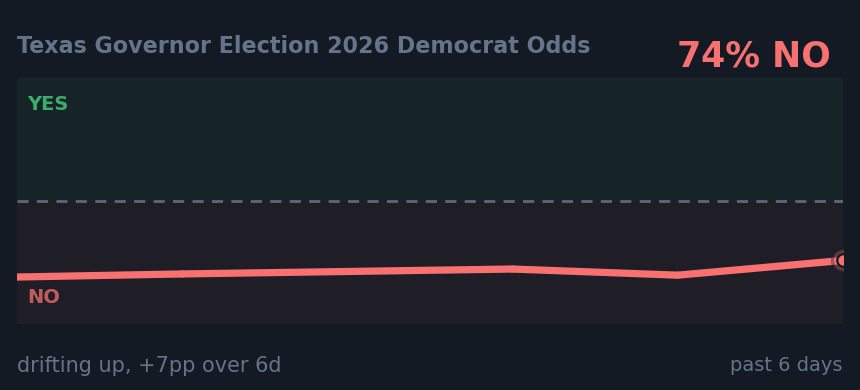
Gas at $4.46 a gallon is what you pay at the pump; when it's elevated like this, voter approval tends to decline.
Connects to: Texas Governor Election 2026 Democrat Odds
Source: FRED
30-year Treasury rate
Warning
5.61%
up from 5.27% a month ago, near its highest in the past year.
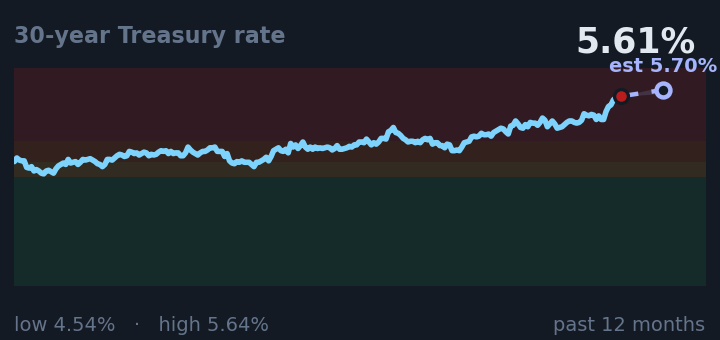
The 30-year Treasury rate at 5.61% is the long-term borrowing cost for government and companies; when it rises like this, the cost of servicing the national debt spirals higher.
Connects to: Morgan Stanley IPO Lead Underwriter
Source: FRED
Consumer sentiment
Caution
52
down from 55 a month ago, in the middle of its range for the past year.
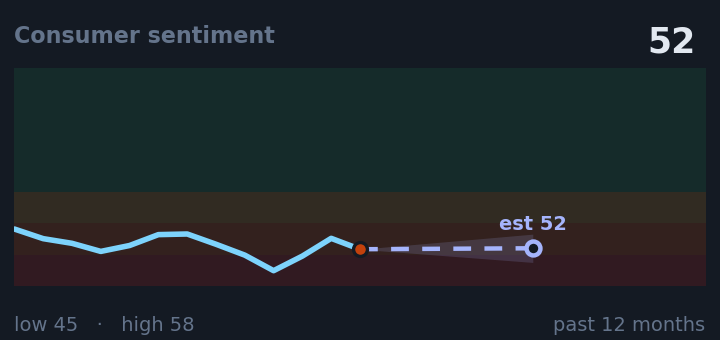
Consumer sentiment at 52 is depressed, below the recessionary threshold of 60, and predicts whether people will spend, take on debt, and look for new jobs.
Connects to: Texas Governor Election 2026 Democrat Odds; Morgan Stanley IPO Lead Underwriter
Source: FRED
People filing for unemployment
Normal
197k
down from 204k a month ago, in the middle of its range for the past year.
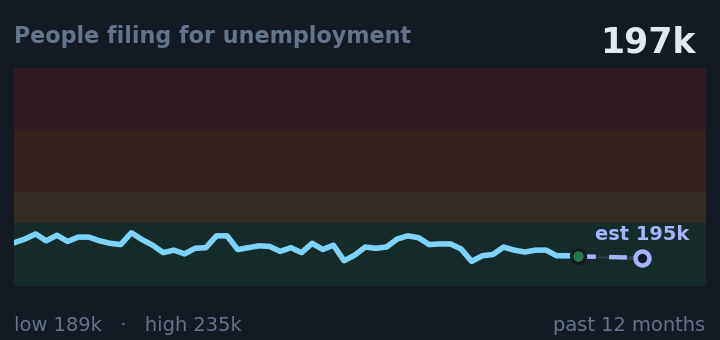
People filing for unemployment at 197,000 per week is the clearest signal of labor market strength; when it's low like this it means employers are holding onto workers.
Connects to: Morgan Stanley IPO Lead Underwriter
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.45%
up from +0.40% a month ago, in the middle of its range for the past year.
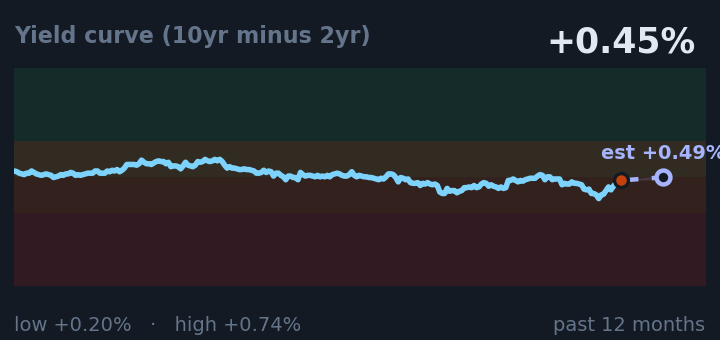
The yield curve spread at positive 0.45% is the difference between long-term and short-term borrowing rates; when it goes negative it has historically preceded recessions.
Connects to: Morgan Stanley IPO Lead Underwriter
Source: FRED
Market volatility (VIX)
Normal
16.4
about the same as a month ago, in the middle of its range for the past year.
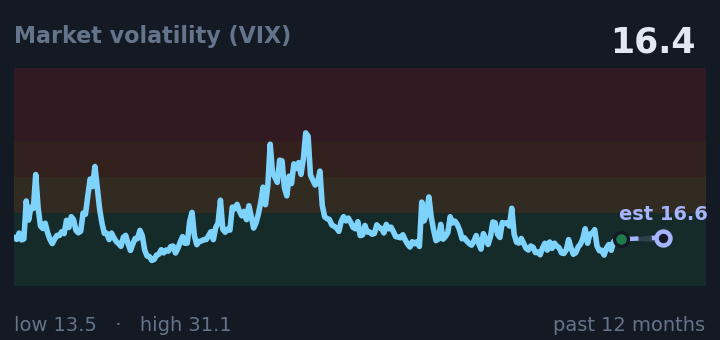
Market volatility at 16.4 measures expected stock price moves; this level is within the normal range.
Source: FRED