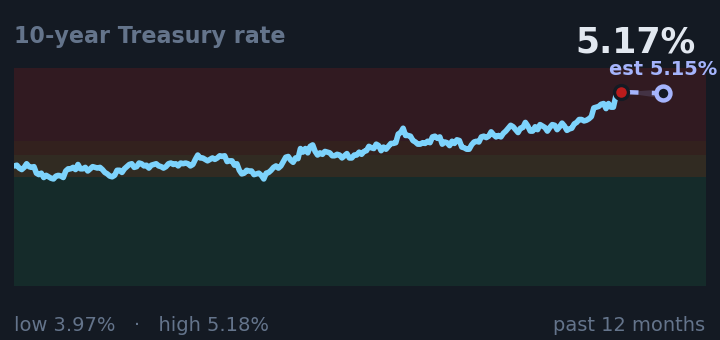
The 10-year Treasury yield at 5.17% sits in the bond vigilante pressure zone; historical patterns show this level forces policy reversals, as occurred in April 2025 when tariff pauses followed rate rises.
Source: FREDThe market's price on "Magdalena Andersson be the next Prime Minister of Sweden" has risen 79 points over the past month, down 7 of that in the past week, one of the clearest sustained moves on the board. It now reads 80% YES. On September 22nd this brief named "Trump recognize Somaliland" at 29% YES. The market's price has fallen to 9% since, a move of 20 points in 7 days. 2 of the 5 biggest movers sit in Europe, clustered together on the map: "Alberto Núñez Feijóo become Prime Minister of Spain following the next Spanish general election" (Spain) and "Magdalena Andersson be the next Prime Minister of Sweden" (Sweden). The month-long backdrop is unchanged: borrowing costs, mortgage rates, gas at the pump and how households feel are still pressing on the wallet.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
The 10-year Treasury yield at 5.17% sits in the bond vigilante pressure zone; historical patterns show this level forces policy reversals, as occurred in April 2025 when tariff pauses followed rate rises.
Source: FRED
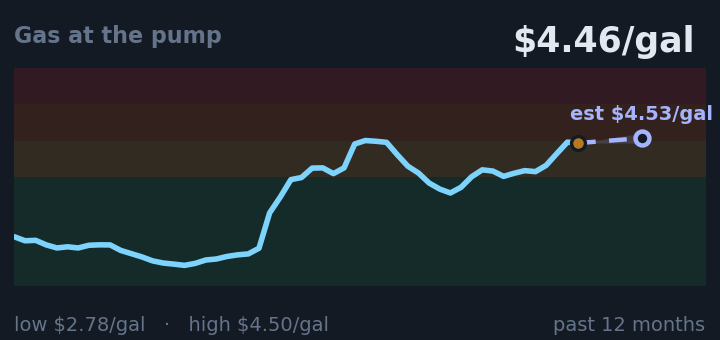
Gas at $4.48 a gallon is elevated and historically correlates with declining approval for sitting leaders.
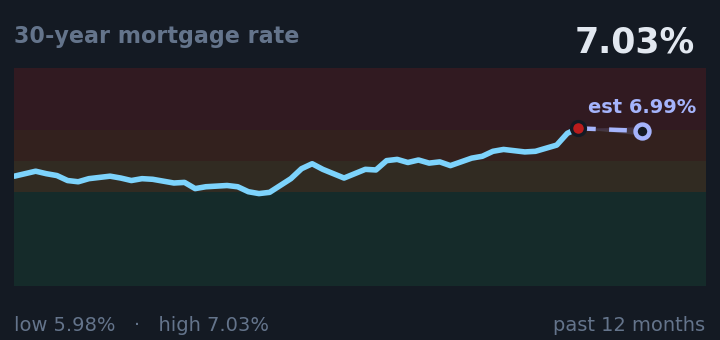
The 30-year mortgage rate at 7.03% sits in the housing affordability crisis zone, which freezes home purchases.
Source: FRED
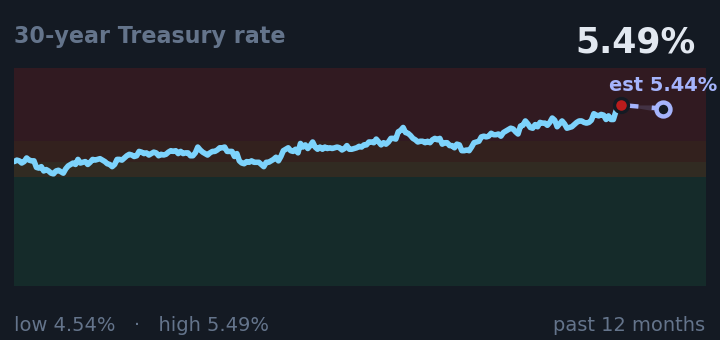
The 30-year Treasury yield at 5.49% marks the fiscal sustainability crisis zone where deficit financing costs spike.
Source: FRED
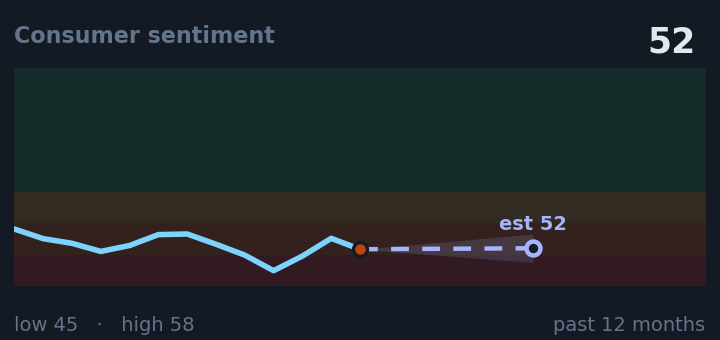
Consumer sentiment at 52 sits below the recessionary threshold of 60, indicating reduced household confidence and purchasing.
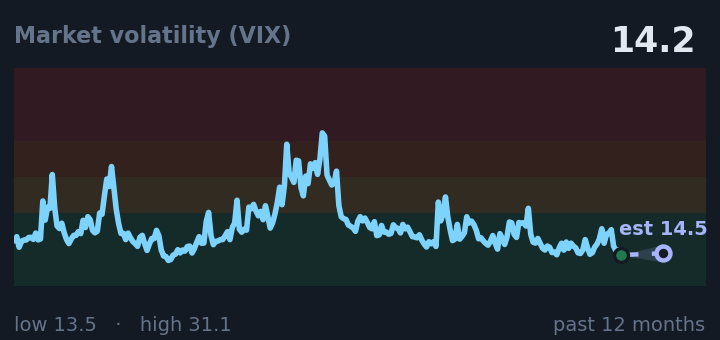
Market volatility at 14.2 is near its lowest, indicating traders see little need to hedge against near-term market moves.
Source: FRED
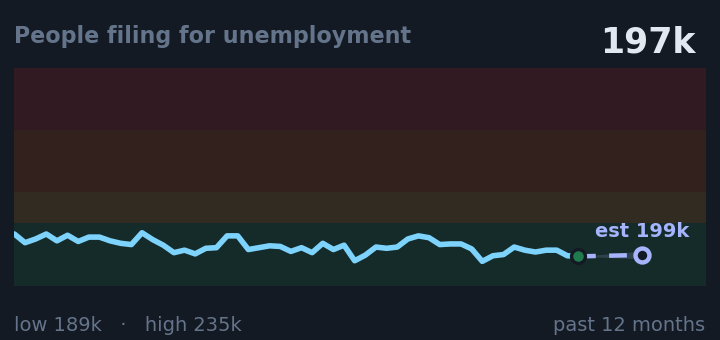
Jobless claims at 197,000 are very low, indicating a tight labor market where job losses remain minimal.
Source: FRED
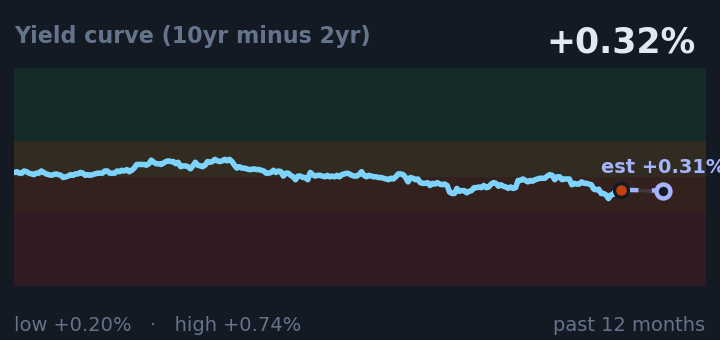
The yield curve at 0.32% (10-year Treasury minus 2-year Treasury) is flattening; inversion in this measure historically signals recession, though it remains positive today.
Source: FRED
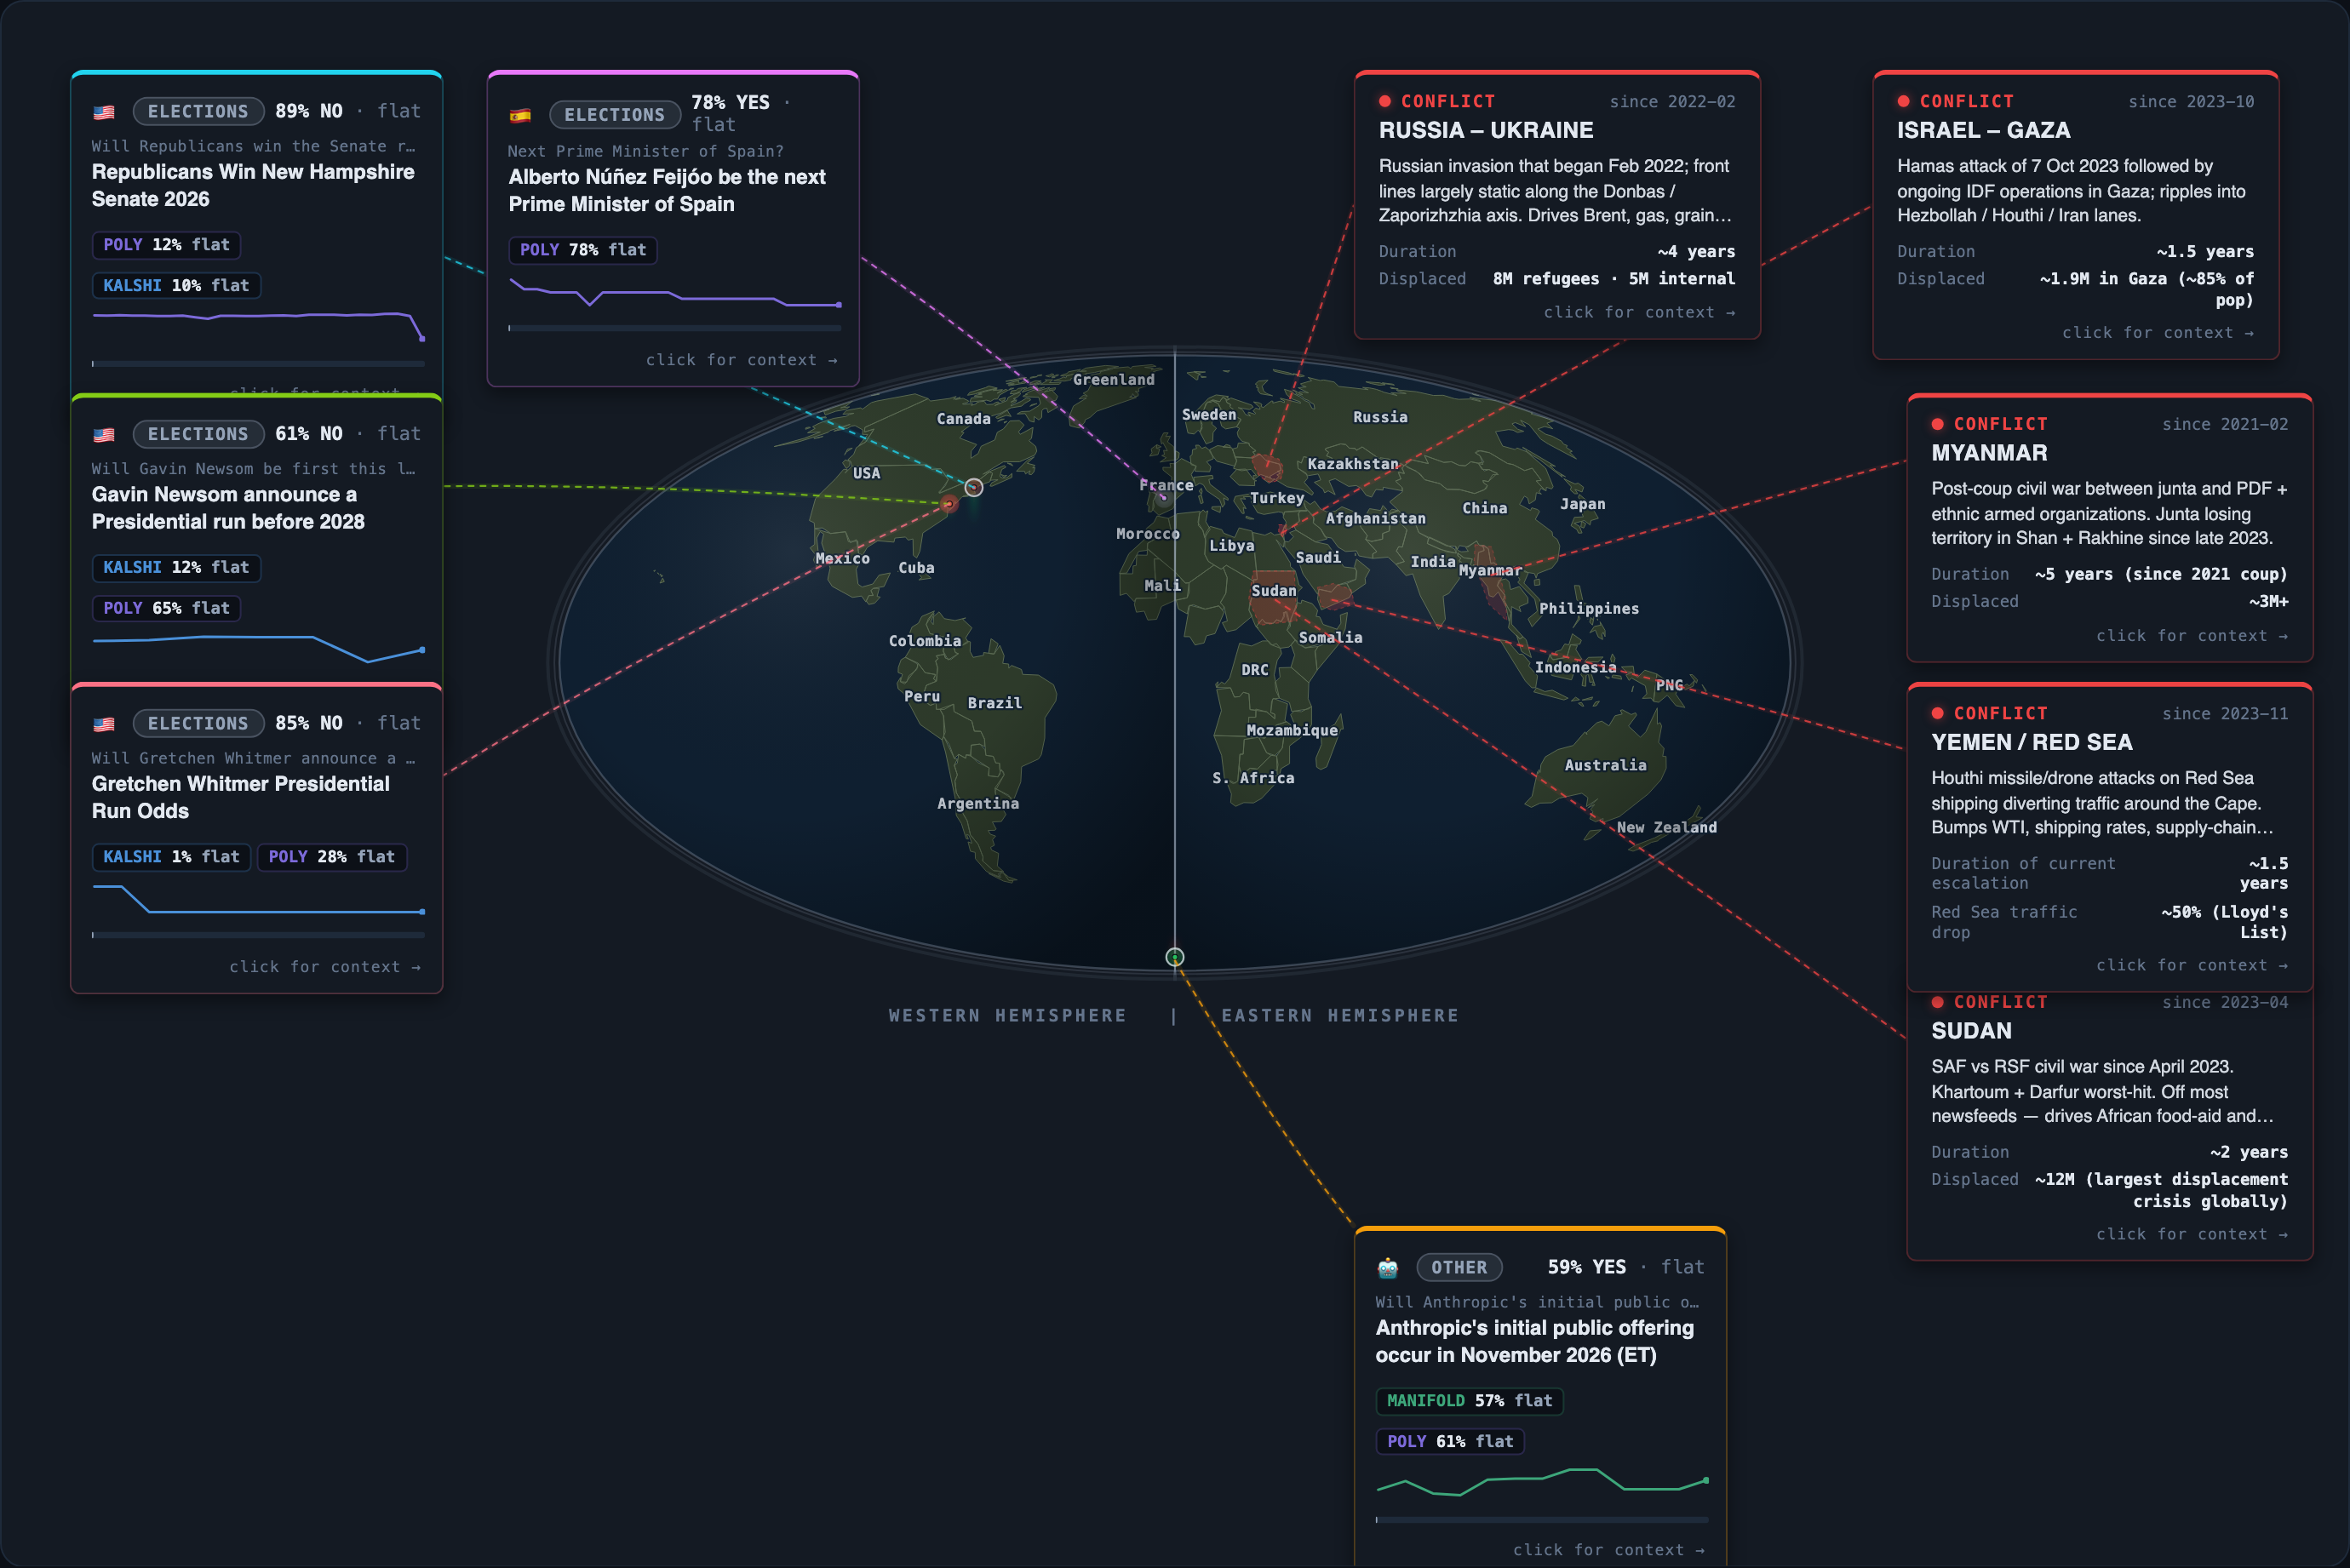
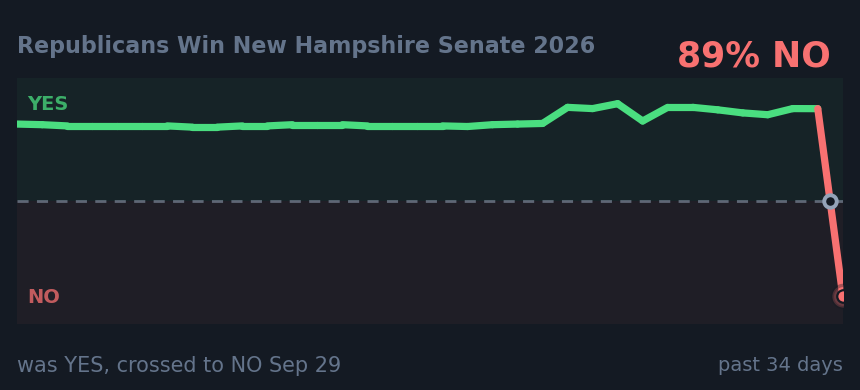
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Kalshi prices Republican victory at 90% while Polymarket's inverse Democrat position implies 18% Republican odds—an 8-point spread suggesting model divergence on macro headwinds. Depressed consumer sentiment and elevated gas prices historically favor incumbents, but timing and ca
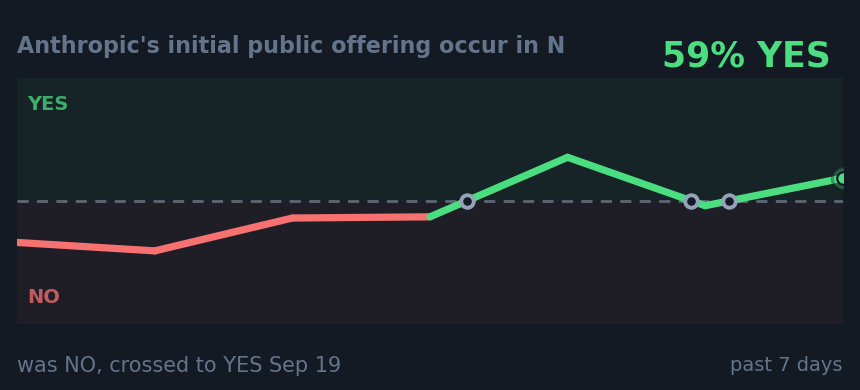
In plain terms: the public’s money is close to a coin flip on whether this will happen, and held steady overnight.
Manifold prices a 56% chance of public trading by November 6, while Polymarket estimates only a 25% probability for an IPO in November, indicating a significant disagreement between the platforms about the timing of Anthropic's initial public offe…
In plain terms: the public’s money is leaning that this will happen, and held steady overnight.
The platforms agree on an 82% probability, indicating a strong consensus among traders about the next Prime Minister's identity, with no clear underdog or overbetting.
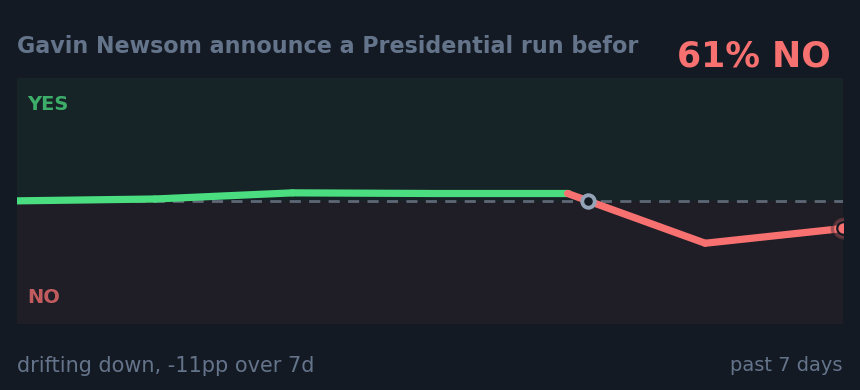
In plain terms: the public’s money is close to a coin flip on whether this will not happen, and held steady overnight.
Kalshi prices Newsom at 22% chance of being first to declare before Nov 1, 2028, while Polymarket shows an 80% probability, indicating a significant disagreement between the platforms on his likelihood of declaring early.
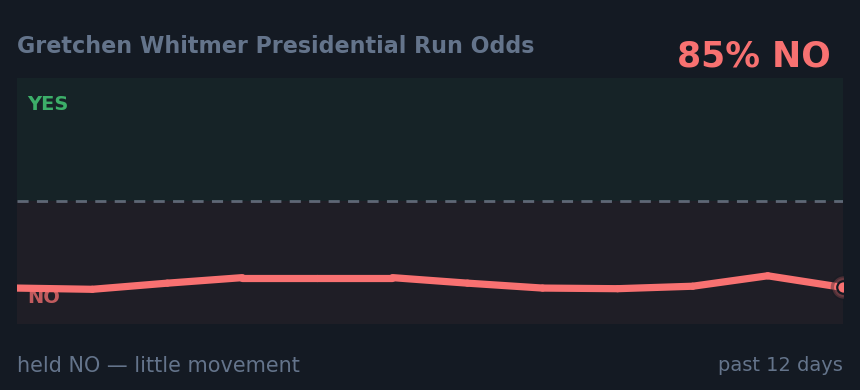
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
The platforms agree on a 0 percentage points spread, indicating no disagreement between their prices, with Polymarket pricing Whitmer's announcement at 36%, reflecting the average probability of her running before 2028.
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 3 flat |
| EUROPE | 0 rose 0 fell 1 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |