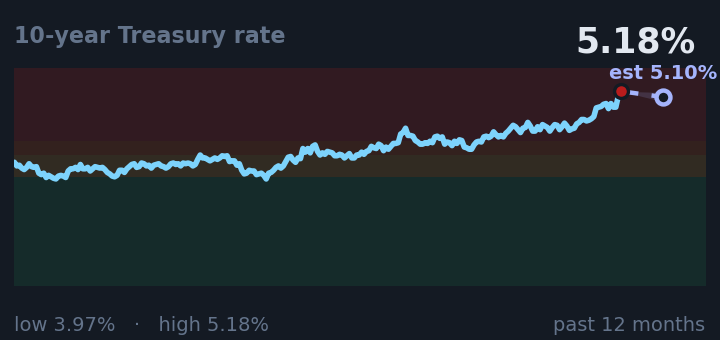
The 10-year Treasury rate at 5.18% sets the baseline for most household debt and is currently in a historical pressure zone where policy reversals tend to happen.
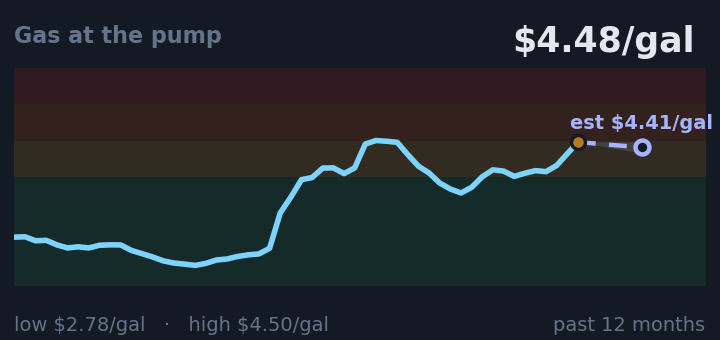
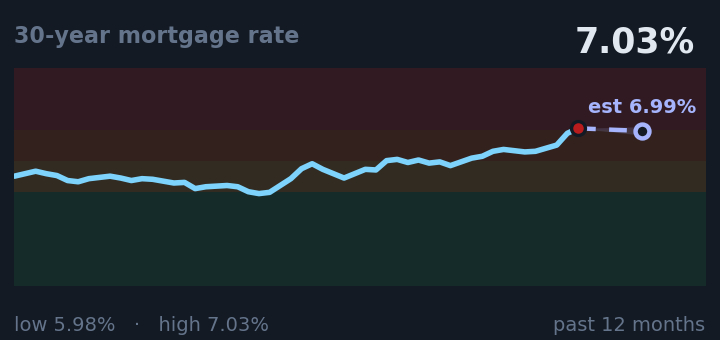
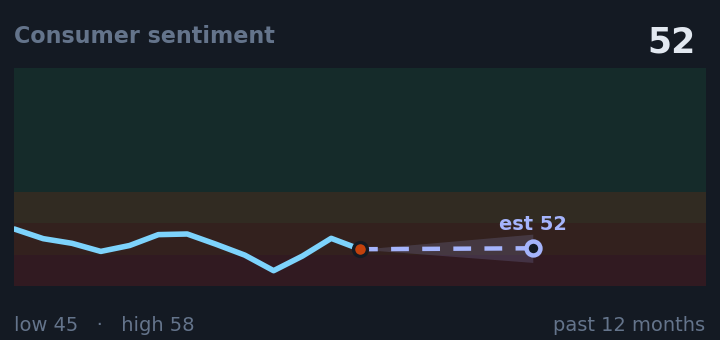
Source: FREDThe market's price on Republicans winning the Senate race in Kansas crossed above 50% to YES today, now at 72% after rising 42 points in a single day and 3 points this week, reversing a month-long decline of 6 points. In France, four presidential candidates fell into near-certain defeats on the same day: Borne, Cazeneuve, Olivier Faure, and Jordan Bardella each declined 20 to 22 points and now sit at 2%, marking an establishment rejection across Western Europe. These political shifts are unrelated to the month-long wallet tightening: mortgages climbed to 7.03%, gas to $4.48 a gallon, and the 10-year Treasury rate moved to 5.18%, all elevated from a month prior. Consumer sentiment fell to 52 this month, reversing earlier gains, the only fundamental signal to shift direction. On September 20th this brief named Trump recognizing Somaliland at 12% YES; the market has climbed 17 points in six days to now 29%.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
The 10-year Treasury rate at 5.18% sets the baseline for most household debt and is currently in a historical pressure zone where policy reversals tend to happen.
Source: FRED
Gas at $4.48 a gallon sits at an elevated level that historically correlates with declines in approval ratings.
A 30-year mortgage rate of 7.03% marks a housing affordability crisis zone, limiting how many households can access home loans.
Source: FRED
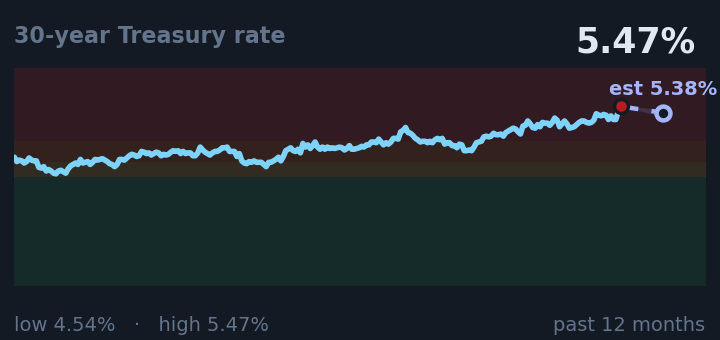
The 30-year Treasury at 5.47% enters a fiscal sustainability crisis zone where deficit costs spiral and housing markets freeze.
Source: FRED
Consumer sentiment at 52 is depressed and has fallen below the recessionary threshold of 60, indicating households are losing confidence.
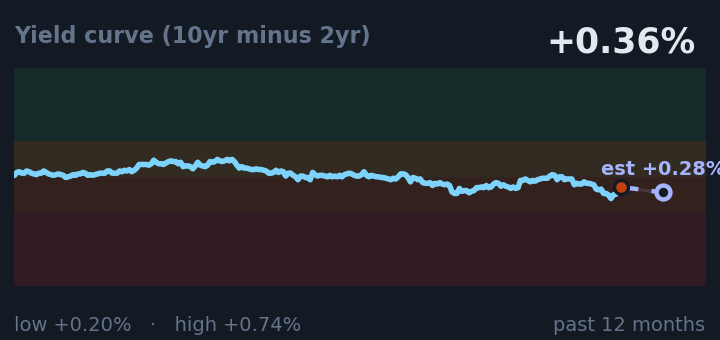
The yield curve spread at 0.36% continues flattening, and when it inverts, has historically preceded recessions.
Source: FRED
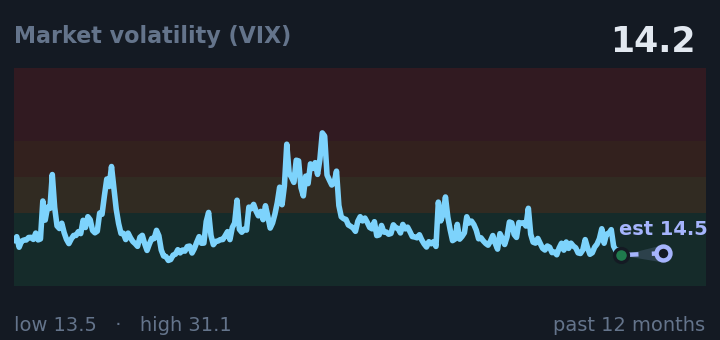
Market volatility at 14.2 is near its year's lowest, signaling that traders see little risk and markets are complacent.
Source: FRED
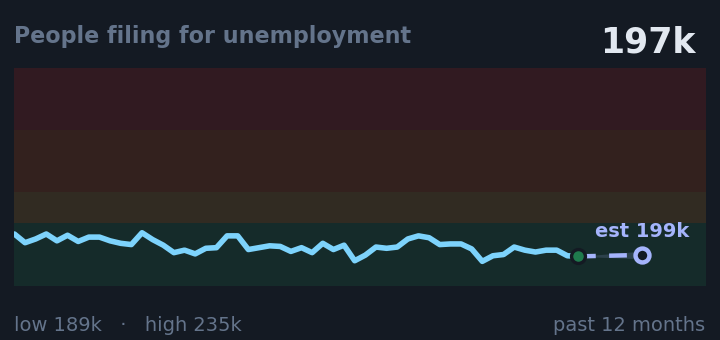
Jobless claims at 197,000 are very low, reflecting a tight labor market where job security remains stable.
Source: FREDIn plain terms: the public’s money is very confident this will not happen, and held steady overnight.
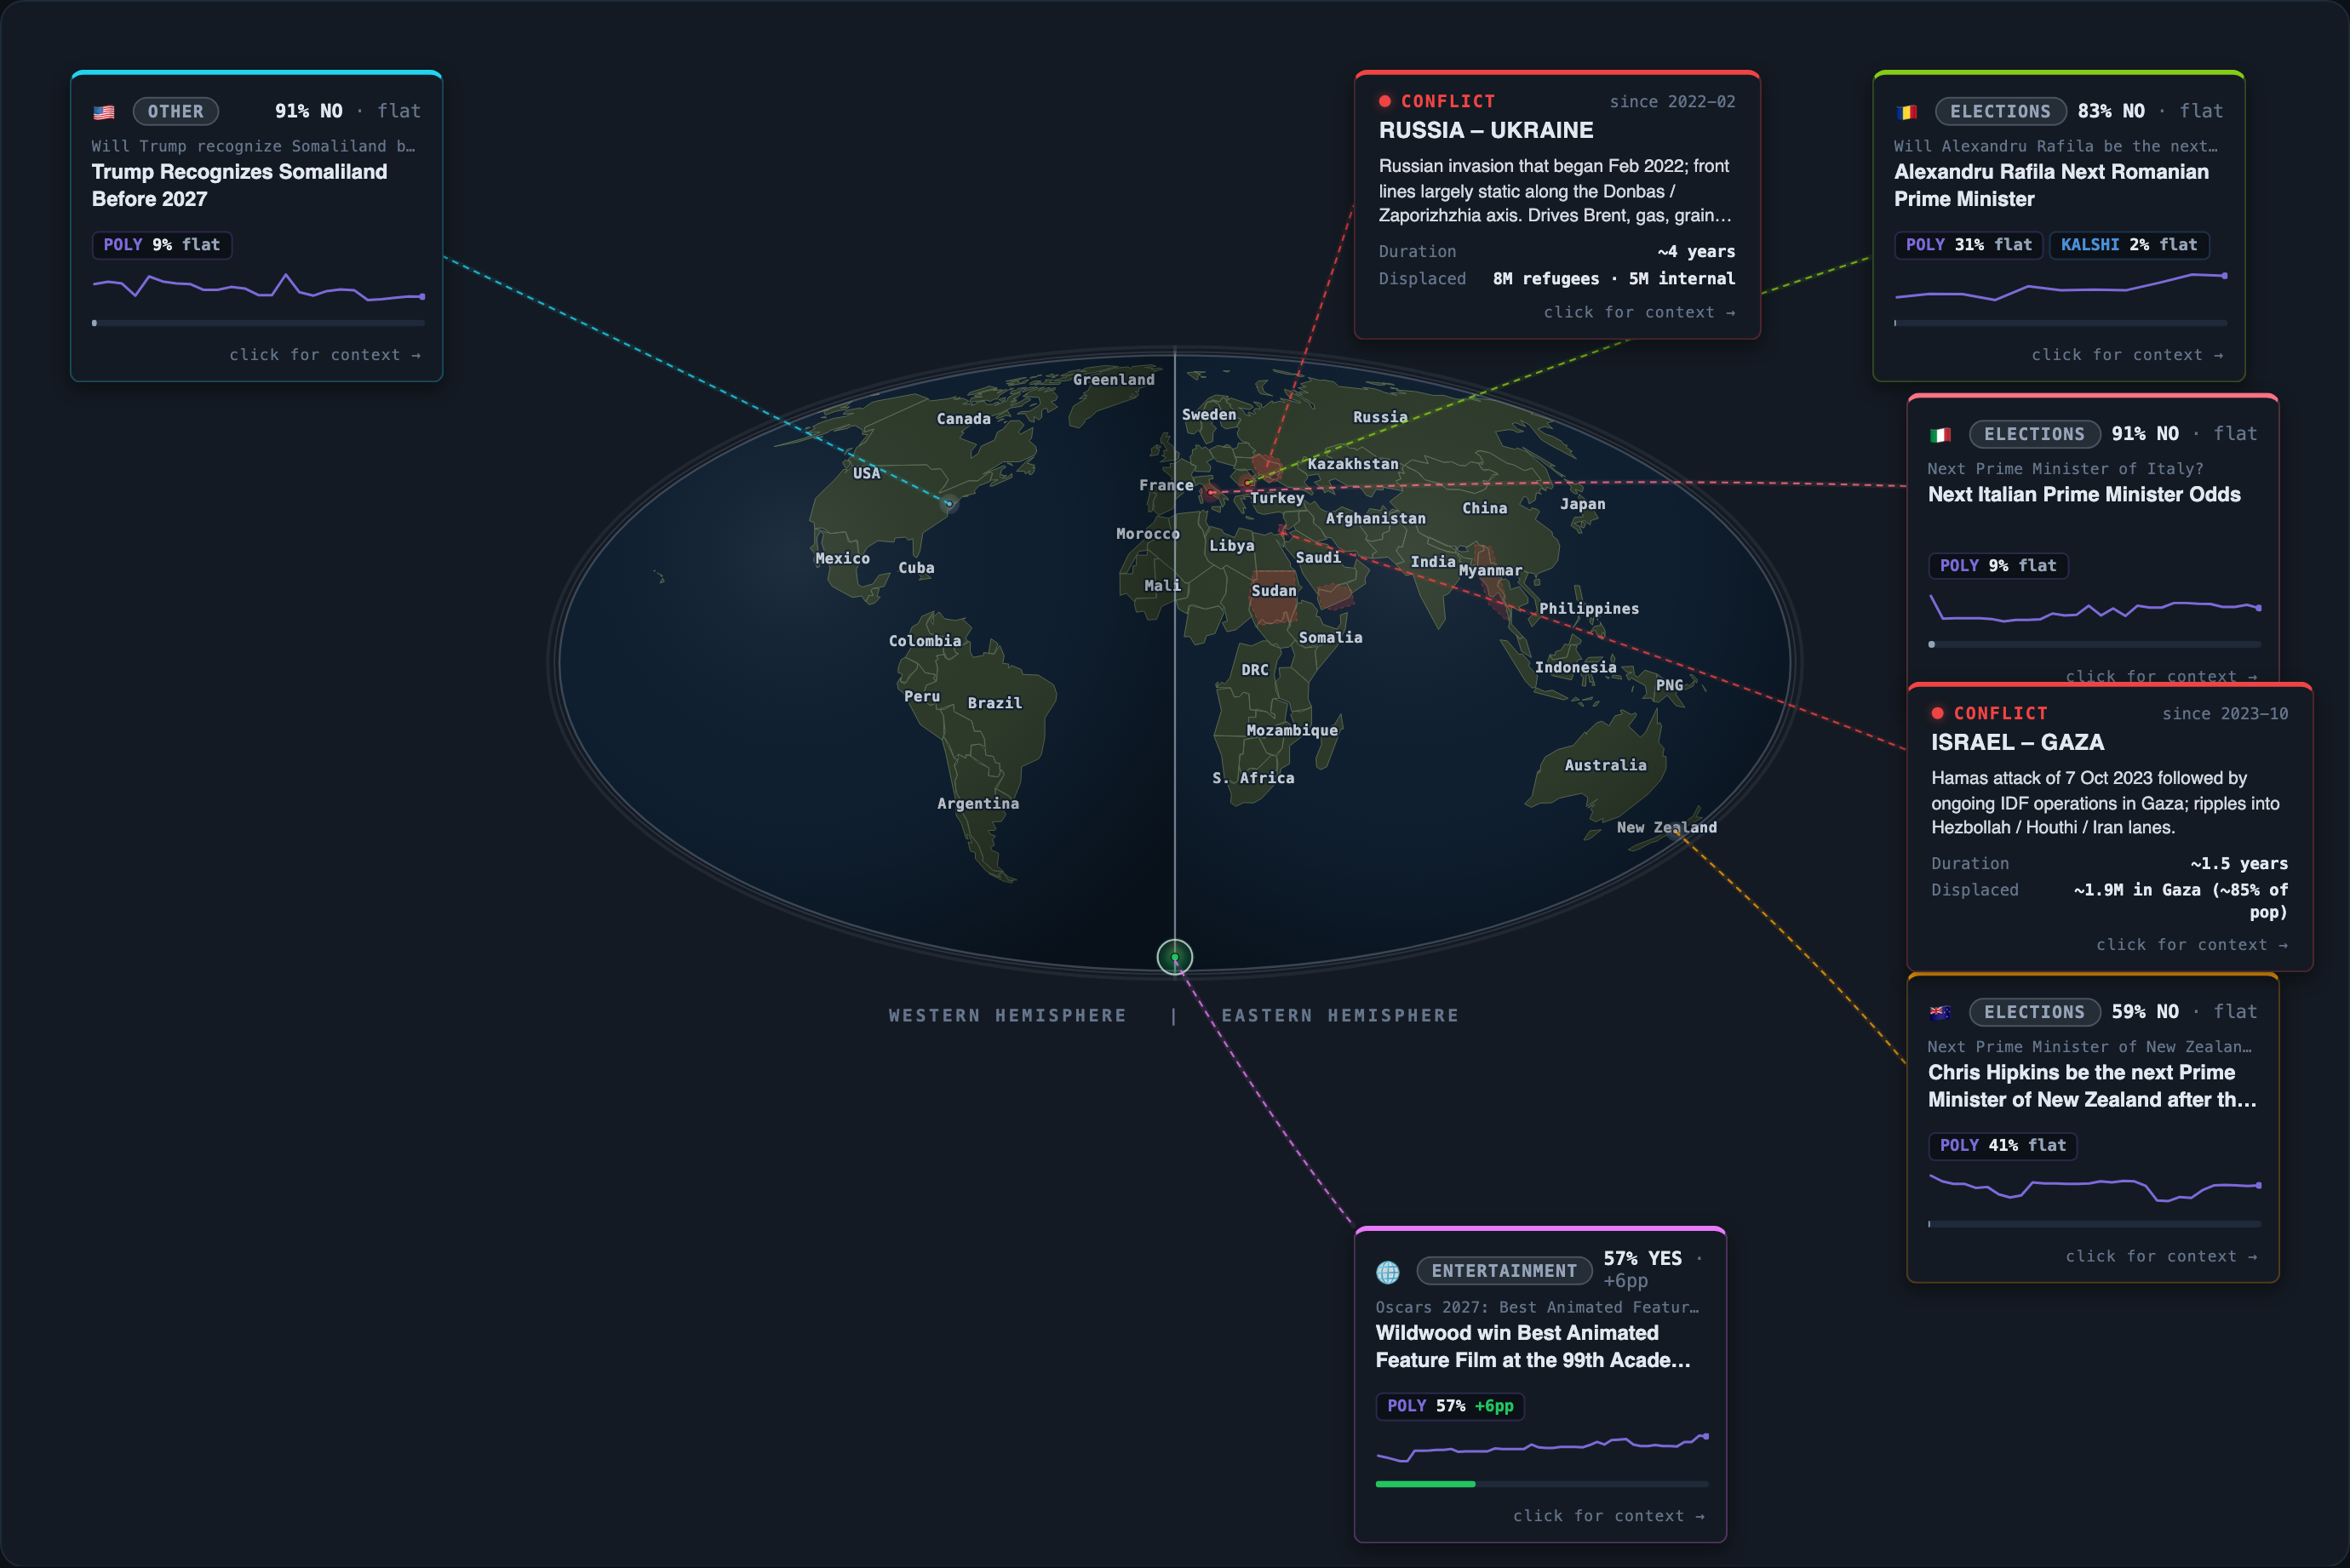
Massive 48-point spread between Kalshi (63%) and Polymarket (15%) on U.S. recognition of breakaway Somaliland. Disagreement likely reflects different interpretations of Trump's foreign policy priorities, geopolitical constraints with Somalia, and whether recognition occurs via ex
In plain terms: the public’s money is close to a coin flip on whether this will not happen, and held steady overnight.
The platforms agree on a 50% probability of Chris Hipkins being the next Prime Minister, with no price listed for Kalshi's related question and Polymarket pricing him at 50%.
In plain terms: the public’s money is close to a coin flip on whether this will happen, and grew more sure overnight.
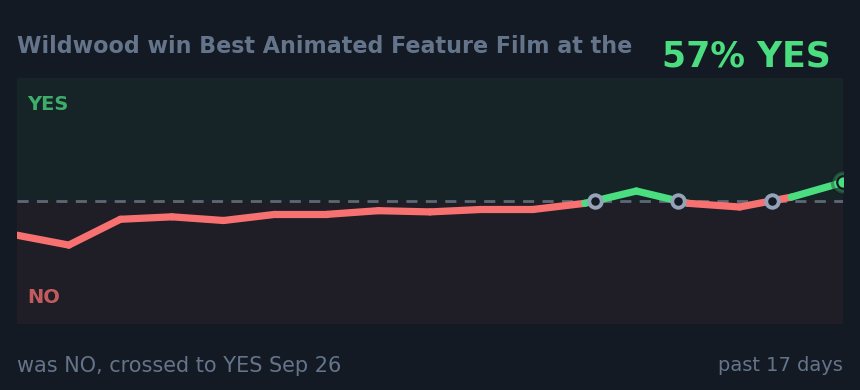
The platforms agree on a 38% average probability of Toy Story 5 winning, indicating no significant disagreement or price discrepancy between them.
In plain terms: the public’s money is leaning that this will not happen, and held steady overnight.
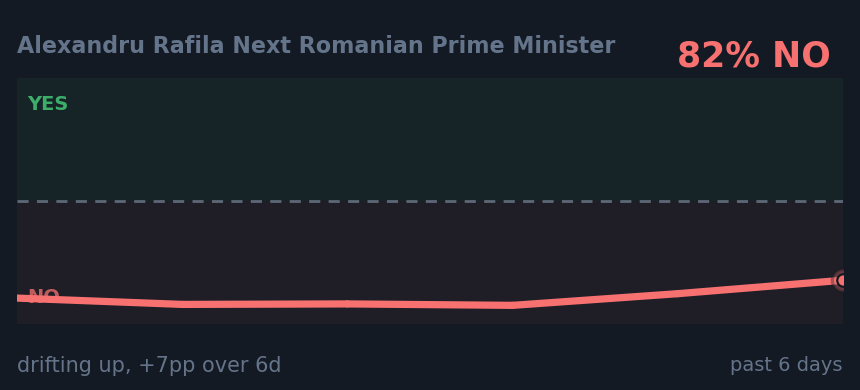
Polymarket's 0% price versus Kalshi's 8% (Grindeanu alternative) suggests extreme uncertainty about succession timing and candidate viability. Depressed consumer sentiment (57) and elevated gas prices create political instability favoring incumbent or establishment candidates, ma
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
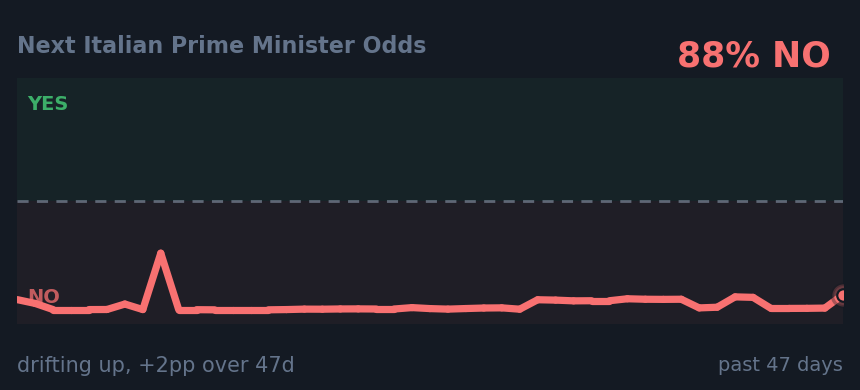
Kalshi and Polymarket agree on Roberto Gualtieri's low chances at 9-11%, with a 2-point spread indicating moderate disagreement, but both platforms price him as the most likely candidate among those mentioned.
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds โ drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 1 flat |
| EUROPE | 0 rose 0 fell 2 flat |
| ASIA | 0 rose 0 fell 1 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |