Gas at the pump
Watch
$4.32/gal
up from $4.01/gal a month ago, near its highest in the past year.
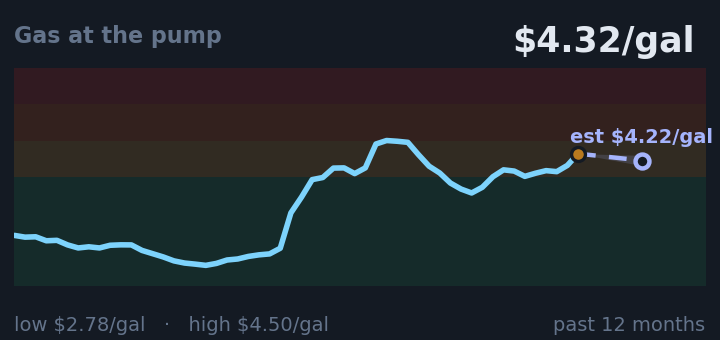
Gas prices at their highest in a year affect what you pay at the pump and historically tend to weigh on voter approval.
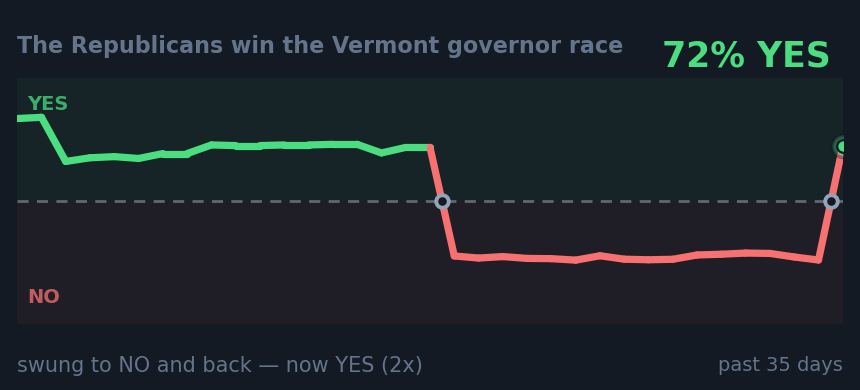
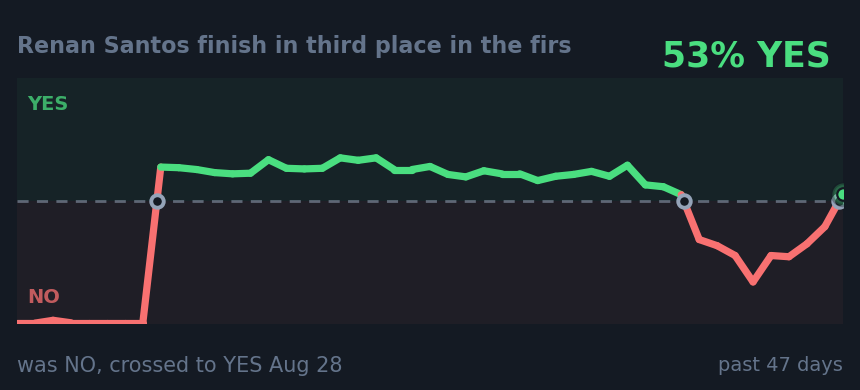
Connects to: Republicans Win Vermont Governor 2026; Australia Next Prime Minister Election; Brazil 2026 Presidential Election Third Place Finisher
Source: FRED
10-year Treasury rate
Warning
5.01%
up from 4.72% a month ago, near its highest in the past year.
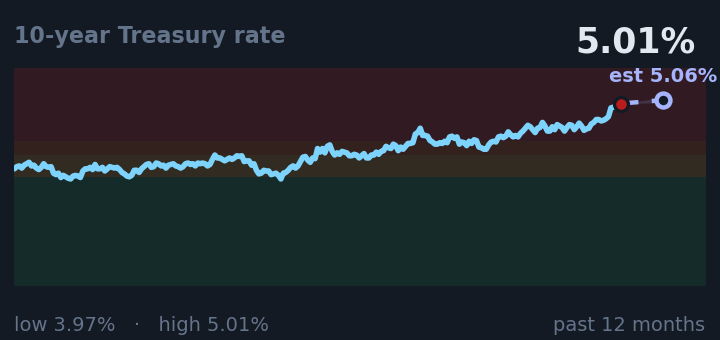
The 10-year Treasury rate at 5.01% is high enough that it has forced policy reversals in the past, constraining what governments can borrow at affordable rates.
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.27%
down from +0.52% a month ago, near its lowest in the past year.
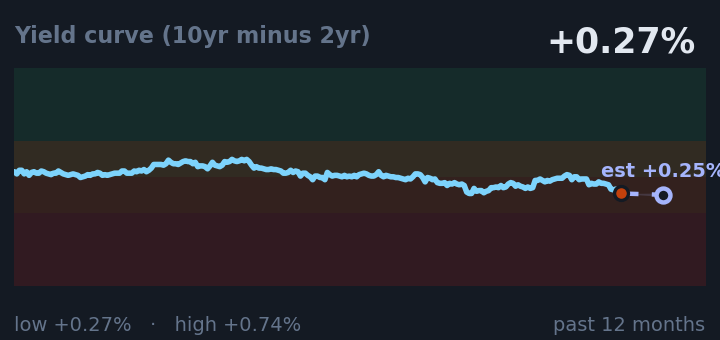
The gap between 10-year and 2-year Treasury rates has flattened to 0.27% and is near its lowest in a year, a warning sign for future economic slowdowns.
Source: FRED
Consumer sentiment
Caution
55
up from 50 a month ago, in the middle of its range for the past year.
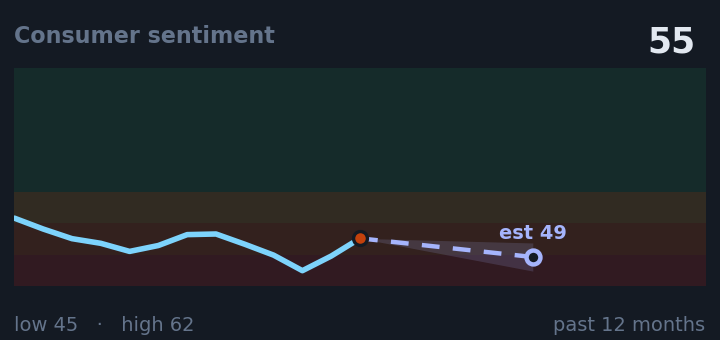
Consumer sentiment at 55 remains depressed, well below the 60 threshold where households typically increase spending, signaling households remain cautious about their finances.
Connects to: Republicans Win Vermont Governor 2026; Australia Next Prime Minister Election; Brazil 2026 Presidential Election Third Place Finisher
Source: FRED
30-year mortgage rate
Caution
6.95%
up from 6.67% a month ago, near its highest in the past year.
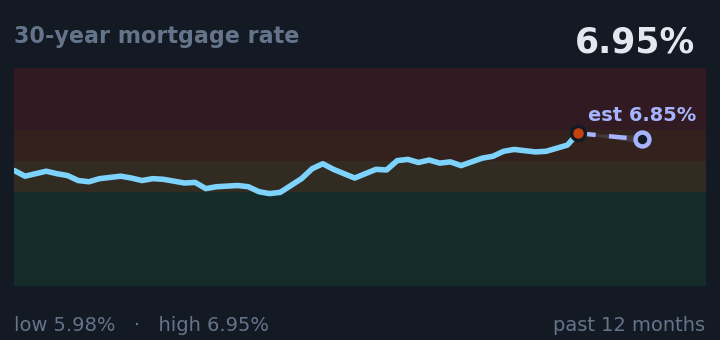
The 30-year mortgage rate at 6.95% is near the highest in a year and suppresses housing demand by raising the cost of borrowing for a home.
Source: FRED
People filing for unemployment
Normal
196k
down from 212k a month ago, near its lowest in the past year.
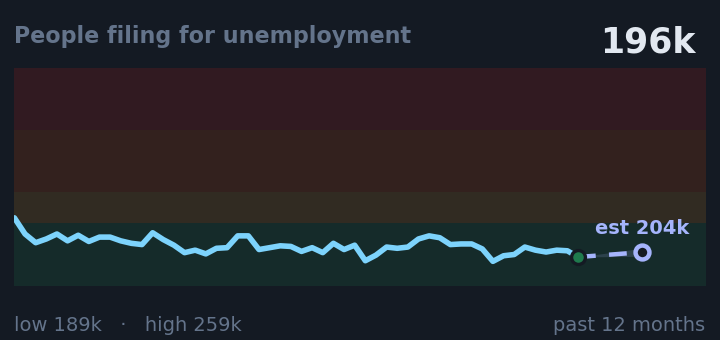
Jobless claims at 196k are near their lowest in a year, indicating employers are still hiring and the labor market remains tight despite economic pressures.
Source: FRED
30-year Treasury rate
Warning
5.35%
about the same as a month ago, near its highest in the past year.
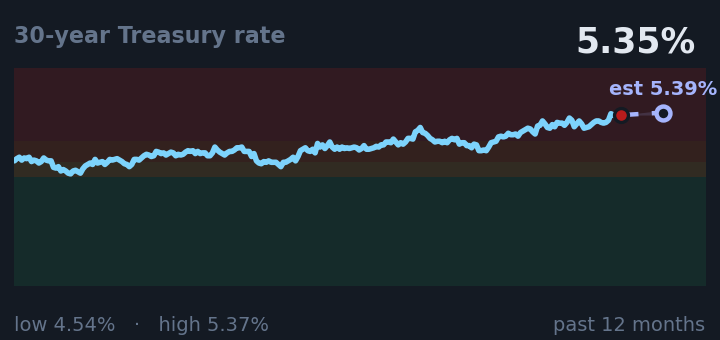
The 30-year Treasury rate at 5.35% is in the fiscal crisis zone where borrowing costs for governments spike, making it harder to finance deficits and raising mortgage rates as a side effect.
Source: FRED
Market volatility (VIX)
Normal
15.4
down from 15.8 a month ago, near its lowest in the past year.
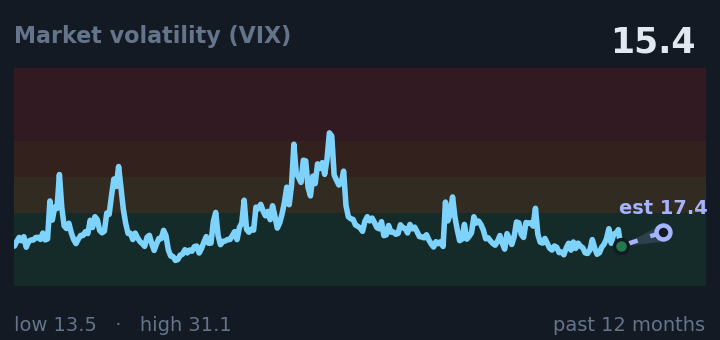
Market volatility at 17.7 is in the middle of its normal range, signaling neither unusual calm nor panic among investors.
Source: FRED