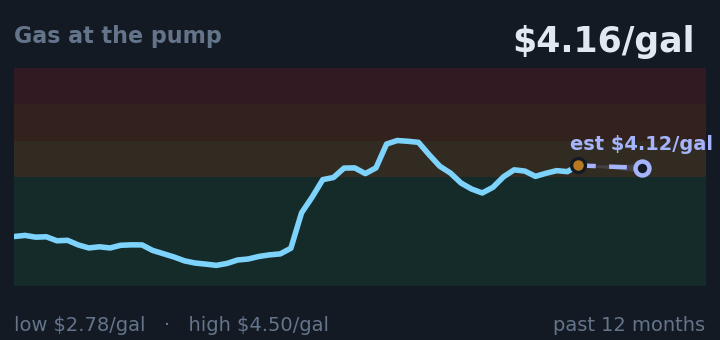
Gas at the pump is $4.16/gal, up from $4.08/gal a month ago, and in the middle of its range for the past year.
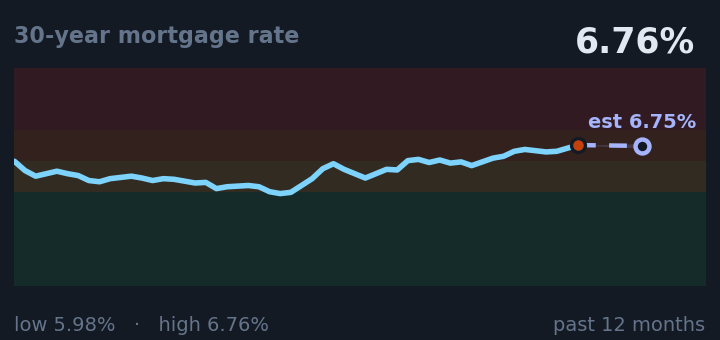
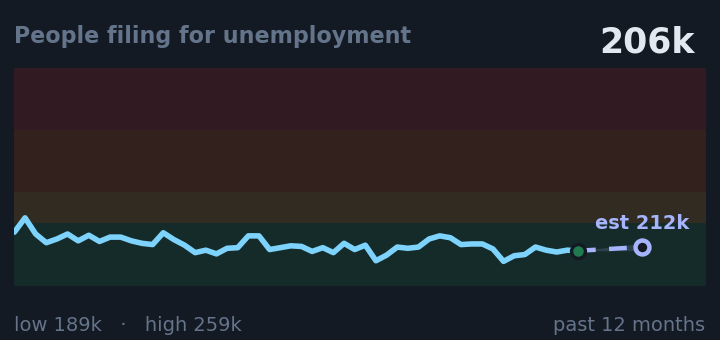
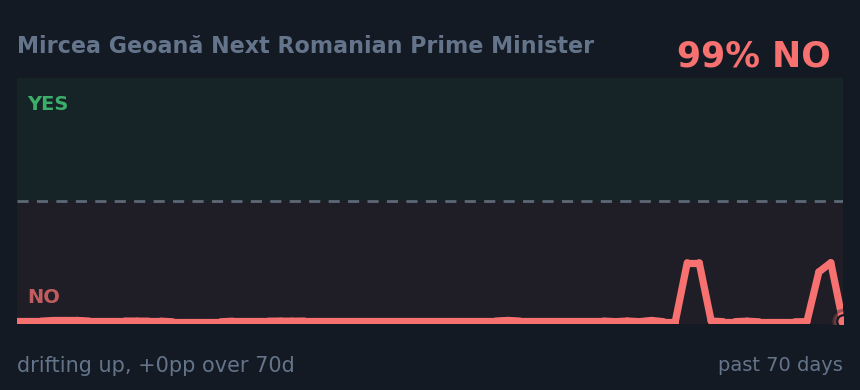
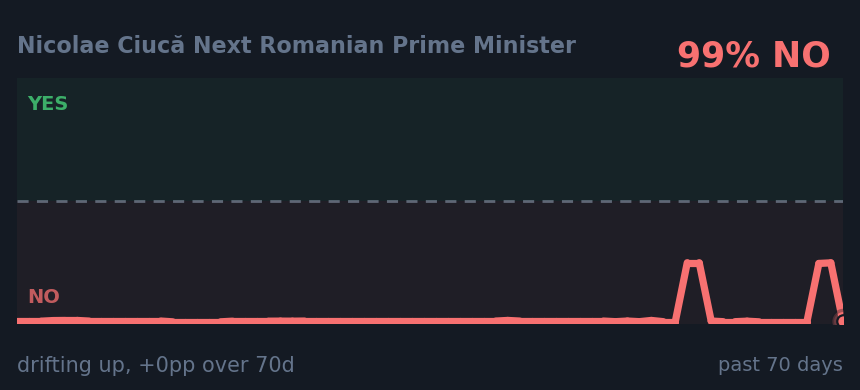
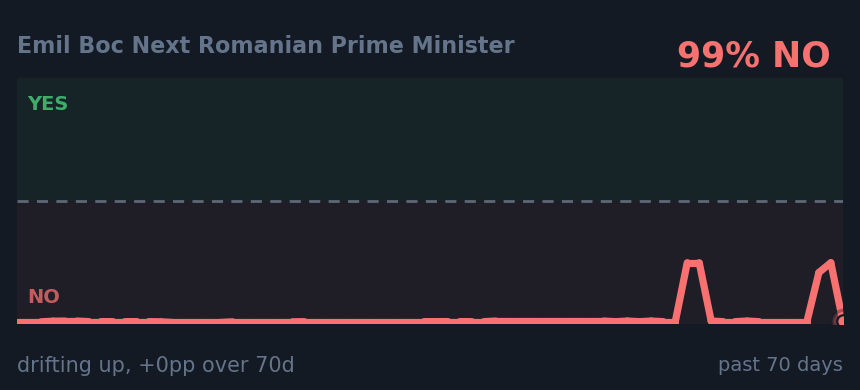
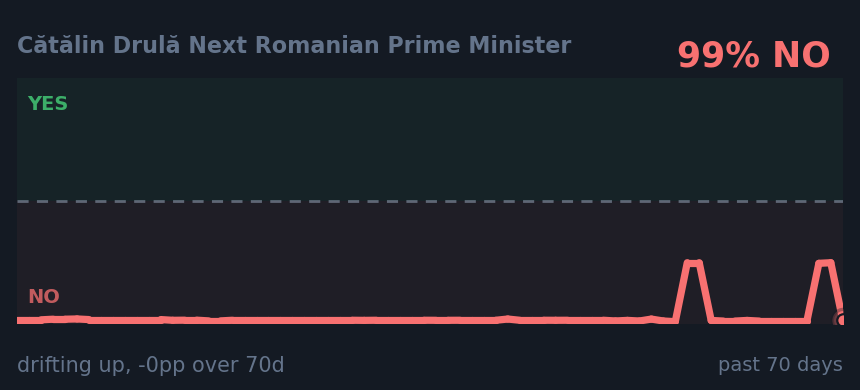
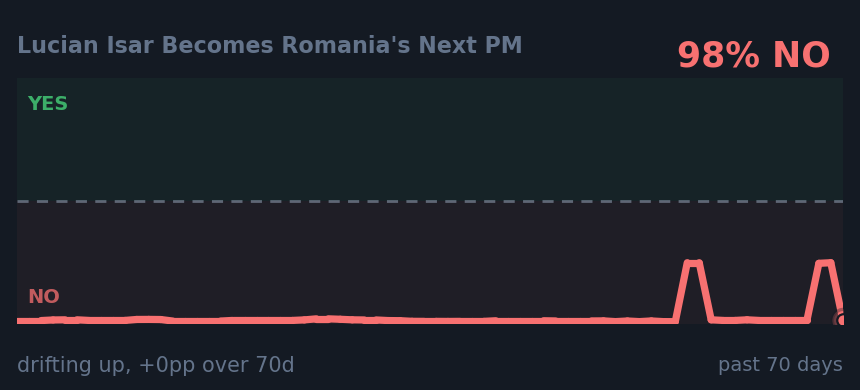
On September 8th this brief named "Alexandru Nazare Next Romanian Prime Minister" at 27% YES. The market's price has risen to 50% since, a move of 24 points in 7 days. 5 of the 5 biggest movers sit in Europe, clustered together on the map: "Nicolae Ciucă Next Romanian Prime Minister" (Romania) and "Emil Boc Next Romanian Prime Minister" (Romania) and "Mircea Geoană Next Romanian Prime Minister" (Romania) and "Cătălin Drulă Next Romanian Prime Minister" (Romania) and "Lucian Isar Becomes Romania's Next PM" (Romania). The month-long backdrop is unchanged: borrowing costs, mortgage rates, gas at the pump and layoffs are still pressing on the wallet. Otherwise the picture held: 30-year mortgage rate is 6.76%; people filing for unemployment is 206k.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Gas at the pump is $4.16/gal, up from $4.08/gal a month ago, and in the middle of its range for the past year.
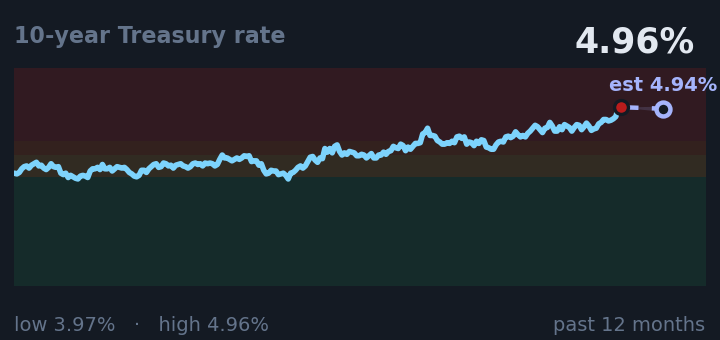
The 10-year Treasury rate at 4.96% determines the cost of borrowing for longer-term debt, including mortgages and student loans.
Source: FRED
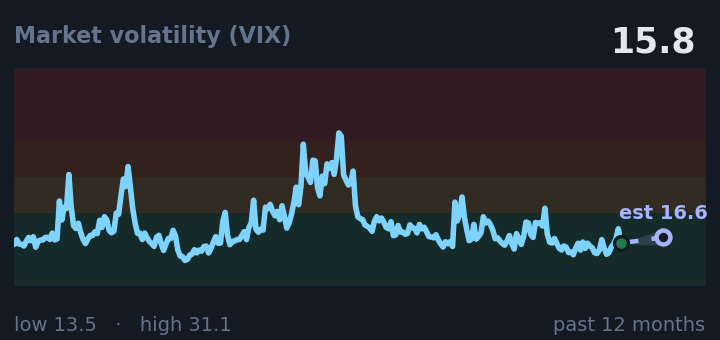
Market volatility at 15.8 is in the normal range, showing stock investors are not in acute distress.
Source: FRED
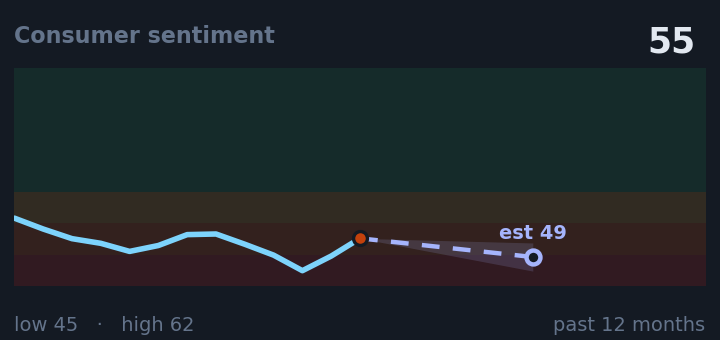
Consumer sentiment at 55 remains below 60, the threshold where households typically increase spending, signaling continued financial caution.
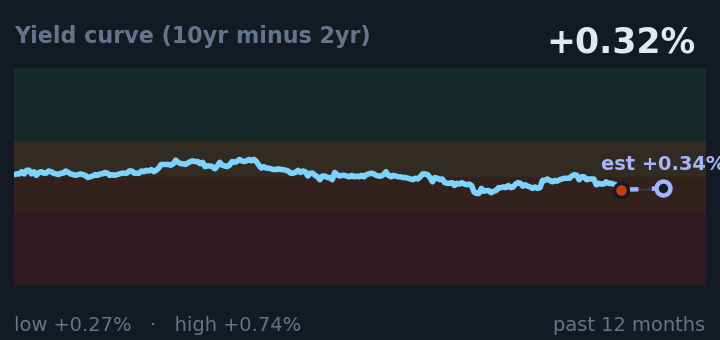
The spread between 10-year and 2-year Treasury rates at 0.32% indicates bond investors are watching for potential economic weakness.
Source: FRED
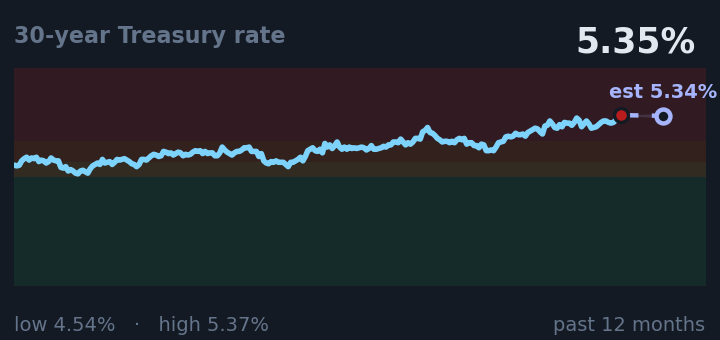
The 30-year Treasury rate at 5.35% indicates fiscal sustainability concerns in bond markets, directly raising mortgage rates that households pay.
Source: FRED
The 30-year mortgage rate at 6.76% is elevated, substantially raising monthly payments and suppressing housing demand.
Source: FRED
Initial jobless claims at 206,000 remain in a healthy range, though they have edged upward over the past month.
Source: FRED
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Extreme disconnect between Polymarket (0%) and Kalshi (2%) on a low-probability outcome suggests either data lag or genuine model divergence. Depressed consumer sentiment (57) and elevated gas prices typically weaken incumbent coalitions, potentially favoring opposition figures l
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Two major prediction platforms show extreme consensus (0-2%) that Ciucă won't become next PM, suggesting market confidence in this outcome. The 2-point spread indicates near-certainty, making this a low-uncertainty political event despite broader economic headwinds.
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Polymarket-Kalshi spread (0%-2%) on a low-probability event suggests minimal disagreement on Boc's slim chances. Depressed consumer sentiment and elevated gas prices may further reduce his viability in upcoming political transitions.
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Low-probability event with tight 2-point spread between Polymarket (1%) and Kalshi (3%), suggesting genuine uncertainty despite depressed consumer sentiment (57) and elevated energy costs that typically undermine incumbent support. Agreement at such low levels indicates markets s
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Extremely niche prediction on a relatively unknown Romanian politician with minimal market interest (0-2% pricing). The tight spread reflects low liquidity rather than genuine uncertainty—depressed consumer sentiment and elevated energy costs create broader political volatility,
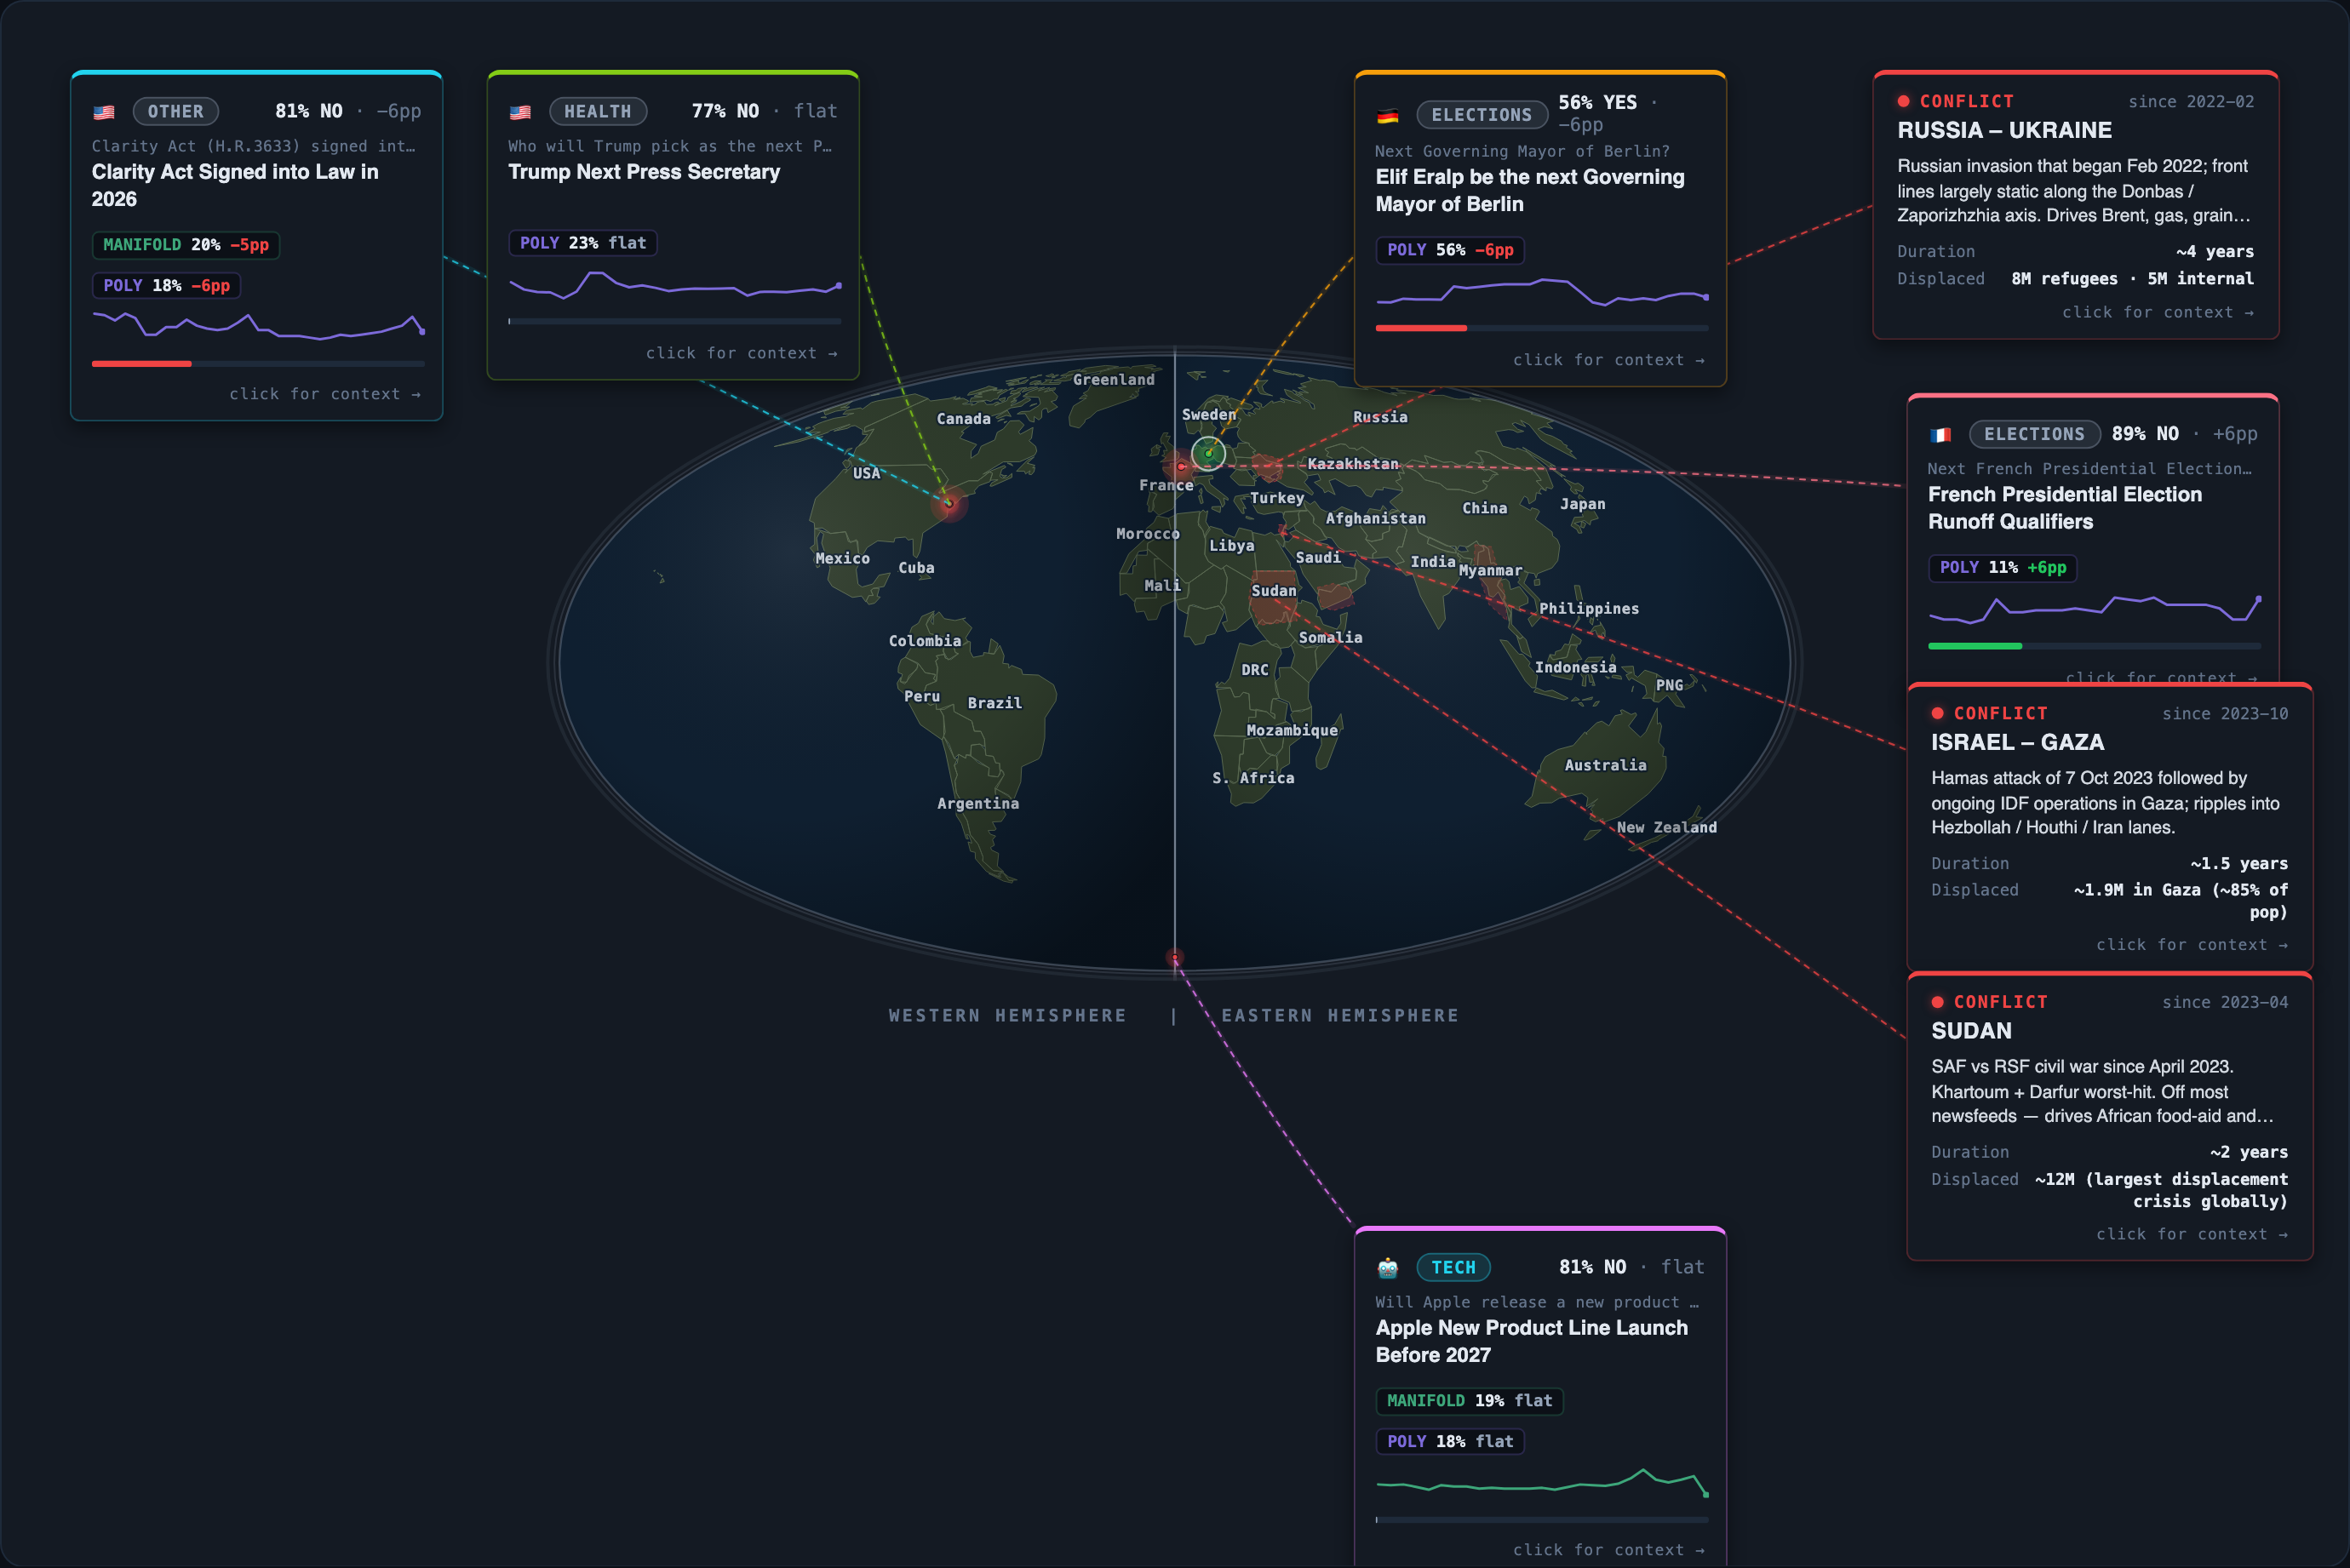
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 0 flat |
| EUROPE | 5 rose 0 fell 0 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |