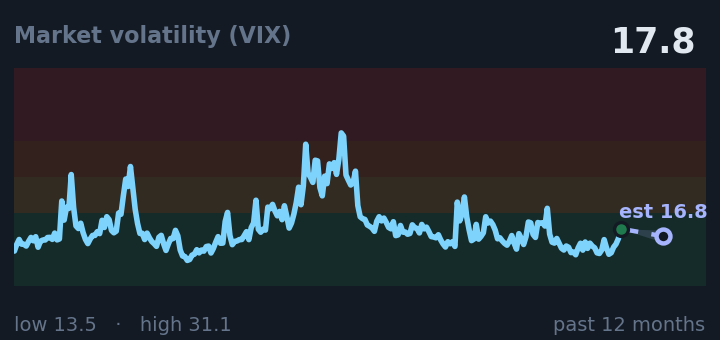
Market volatility at 17.8 reflects moderate investor concern about unexpected moves.
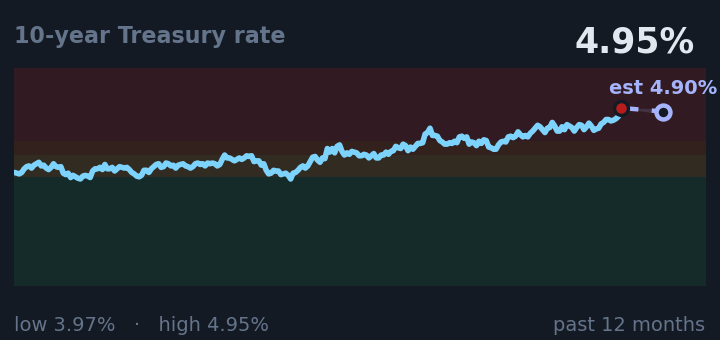
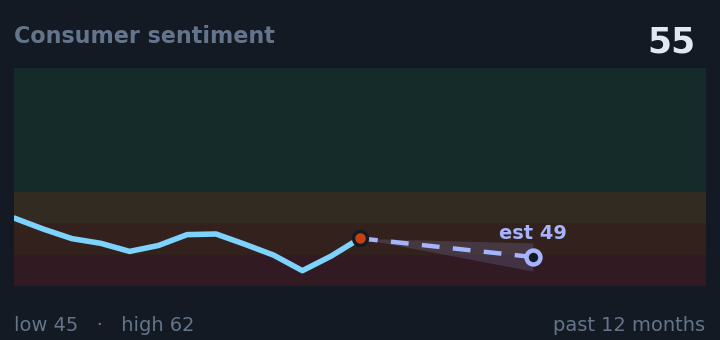
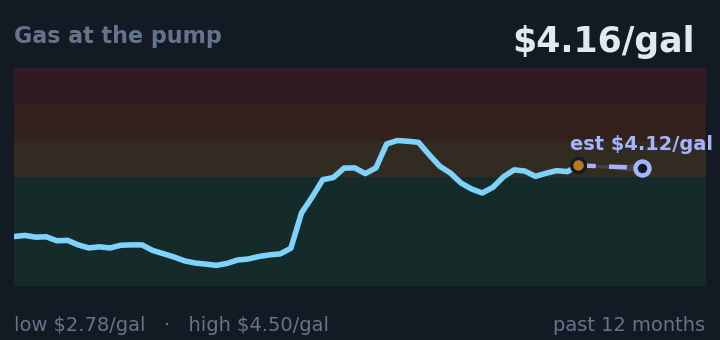
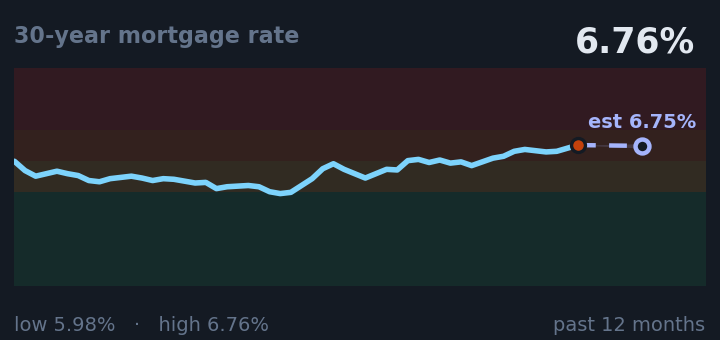
Source: FREDOn September 11th this brief named Belit Onay's chances at winning Hannover's mayoral race at 33% YES, and the market's price has risen to 70% since, a move of 36 points in 2 days. A separate market moved with far greater drama: Cabinet stability, priced at 61% YES for no departures before 2027, jumped 55 points in a single day, about 18 times its normal daily move. Three of the day's five biggest movers cluster in the Americas, split between political and athletic markets. The month-long backdrop of rising borrowing costs continues, with the 10-year Treasury now at 4.95%, in the zone where policy reversals have forced pauses, while the 30-year mortgage rate sits at 6.76%. Consumer sentiment has drifted upward to 55 over the month but remains below the 60 threshold where spending rebounds, and gas at $4.16 echoes the wallet pressure of recent weeks.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Market volatility at 17.8 reflects moderate investor concern about unexpected moves.
Source: FRED
The 10-year Treasury at 4.95% sets the floor for all long-term borrowing and sits where policy reversals have historically occurred.
Source: FRED
Consumer sentiment at 55 indicates households are cautious about their finances and pulling back on spending.
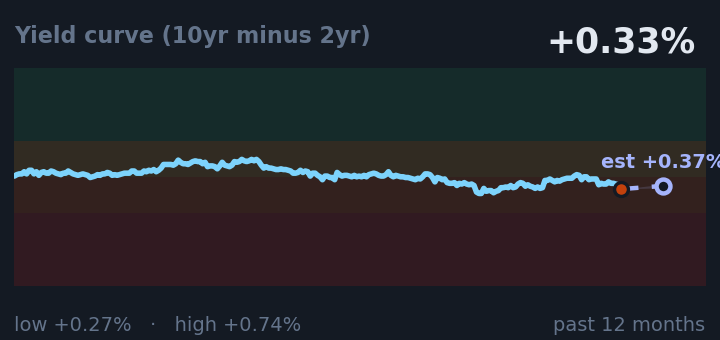
A flattening yield curve at 0.33% historically precedes economic slowdown within a year.
Source: FRED
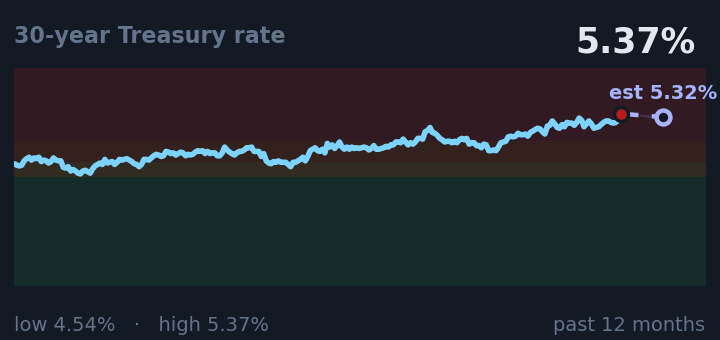
The 30-year Treasury above 5% signals concerns about government deficits, with most new spending going to interest costs.
Source: FRED
Gas at $4.16 historically correlates with voters becoming less confident in political leadership.
Mortgage rates at 6.76% mean households spend more on interest and have less for consumption and home purchases.
Source: FRED
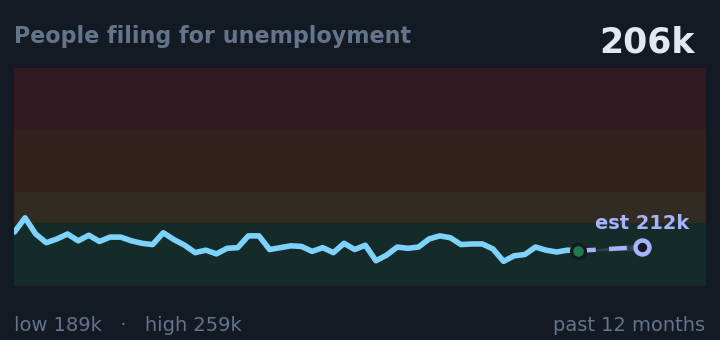
Jobless claims at 206k indicate a stable labor market, while borrowing costs continue rising.
Source: FREDIn plain terms: the public’s money is leaning that this will not happen, and held steady overnight.
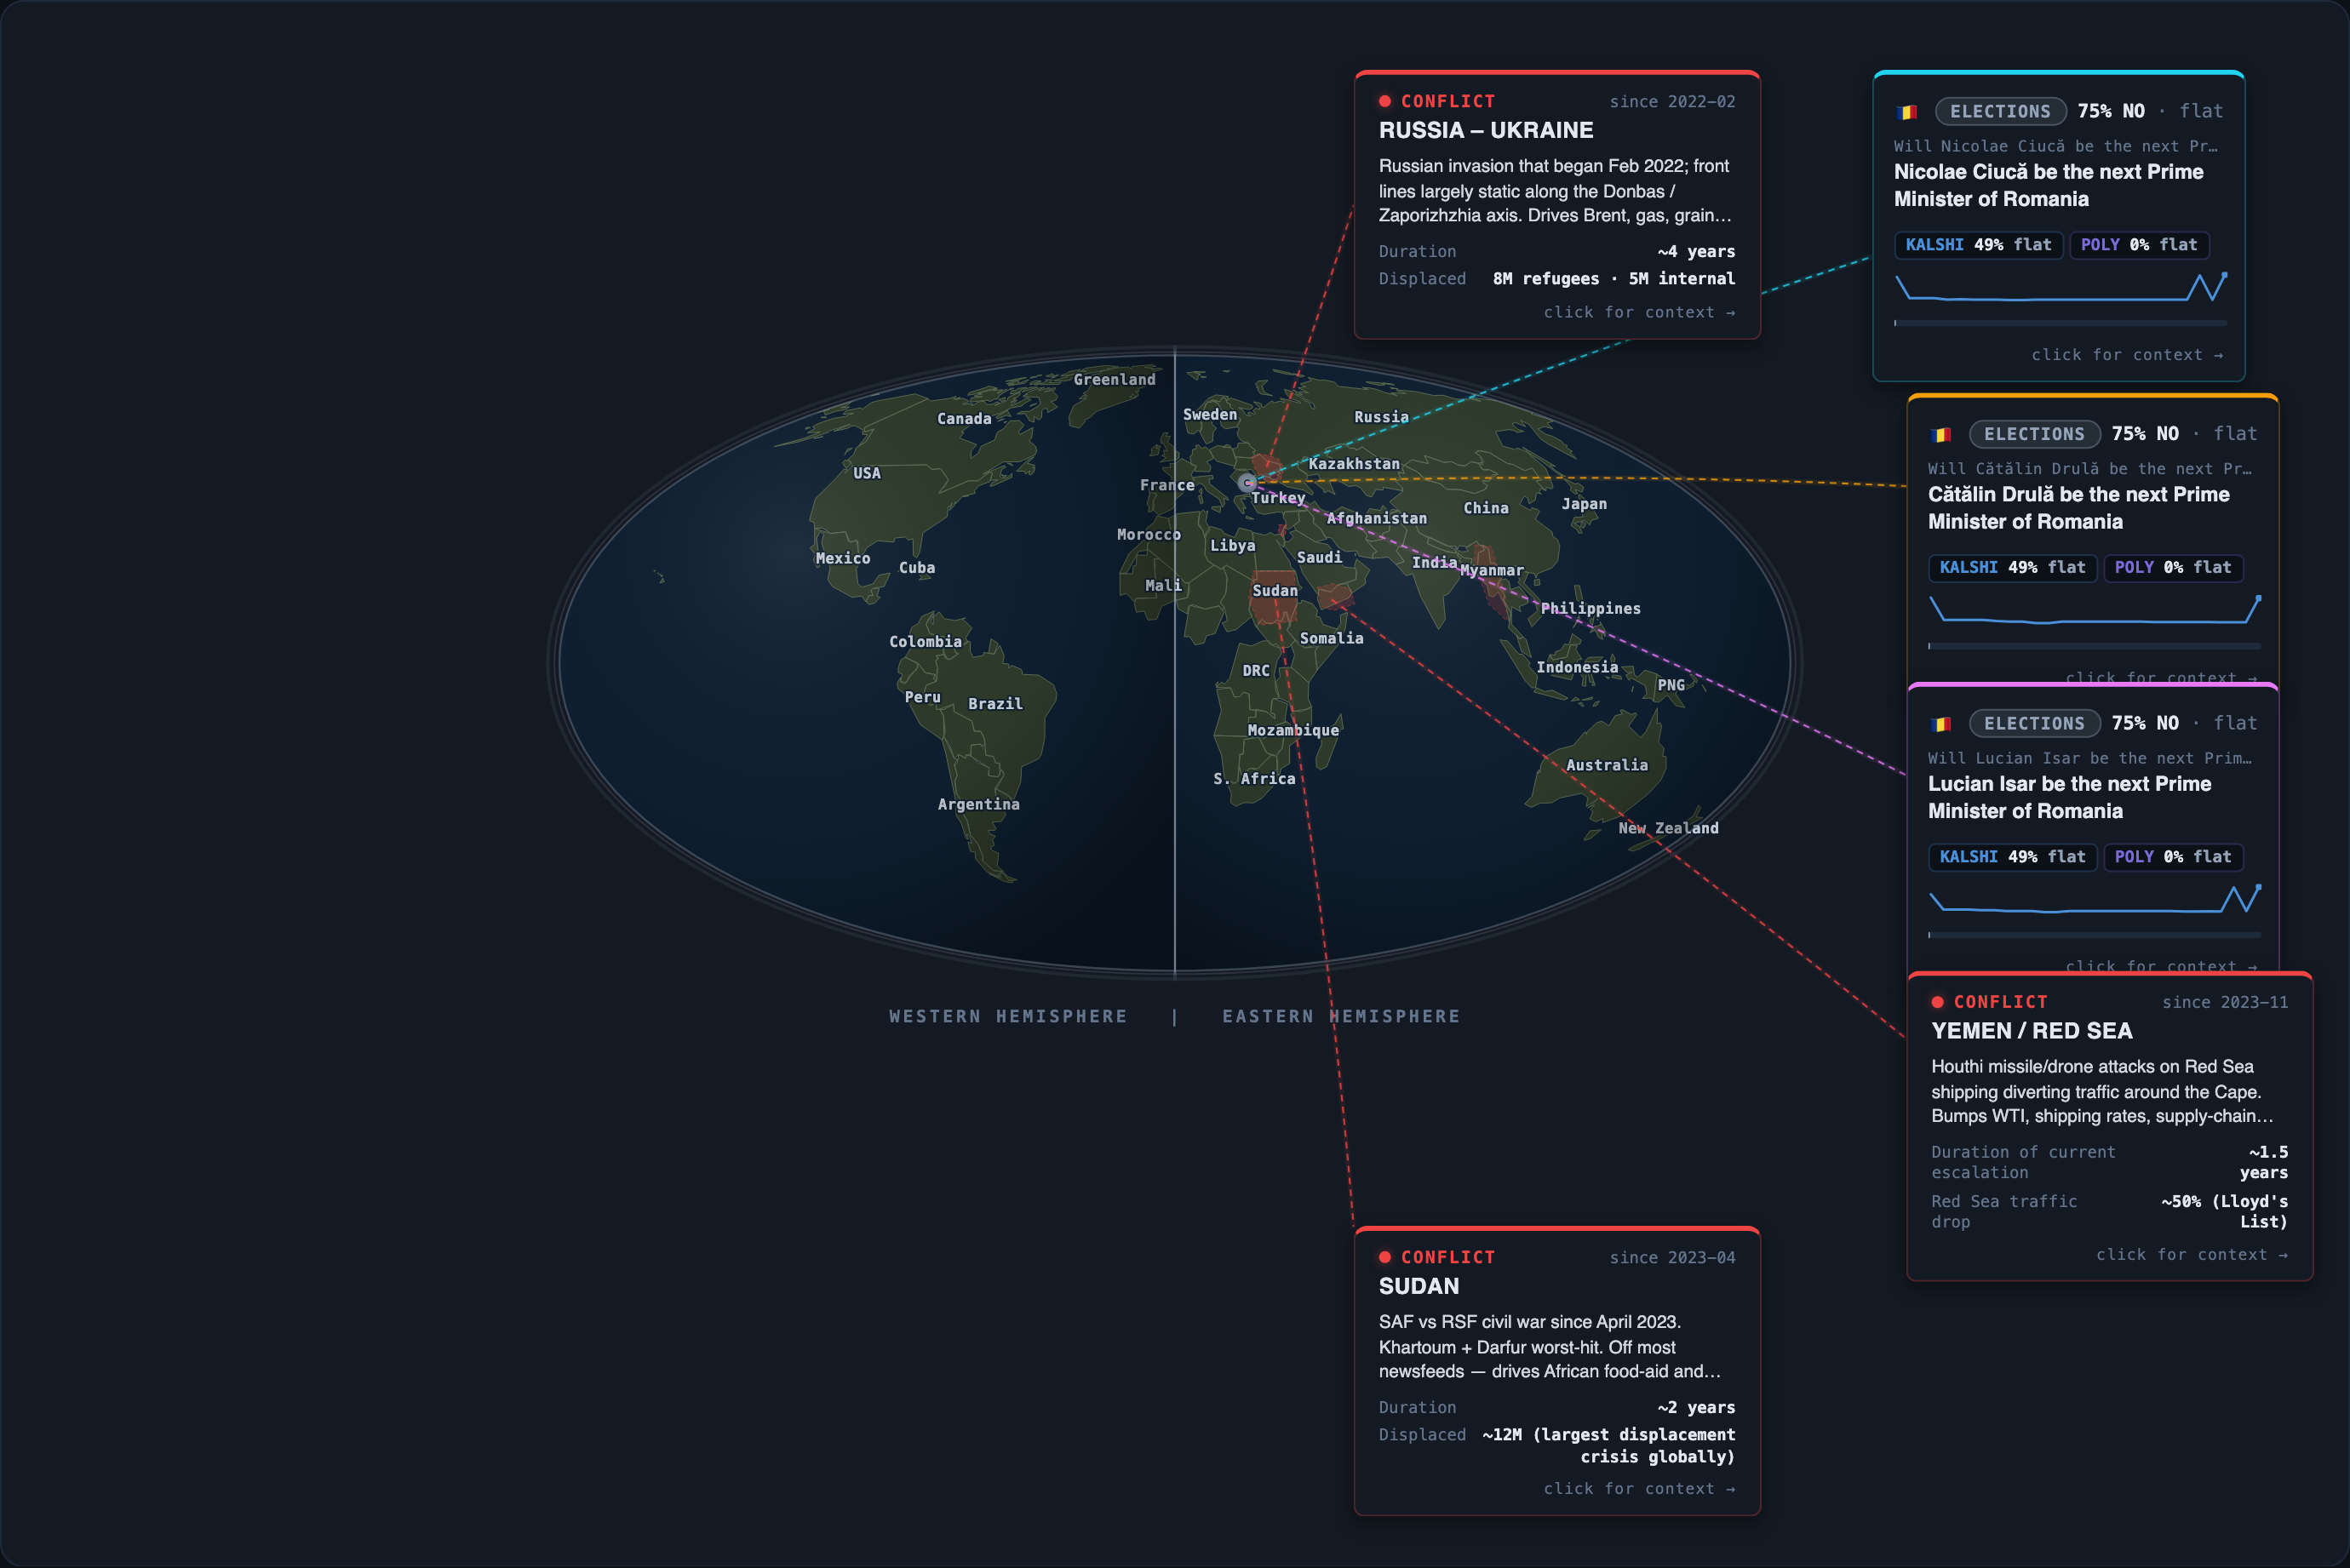
Two major prediction platforms show extreme consensus (0-2%) that Ciucă won't become next PM, suggesting market confidence in this outcome. The 2-point spread indicates near-certainty, making this a low-uncertainty political event despite broader economic headwinds.
In plain terms: the public’s money is leaning that this will not happen, and held steady overnight.
Low-probability event with tight 2-point spread between Polymarket (1%) and Kalshi (3%), suggesting genuine uncertainty despite depressed consumer sentiment (57) and elevated energy costs that typically undermine incumbent support. Agreement at such low levels indicates markets s
In plain terms: the public’s money is leaning that this will not happen, and held steady overnight.
Extremely niche prediction on a relatively unknown Romanian politician with minimal market interest (0-2% pricing). The tight spread reflects low liquidity rather than genuine uncertainty—depressed consumer sentiment and elevated energy costs create broader political volatility,
In plain terms: the public’s money is leaning that this will not happen, and held steady overnight.
Polymarket-Kalshi spread (0%-4%) on a fringe candidate reflects data scarcity and low conviction. Depressed consumer sentiment (57) and elevated gas prices may weaken incumbent parties, potentially benefiting anti-establishment figures like Simion, but 4% baseline suggests neglig
In plain terms: the public’s money is leaning that this will not happen, and held steady overnight.
Matched event shows tight 2-point spread (2% Polymarket vs 4% Kalshi) for a low-probability outcome. Agreement near 3% suggests minimal market conviction; depressed consumer sentiment (57) and elevated gas prices may constrain any anti-incumbent sentiment that could elevate an al
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 0 flat |
| EUROPE | 0 rose 0 fell 5 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |