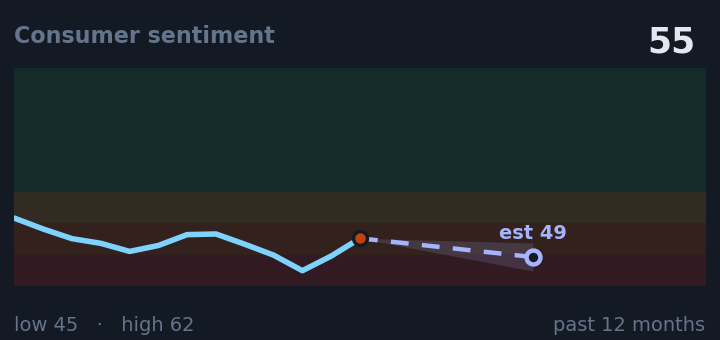
Consumer sentiment at 55 is below the recessionary threshold of 60 and reflects whether households feel confident enough to spend and invest.
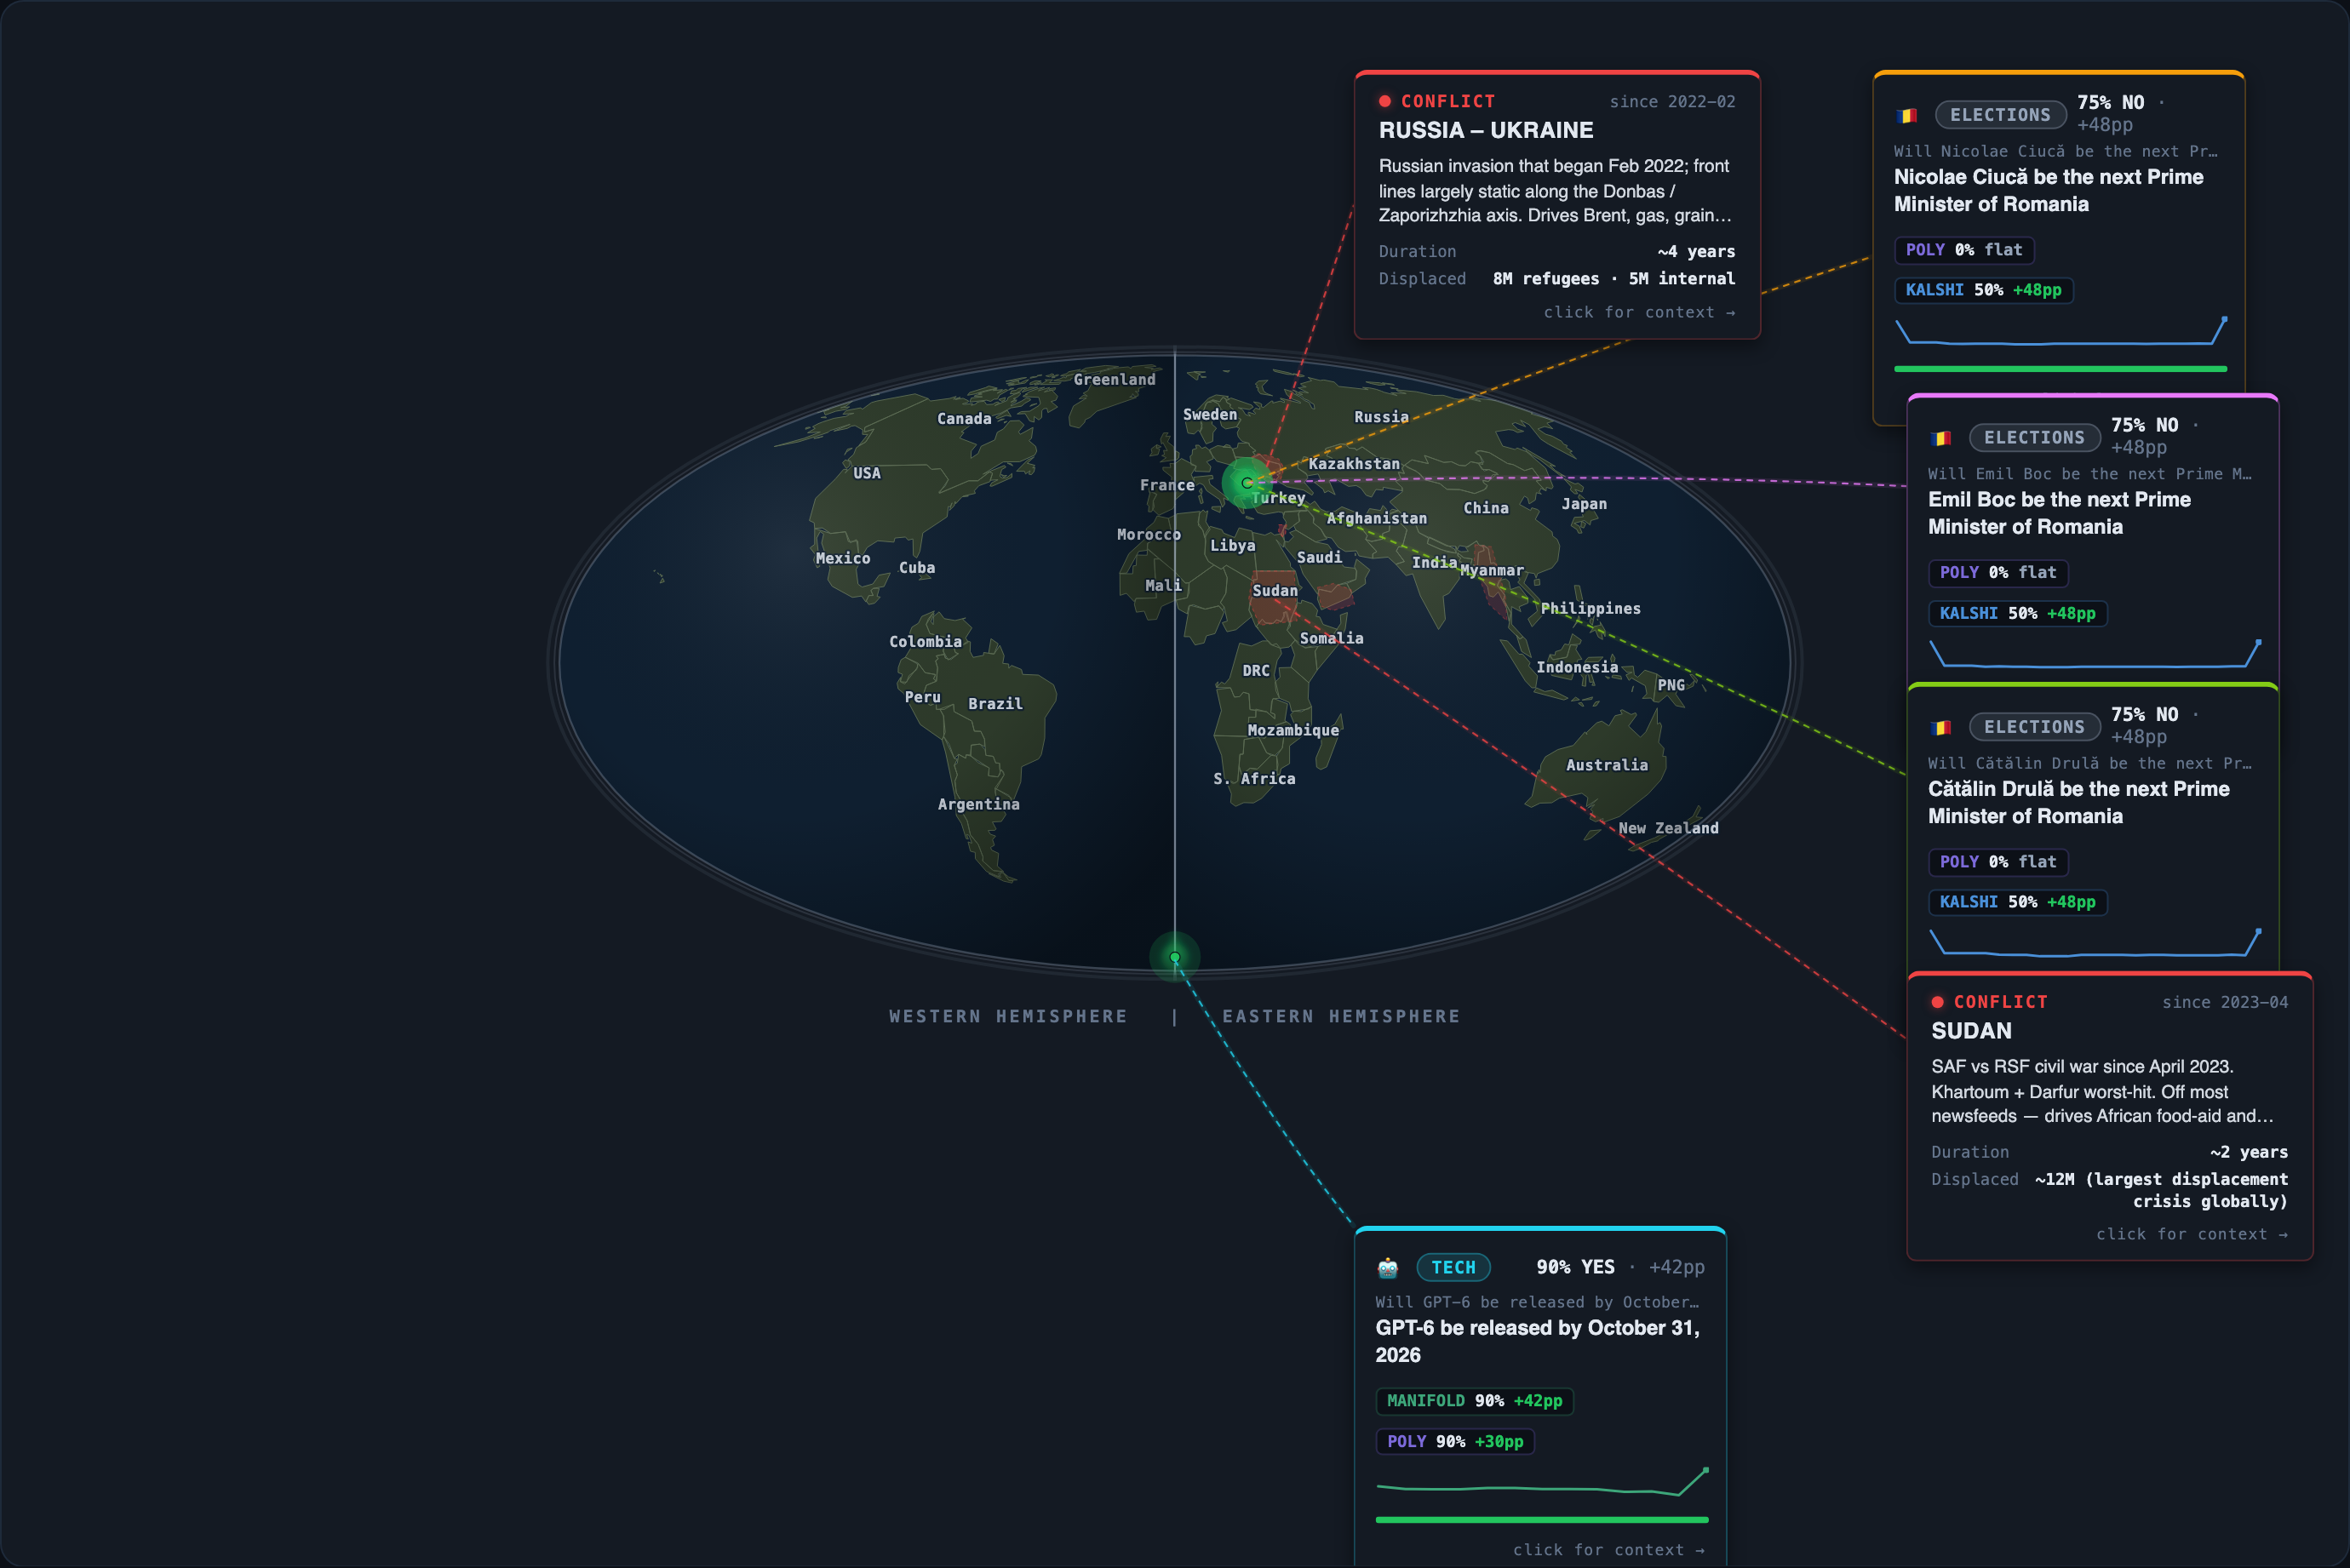
The market's price on Eugen Tomac becoming Romania's next Prime Minister has risen 22 points and now reads 75% NO, one of Europe's clearest political moves in recent weeks. The Goldman Sachs and OpenAI underwriter question from August 30th surged to 69% YES, a move of 34 points in three days, putting control of a major AI company's IPO into bankers' hands as tech valuations affect who keeps jobs. Mortgage rates climbed to 6.66%, jobless claims rose to 203,000, and consumer sentiment rose to 55 but stays depressed, extending the month-long wallet pressure. The rest of the board scattered across unlocated questions about entertainment and technology releases, with no immediate household impact. VIX, gas prices, and Treasury yields remain unchanged over the past month.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Consumer sentiment at 55 is below the recessionary threshold of 60 and reflects whether households feel confident enough to spend and invest.
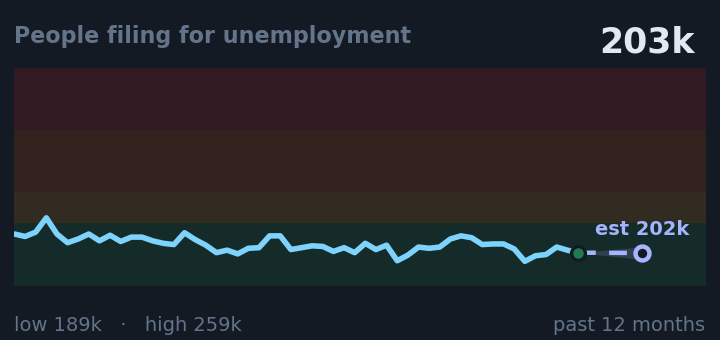
Initial jobless claims at 203,000 measure how many people are losing their jobs each week, directly affecting household income stability and family spending plans.
Source: FRED
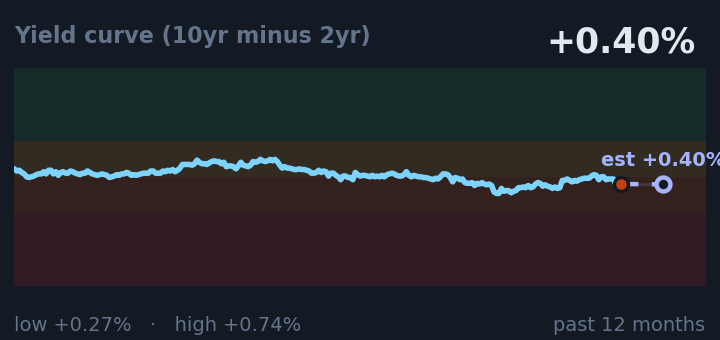
The yield curve spread of 0.40% is the difference between what it costs to borrow for 10 years versus 2 years, affecting borrowing costs across the entire economy.
Source: FRED
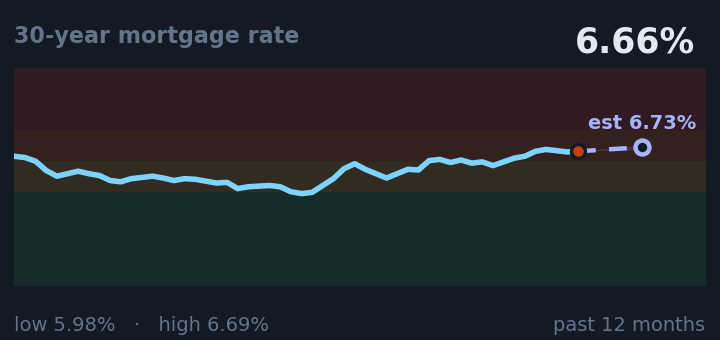
30-year mortgage rates at 6.66% are near their highest in the past year and directly determine what households can afford to borrow for home purchases.
Source: FRED
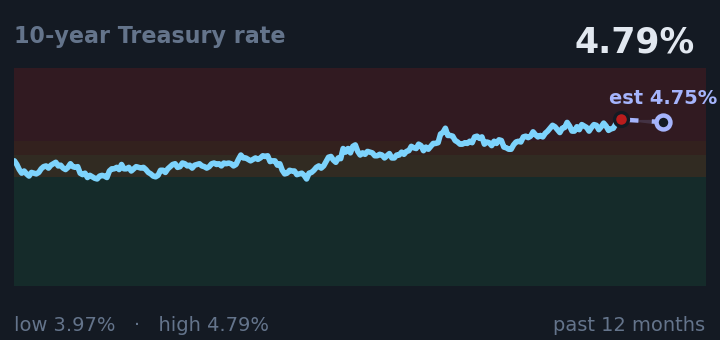
10-year Treasury yields at 4.75% are in the bond vigilante pressure zone, where historically high borrowing costs have forced policy reversals like the April 2025 tariff pause.
Source: FRED
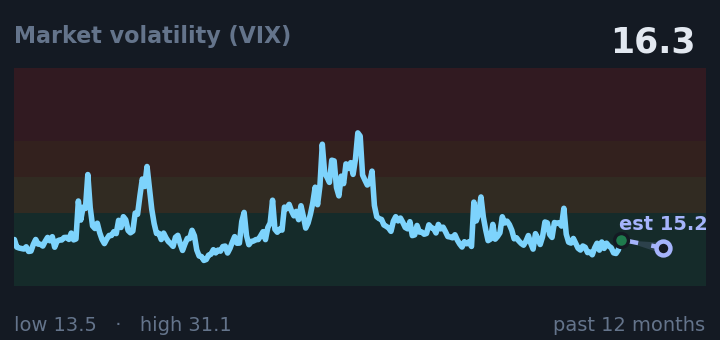
Market volatility (VIX) at 16.3 is in the normal range and indicates investors are neither panicked nor overly confident about future stock market swings.
Source: FRED
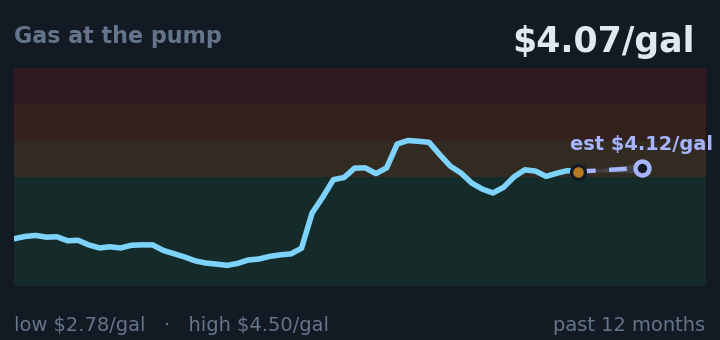
Gas at $4.07/gal affects the cost of commuting and shipping, influencing both personal transportation budgets and broader inflation for everything households buy.
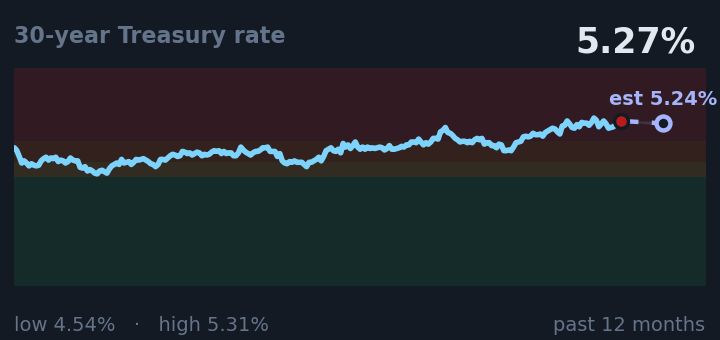
30-year Treasury yields at 5.25% are in the fiscal sustainability crisis zone, where high government borrowing costs make deficit financing more expensive and mortgage rates rise.
Source: FRED
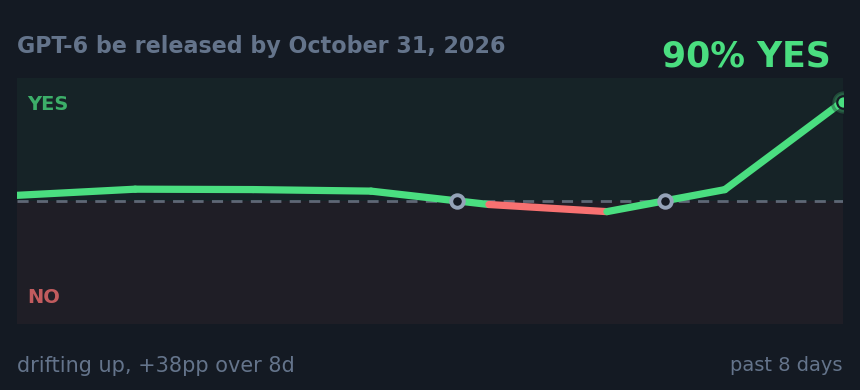
In plain terms: the public’s money is very confident this will happen, and grew much more sure overnight.
Manifold and Polymarket agree on a 4-point spread, with Polymarket pricing slightly higher at 56%, indicating a moderate consensus that GPT-6 will be released by the given date.
In plain terms: the public’s money is leaning that this will not happen, and grew much less sure overnight.
Two major prediction platforms show extreme consensus (0-2%) that Ciucă won't become next PM, suggesting market confidence in this outcome. The 2-point spread indicates near-certainty, making this a low-uncertainty political event despite broader economic headwinds.
In plain terms: the public’s money is leaning that this will not happen, and grew much less sure overnight.
Polymarket-Kalshi spread (0%-2%) on a low-probability event suggests minimal disagreement on Boc's slim chances. Depressed consumer sentiment and elevated gas prices may further reduce his viability in upcoming political transitions.
In plain terms: the public’s money is leaning that this will not happen, and grew much less sure overnight.
Low-probability event with tight 2-point spread between Polymarket (1%) and Kalshi (3%), suggesting genuine uncertainty despite depressed consumer sentiment (57) and elevated energy costs that typically undermine incumbent support. Agreement at such low levels indicates markets s
In plain terms: the public’s money is leaning that this will not happen, and grew much less sure overnight.
Polymarket-Kalshi spread (0%-4%) on a fringe candidate reflects data scarcity and low conviction. Depressed consumer sentiment (57) and elevated gas prices may weaken incumbent parties, potentially benefiting anti-establishment figures like Simion, but 4% baseline suggests neglig
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 0 flat |
| EUROPE | 4 rose 0 fell 0 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |