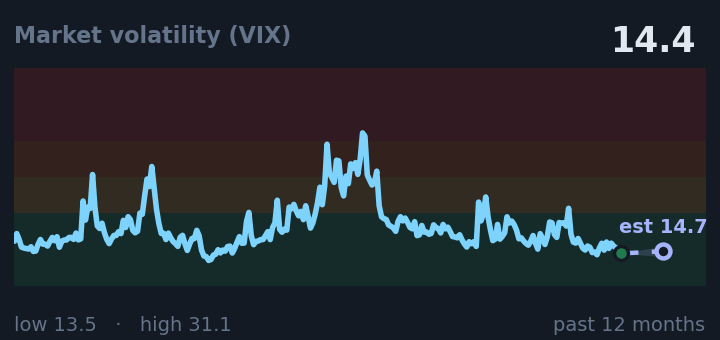
Market volatility at 14.5 signals investors are complacent; historically, this calm can make unexpected shocks more painful.
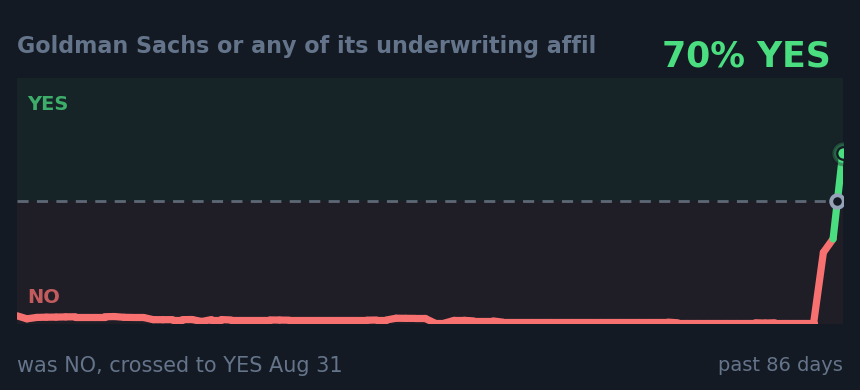
The market's price on Goldman Sachs serving as lead underwriter on OpenAI's initial public offering crossed the 50% line to YES today, now reading 70%, up 36 points today and 70 over the week, one of the month's clearest moves.
Four of the five biggest movers sit in the United States, clustered around politics and sports: whether Novak Djokovic wins the US Open, whether Trump cabinet members exit, and the Republicans' Senate and House seat prospects in 2026. On August 27th this brief named the Trump Press Secretary market at 32% YES; the market has fallen to 19% since, a move of 14 points in 4 days. If you follow tech equity pricing or have interest in the OpenAI IPO, traders are now overwhelmingly confident Goldman will lead the underwriting, giving the bank significant control over the IPO terms. This morning's move is unrelated to the month-long household pressures that continue defining the backdrop.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Market volatility at 14.5 signals investors are complacent; historically, this calm can make unexpected shocks more painful.
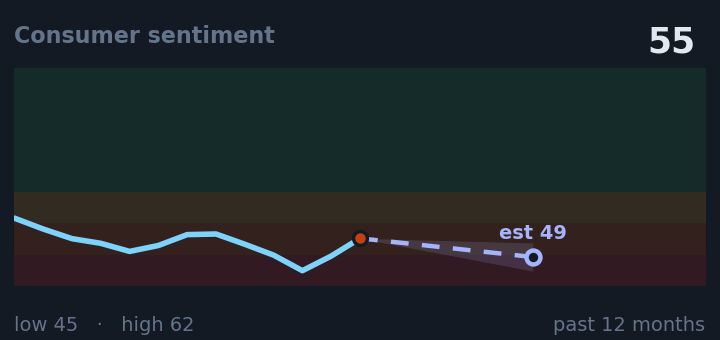
Consumer sentiment at 55 means American households still feel financial pressure despite a slight improvement this month.
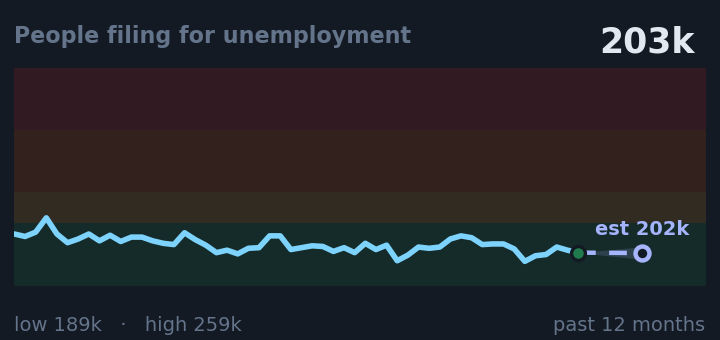
Jobless claims at 203k show the labor market remains intact, though rising from 189k a month ago.
Source: FRED
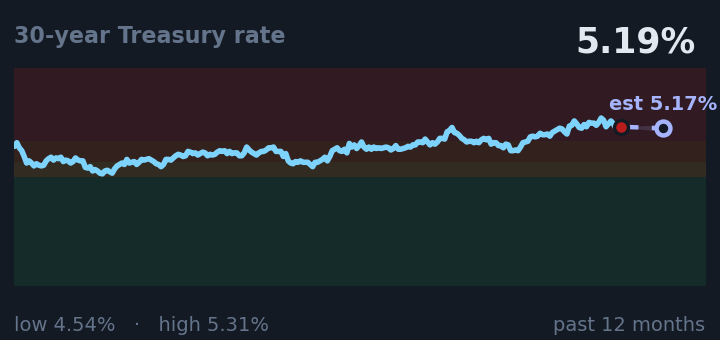
Thirty-year Treasury rates at 5.19% drive mortgage rates and signal fiscal stress where government borrowing costs spiral higher.
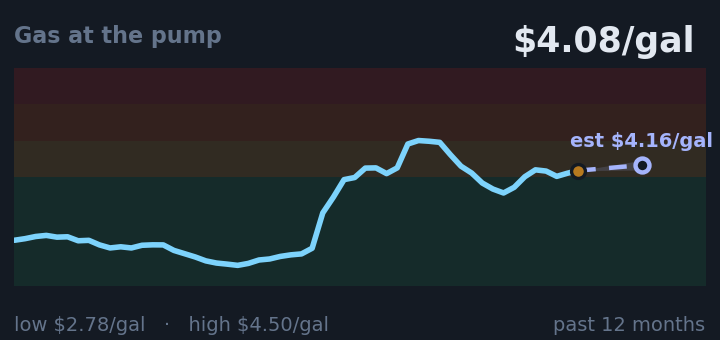
Gas at $4.08 a gallon costs families thousands per year in commuting and errands, up from $4.00 a month ago.
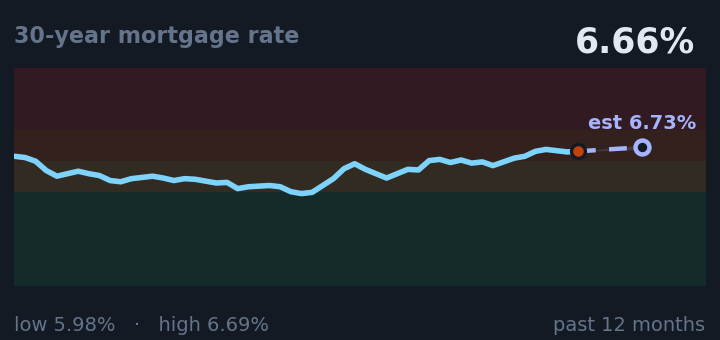
Mortgage rates at 6.66% price homebuyers out of the market and reset the carrying costs on variable-rate debt.
Source: FRED
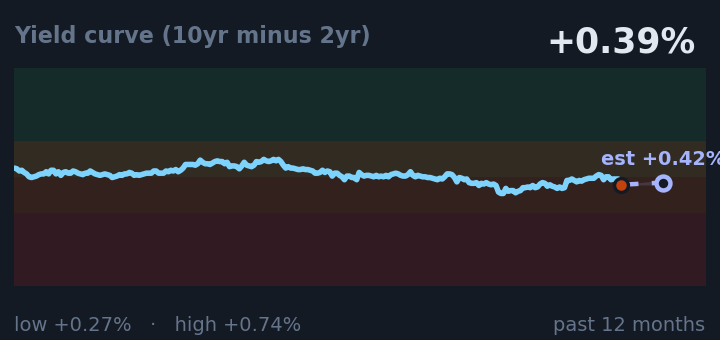
The yield curve at 0.39% spread is flattening toward inversion, a historically reliable recession signal.
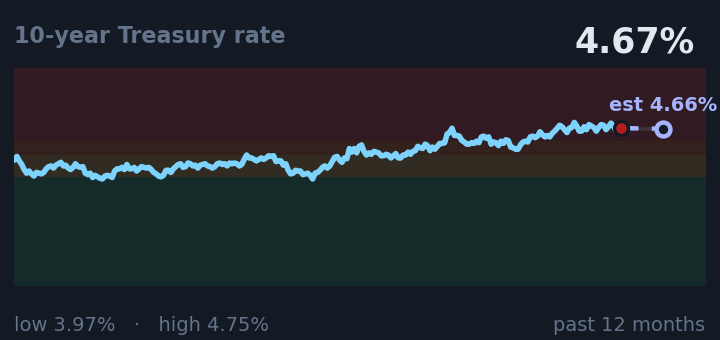
The 10-year Treasury rate at 4.67% sits in the bond vigilante pressure zone, where policy makers have historically reversed course.
In plain terms: the public’s money is leaning that this will happen, and held steady overnight.
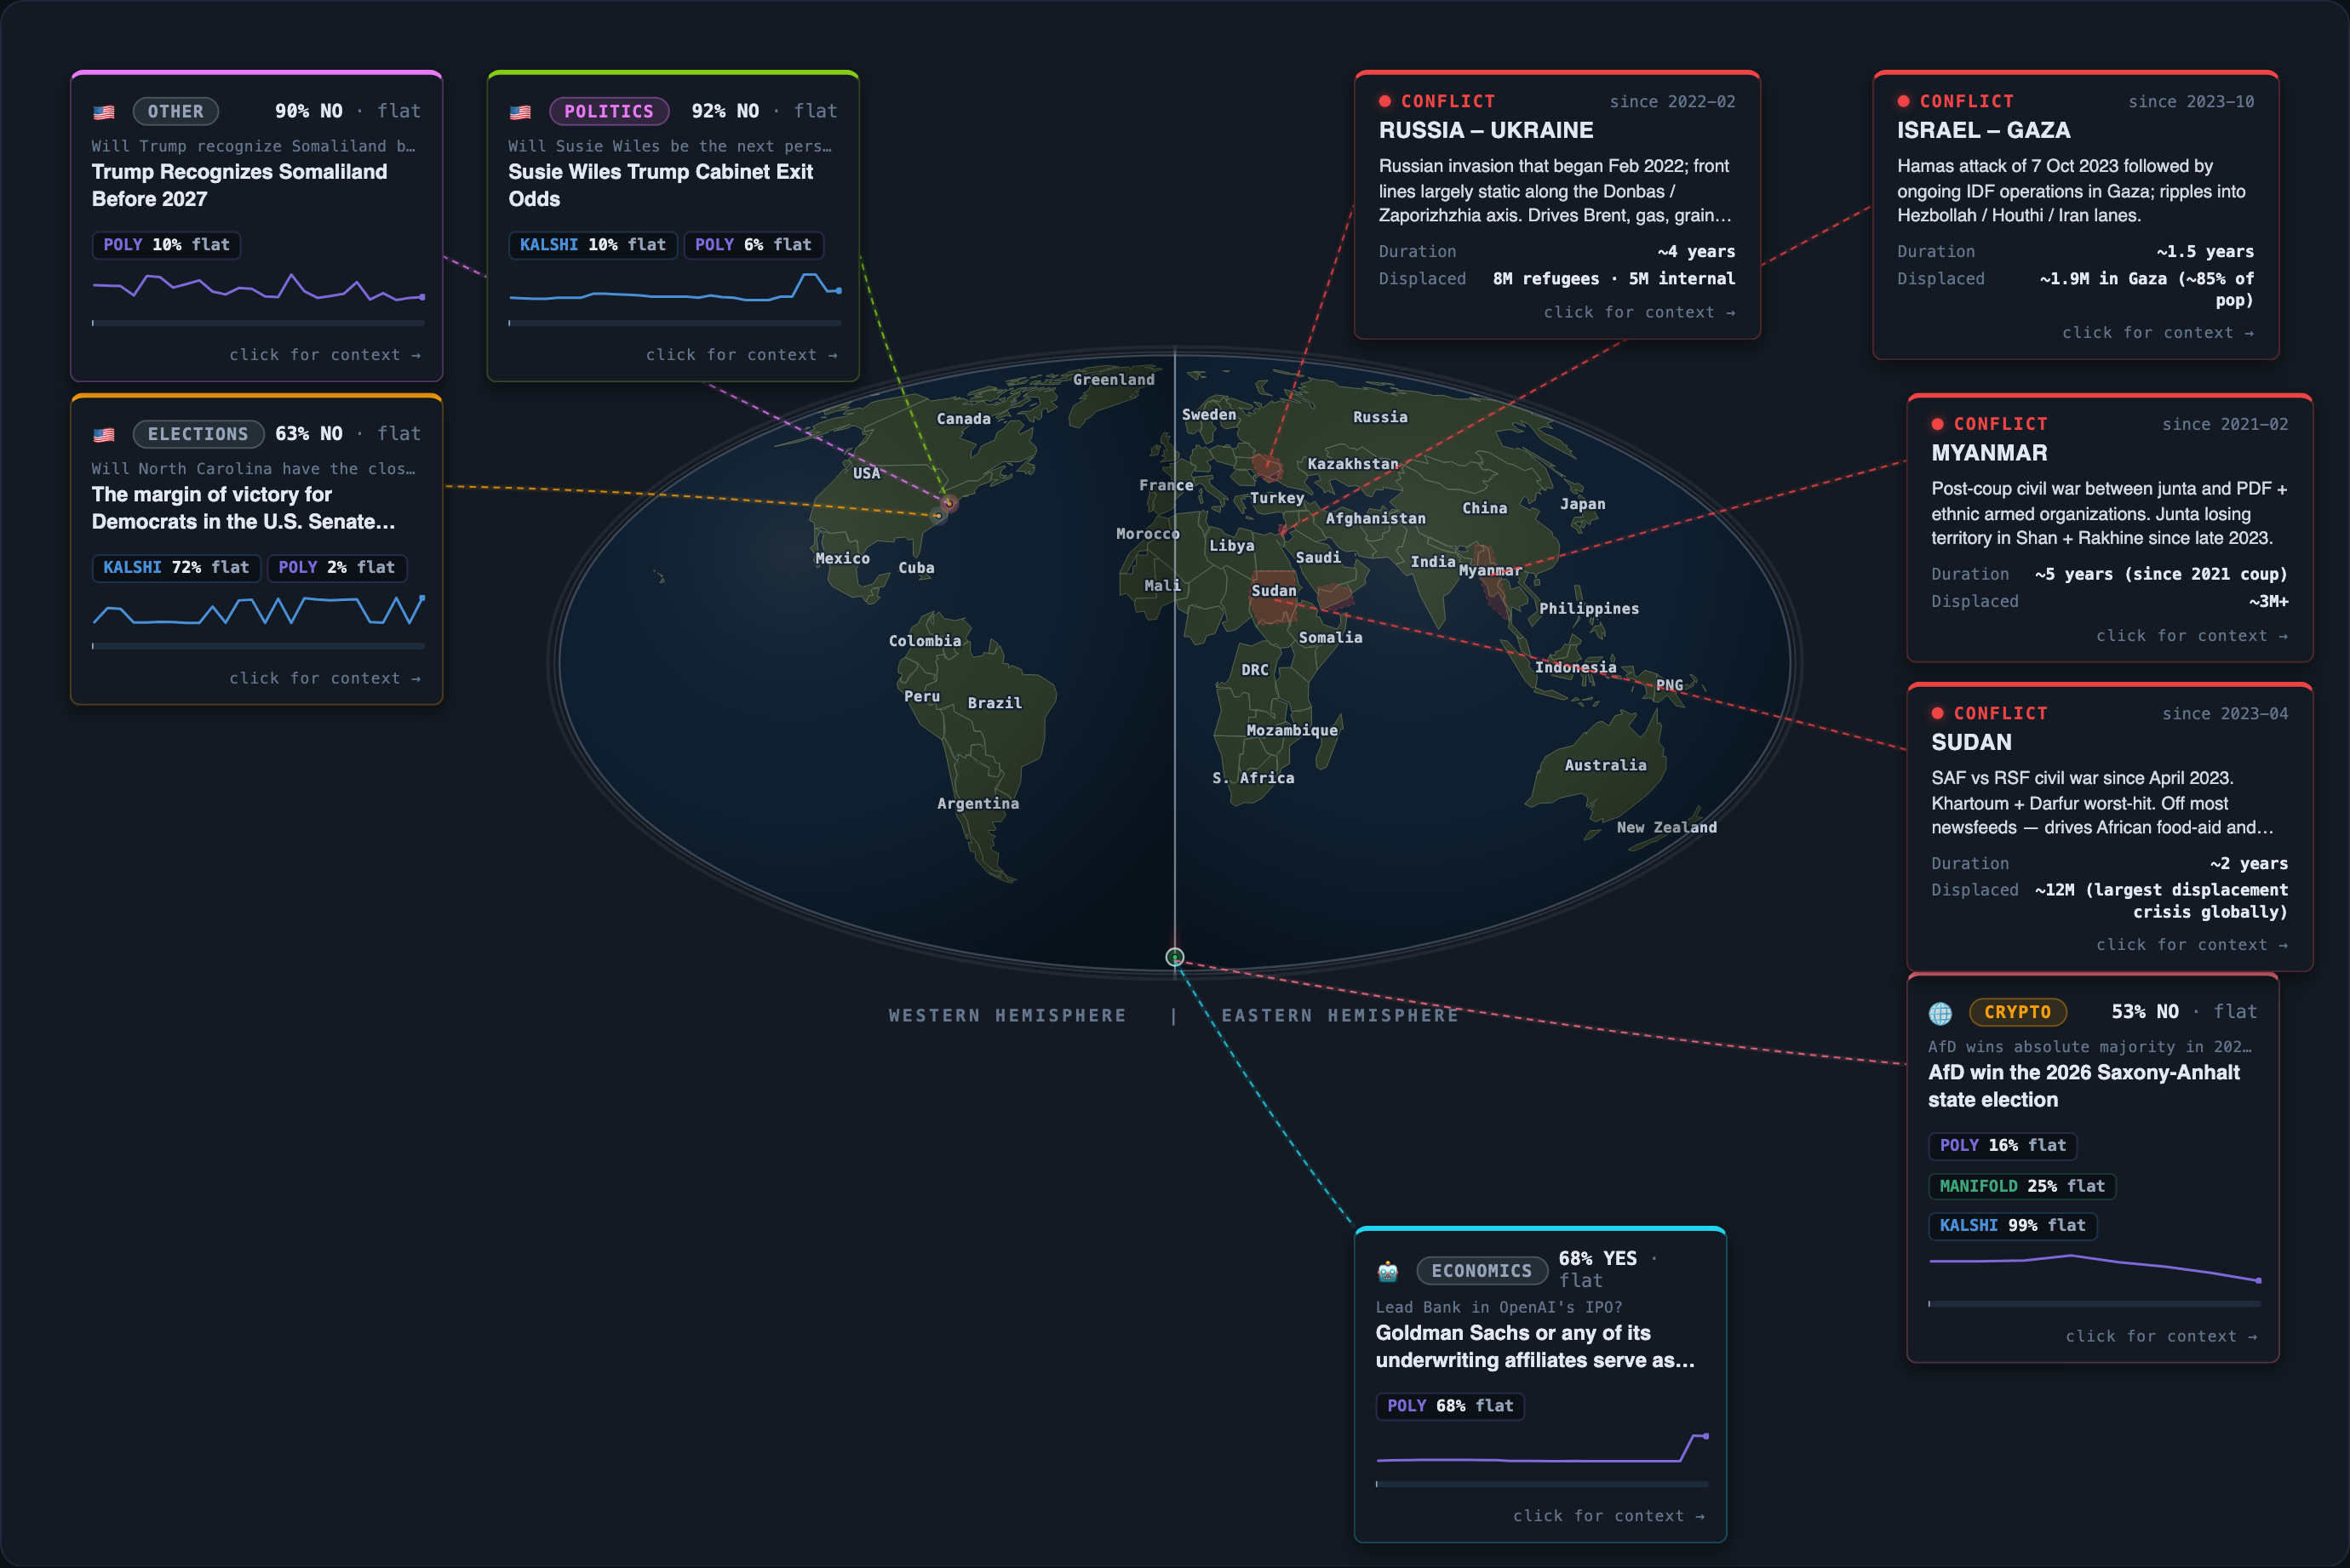
Polymarket prices Deutsche Bank at 1% to lead OpenAI's IPO, indicating a strong consensus among traders, while Kalshi has no price, suggesting a lack of market participation or uncertainty.
In plain terms: the public’s money is close to a coin flip on whether this will not happen, and held steady overnight.
Both platforms agree on an average probability of 11%, indicating a low confidence level among market participants regarding North Carolina's Senate race being the closest in 2026, with no significant price difference between them.
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Massive 48-point spread between Kalshi (63%) and Polymarket (15%) on U.S. recognition of breakaway Somaliland. Disagreement likely reflects different interpretations of Trump's foreign policy priorities, geopolitical constraints with Somalia, and whether recognition occurs via ex
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
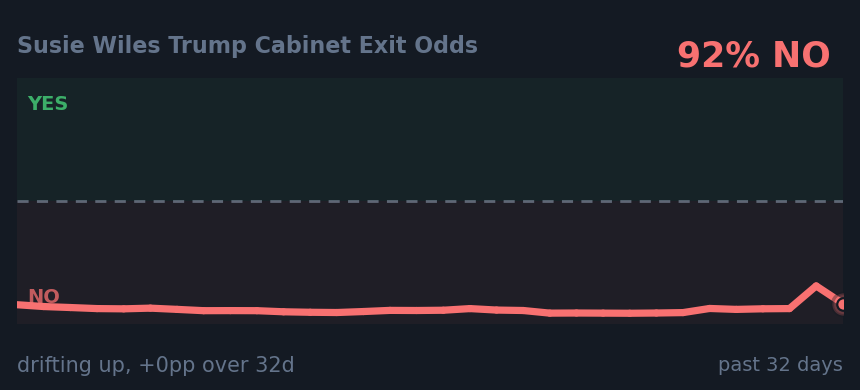
Polymarket and Kalshi agree on a 2-point spread with an average probability of 7%, indicating moderate consensus on the likelihood of Susie Wiles leaving the Trump Cabinet, but differing in their specific prices.
In plain terms: the public’s money is close to a coin flip on whether this will not happen, and held steady overnight.
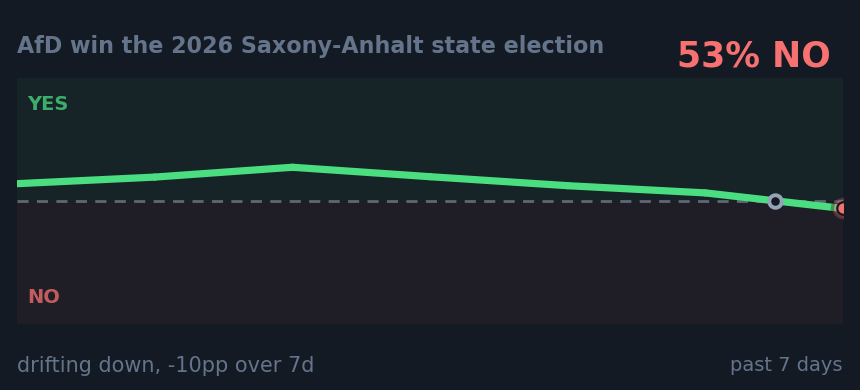
Manifold prices AfD at 25% for an absolute majority, while Kalshi's near-100% price indicates strong confidence in their win, highlighting a significant disagreement between platforms on the outcome's likelihood.
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds โ drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 3 flat |
| EUROPE | 0 rose 0 fell 0 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |