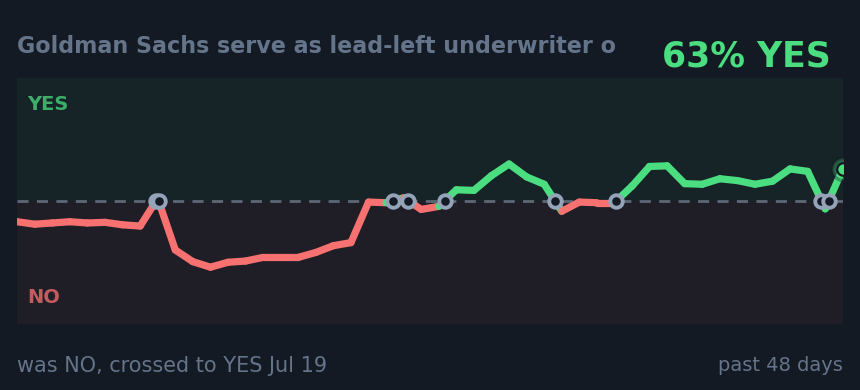
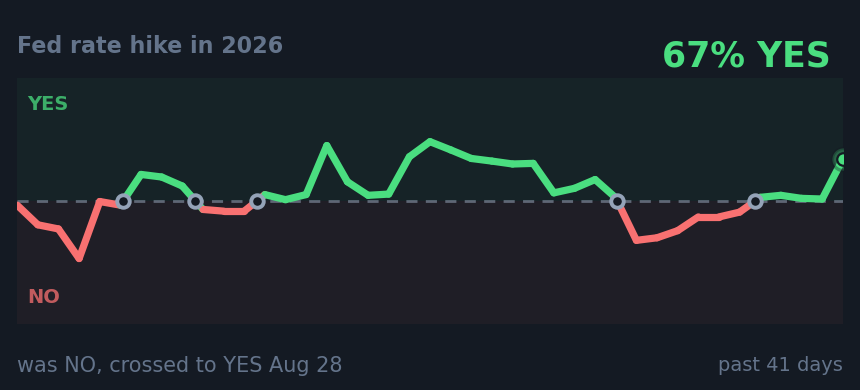
Market volatility (VIX)
Normal
14.5
down from 18.2 a month ago, near its lowest in the past year.
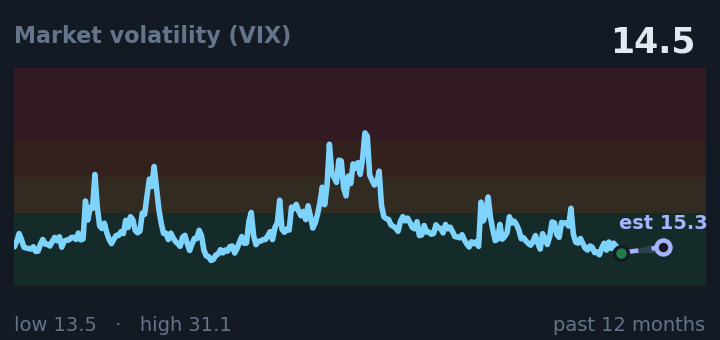
Market volatility (VIX) at 15.2 signals that stock traders expect normal-range price swings, meaning there's little concern about sudden shocks right now.
Connects to: Goldman Sachs Anthropic IPO Underwriter
Source: FRED
Consumer sentiment
Caution
55
up from 50 a month ago, in the middle of its range for the past year.
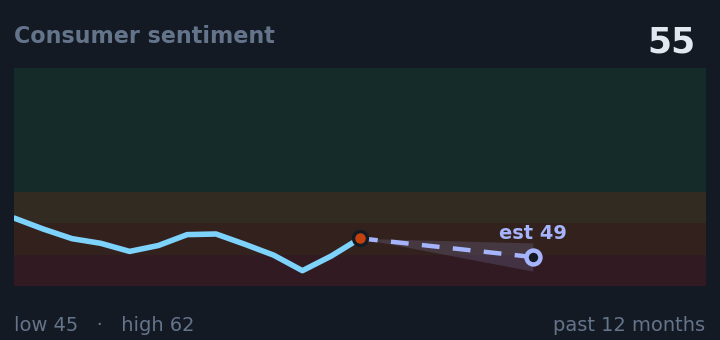
Consumer sentiment at 50 means families are very pessimistic about their financial futures, and this level of depression historically forecasts households cutting back on spending.
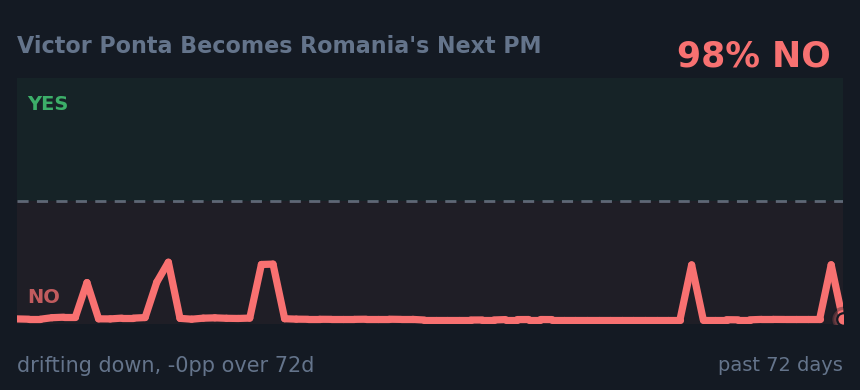
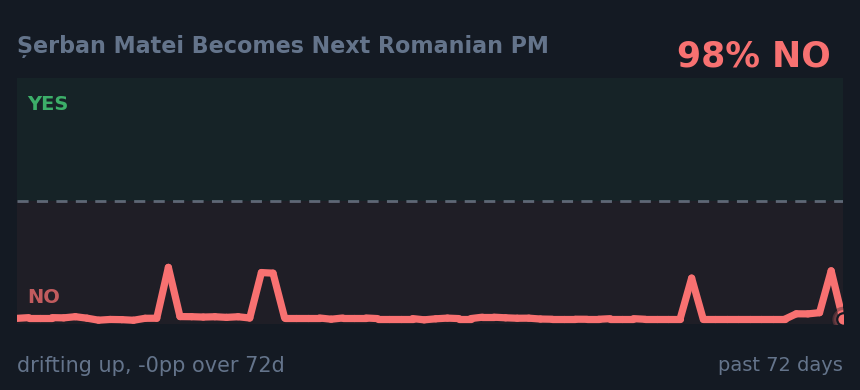
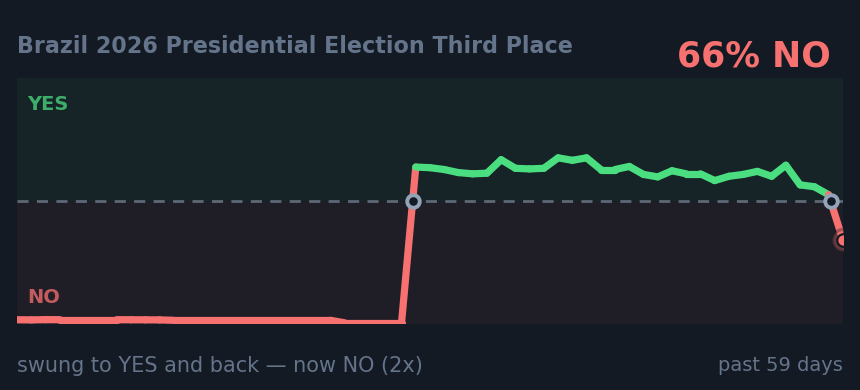
Connects to: Victor Ponta Becomes Romania's Next PM; Șerban Matei Becomes Next Romanian PM; Brazil 2026 Presidential Election Third Place Finisher
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.47%
up from +0.35% a month ago, in the middle of its range for the past year.
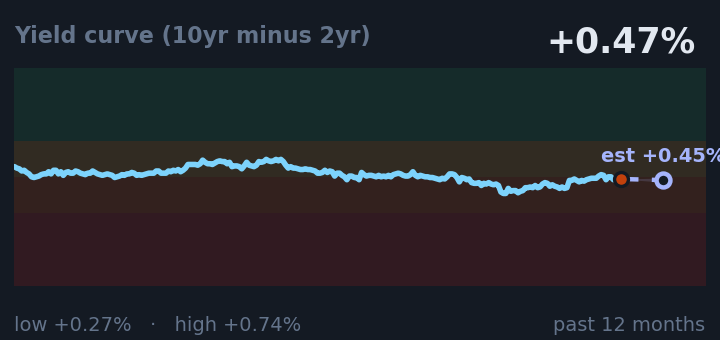
The yield curve, which measures the premium for borrowing long-term (10 years versus 2 years), stands at 0.47%, and when it shrinks or turns negative it has preceded recessions.
Connects to: Goldman Sachs Anthropic IPO Underwriter; Fed Rate Hike in 2026 Agreement
Source: FRED
People filing for unemployment
Normal
203k
up from 189k a month ago, in the middle of its range for the past year.
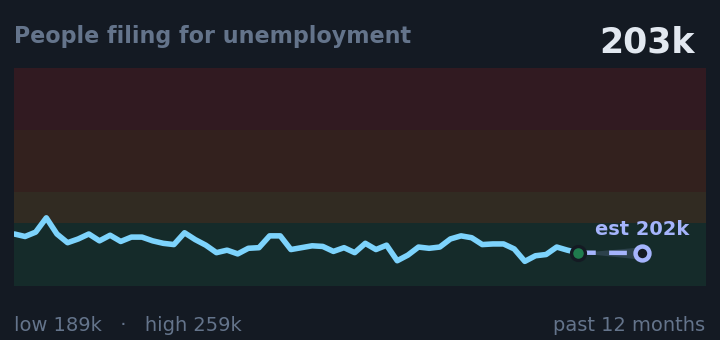
Jobless claims at 203,000 count how many people file for unemployment per week, and the direction this number moves up or down signals whether the job market is tightening or loosening.
Source: FRED
Gas at the pump
Watch
$4.08/gal
up from $4.00/gal a month ago, in the middle of its range for the past year.
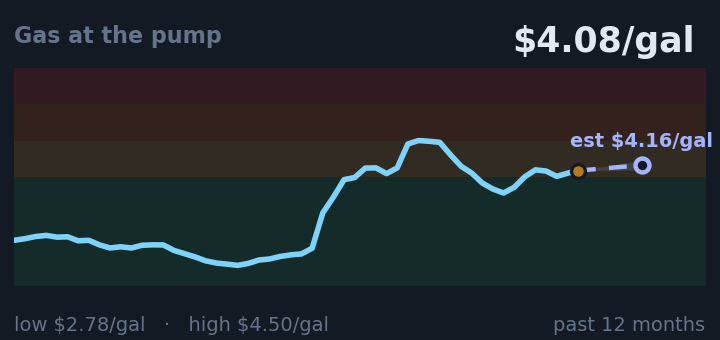
Gas at $4.08 a gallon directly reduces household budgets, and historically when pump prices reach this level voters express lower approval of leaders.
Connects to: Victor Ponta Becomes Romania's Next PM; Șerban Matei Becomes Next Romanian PM; Brazil 2026 Presidential Election Third Place Finisher
Source: FRED
30-year mortgage rate
Caution
6.66%
up from 6.58% a month ago, near its highest in the past year.
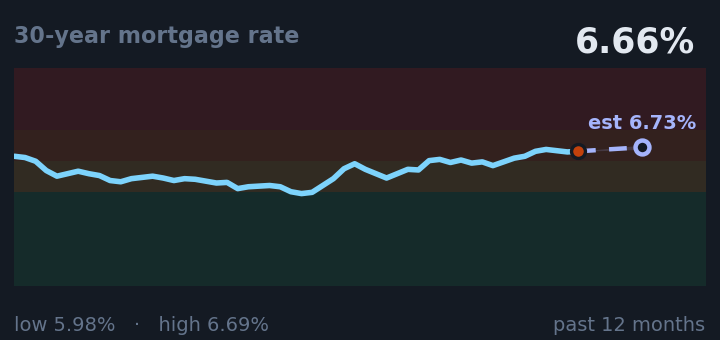
Thirty-year mortgage rates at 6.66% determine how much families pay monthly to buy homes, and rates at the high end of recent ranges suppress how many can qualify to purchase.
Source: FRED
30-year Treasury rate
Warning
5.18%
up from 5.12% a month ago, in the middle of its range for the past year.
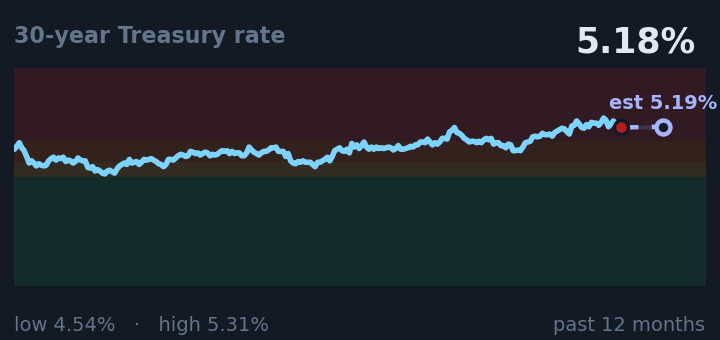
30-year Treasury rate is 5.18%, up from 5.12% a month ago, and in the middle of its range for the past year.
Connects to: Goldman Sachs Anthropic IPO Underwriter; Fed Rate Hike in 2026 Agreement
Source: FRED
10-year Treasury rate
Warning
4.66%
about the same as a month ago, near its highest in the past year.
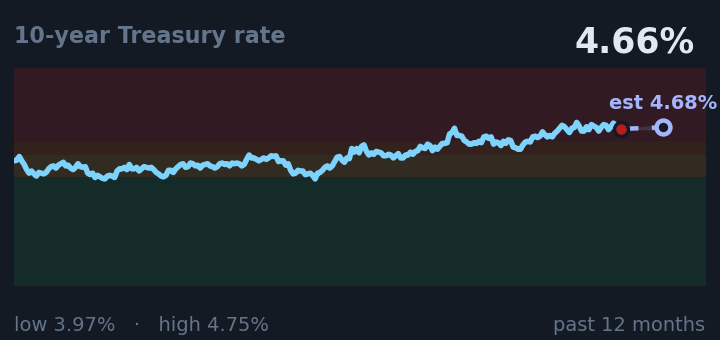
The 10-year Treasury rate at 4.66% sets the baseline cost for long-term borrowing throughout the economy, from mortgages to business loans, and when it rises it signals investor concern about government finances or future inflation.
Connects to: Goldman Sachs Anthropic IPO Underwriter; Fed Rate Hike in 2026 Agreement
Source: FRED