Market volatility (VIX)
Normal
15.2
down from 18.7 a month ago, near its lowest in the past year.
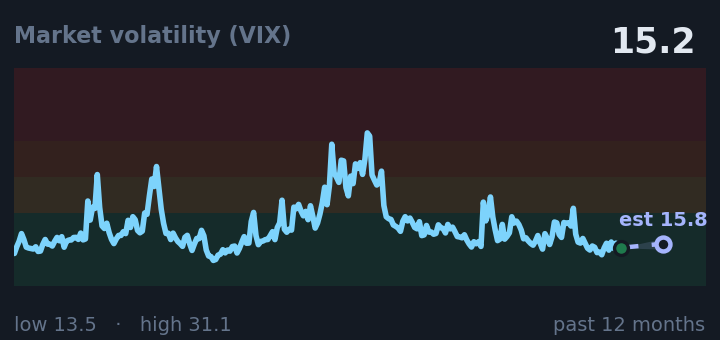
Market volatility at 15.4 is in the calm zone, indicating financial markets expect stable conditions without immediate threats to bank lending or investment flows.
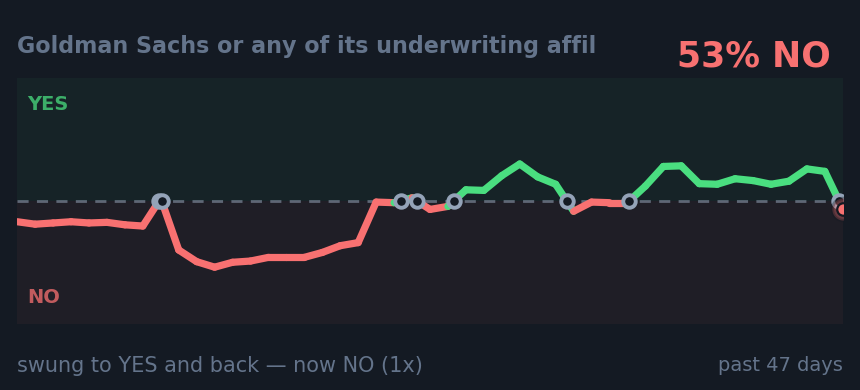
Connects to: Goldman Sachs Anthropic IPO Underwriter
Source: FRED
Consumer sentiment
Warning
50
up from 45 a month ago, in the middle of its range for the past year.
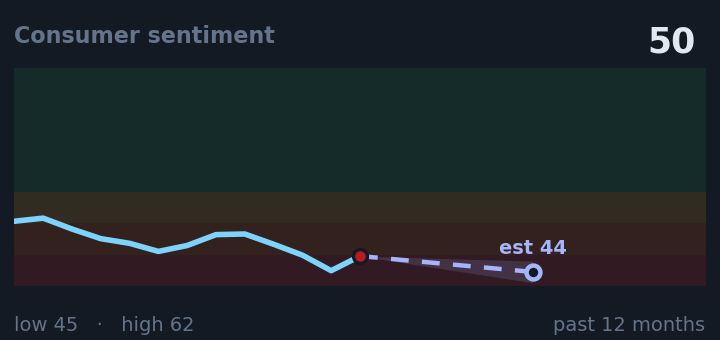
Consumer sentiment at 50 signals severe pessimism about household finances, which means people pull back on major purchases and spending contracts.
Connects to: Grüne Seats Mecklenburg-Vorpommern 2026; Victor Ponta Becomes Romania's Next PM; Șerban Matei Becomes Next Romanian PM
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.47%
up from +0.35% a month ago, in the middle of its range for the past year.
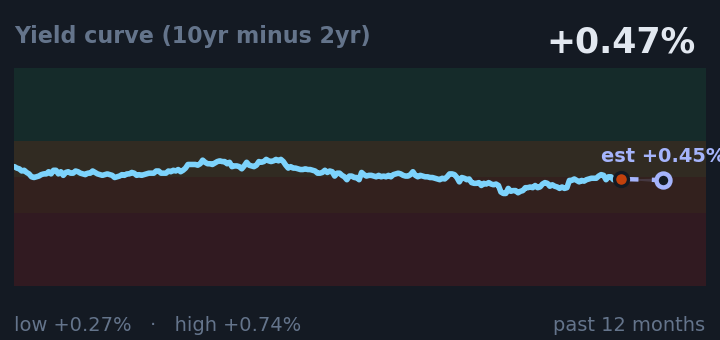
The yield curve spread at 0.47% is the difference between long-term and short-term borrowing costs; historically, when this gap shrinks or inverts to negative, recession risks spike.
Connects to: Goldman Sachs Anthropic IPO Underwriter
Source: FRED
People filing for unemployment
Normal
203k
up from 189k a month ago, in the middle of its range for the past year.
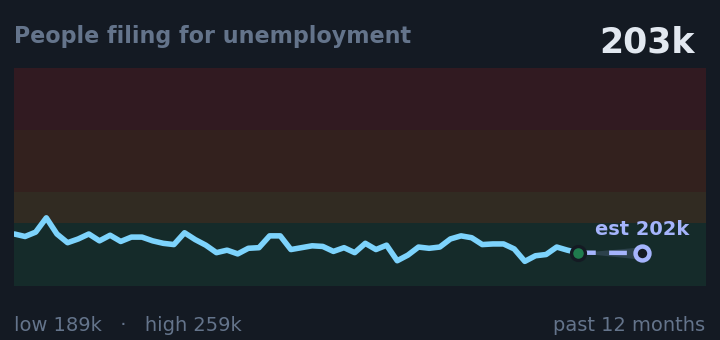
Initial jobless claims at 206,000 mean the labor market remains stable and employers are not cutting headcount.
Source: FRED
Gas at the pump
Watch
$4.08/gal
up from $4.00/gal a month ago, in the middle of its range for the past year.
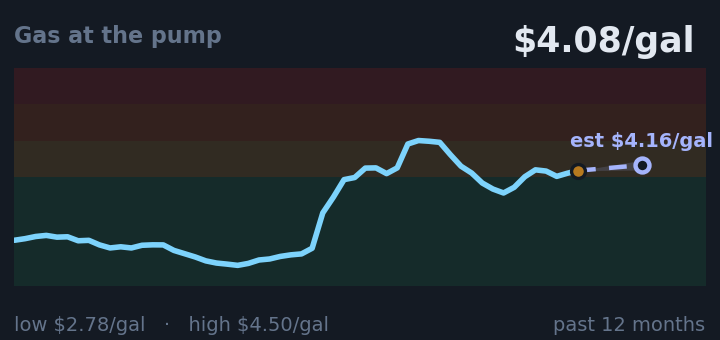
Gas at $4.08 a gallon is elevated and historically correlates with declines in public approval for political leaders.
Connects to: Grüne Seats Mecklenburg-Vorpommern 2026; Victor Ponta Becomes Romania's Next PM; Șerban Matei Becomes Next Romanian PM
Source: FRED
30-year mortgage rate
Caution
6.66%
up from 6.58% a month ago, near its highest in the past year.
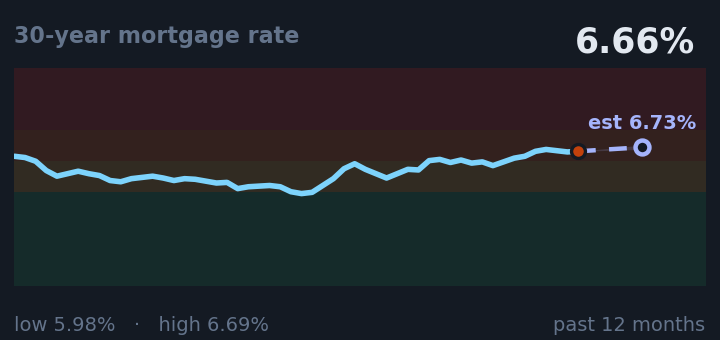
Thirty-year mortgages at 6.65% are expensive and push potential home buyers out of the market, particularly first-time buyers with tight budgets.
Source: FRED
30-year Treasury rate
Warning
5.18%
up from 5.12% a month ago, in the middle of its range for the past year.
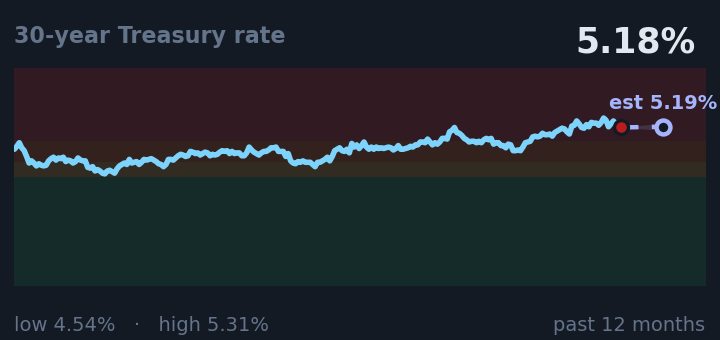
Thirty-year Treasury yields at 5.17% are in the fiscal crisis zone where mortgage rates spike, housing demand freezes, and the cost of government debt climbs.
Connects to: Goldman Sachs Anthropic IPO Underwriter
Source: FRED
10-year Treasury rate
Warning
4.66%
about the same as a month ago, near its highest in the past year.
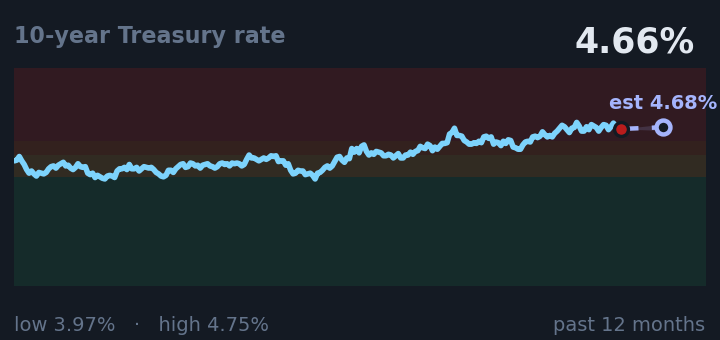
Ten-year Treasury yields at 4.64% put bond markets in a pressure zone where investors can force governments to cut spending or reverse policies that spike long-term borrowing costs.
Connects to: Goldman Sachs Anthropic IPO Underwriter
Source: FRED