Consumer sentiment
Warning
50
up from 45 a month ago, in the middle of its range for the past year.
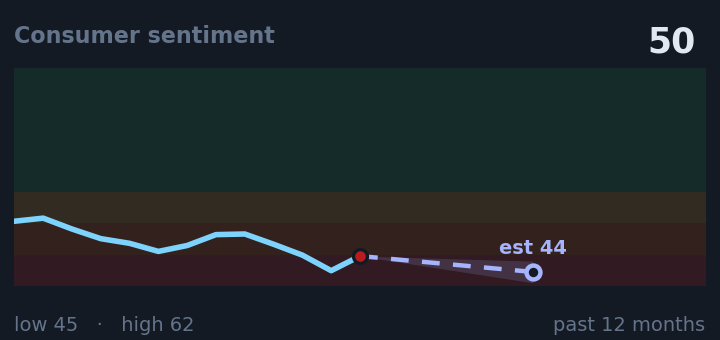
Consumer sentiment stands at 50, having risen from 45 a month ago; at this level, it signals severely depressed household confidence and likely spending contraction.
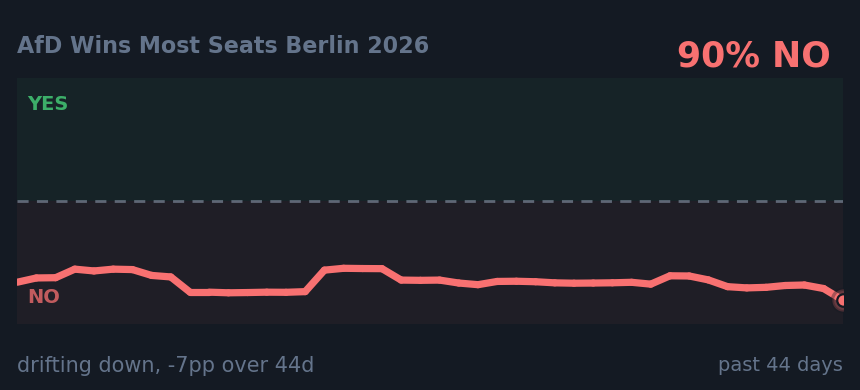
Connects to: AfD Wins Most Seats Berlin 2026; Osnabrück Mayoral Election Winner; Mitch McConnell Senate Exit Probability
Source: FRED
Gas at the pump
Watch
$4.05/gal
up from $3.85/gal a month ago, in the middle of its range for the past year.
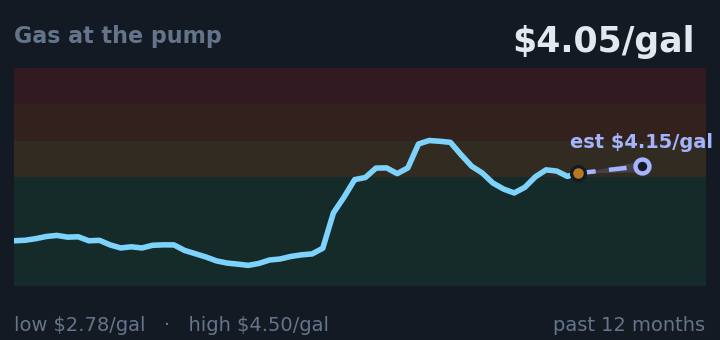
Gas at $4.05 a gallon, elevated after rising from $3.85 a month ago, historically correlates with declines in political approval.
Connects to: AfD Wins Most Seats Berlin 2026; Osnabrück Mayoral Election Winner; Mitch McConnell Senate Exit Probability
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.50%
up from +0.36% a month ago, in the middle of its range for the past year.
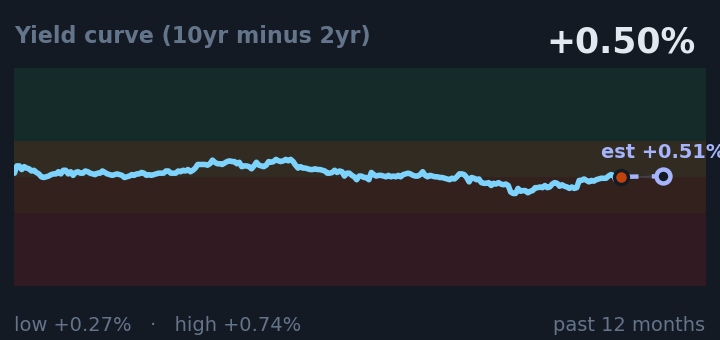
The yield curve has flattened to 0.50% from 0.36% and approaches inversion, a threshold investors monitor closely.
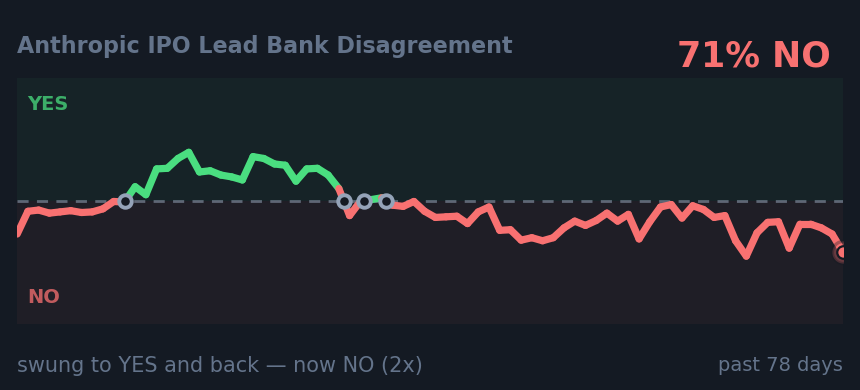
Connects to: Anthropic IPO Lead Bank Disagreement
Source: FRED
Market volatility (VIX)
Normal
16.0
down from 17.1 a month ago, near its lowest in the past year.
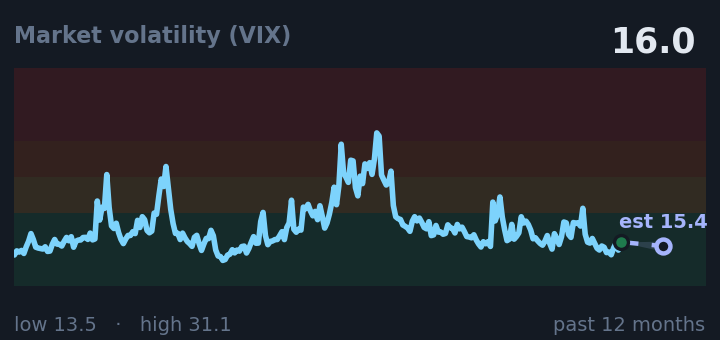
Market volatility at 16.0 sits in the normal range, indicating calm and stable trading conditions.
Connects to: Anthropic IPO Lead Bank Disagreement
Source: FRED
30-year Treasury rate
Warning
5.23%
up from 5.13% a month ago, near its highest in the past year.
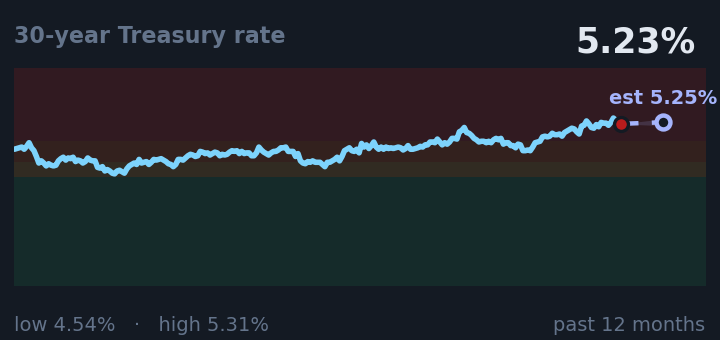
The 30-year Treasury yield at 5.23%, rising from 5.13% a month ago, sits in the fiscal sustainability crisis zone where mortgage rates spike and housing demand freezes.
Connects to: Anthropic IPO Lead Bank Disagreement
Source: FRED
30-year mortgage rate
Caution
6.65%
up from 6.55% a month ago, near its highest in the past year.
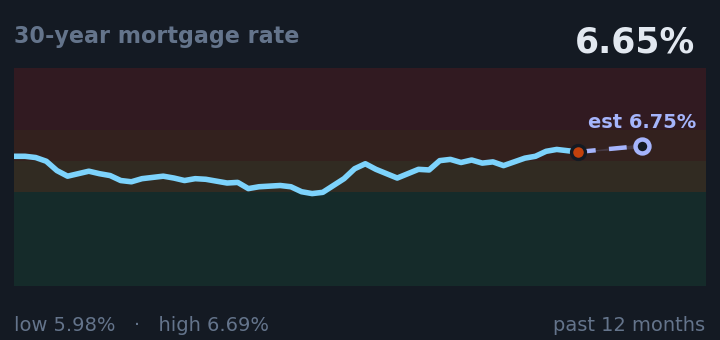
Mortgage rates at 6.65%, up from 6.55% a month ago, remain high and suppress housing demand significantly.
Source: FRED
10-year Treasury rate
Warning
4.69%
up from 4.63% a month ago, near its highest in the past year.
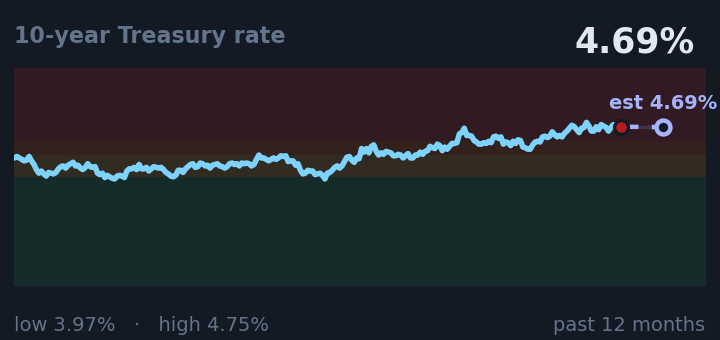
The 10-year Treasury yield at 4.69%, up from 4.63% a month ago, sits in the bond vigilante pressure zone where rising yields have historically forced policy reversals, as seen in April 2025 when a tariff pause followed higher yields.
Connects to: Anthropic IPO Lead Bank Disagreement
Source: FRED
People filing for unemployment
Normal
206k
down from 209k a month ago, in the middle of its range for the past year.
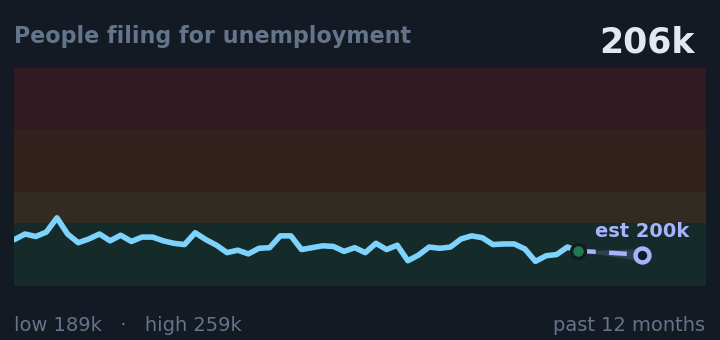
People filing for unemployment is 206k, down from 209k a month ago, and in the middle of its range for the past year.
Source: FRED