Gas at the pump
Watch
$4.01/gal
up from $3.78/gal a month ago, in the middle of its range for the past year.
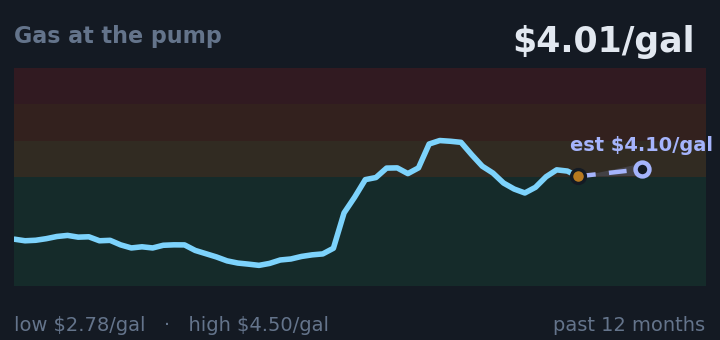
Gas at $4.01 per gallon is what households pay each week for commuting, groceries, and heating; historically, elevated gas prices correlate with declining support for sitting leaders.
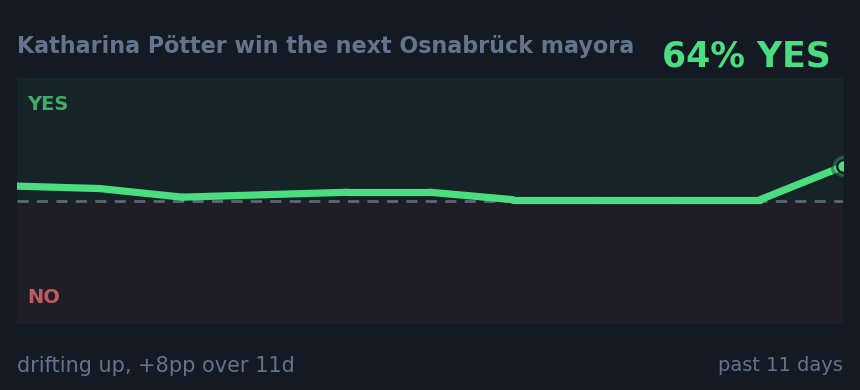
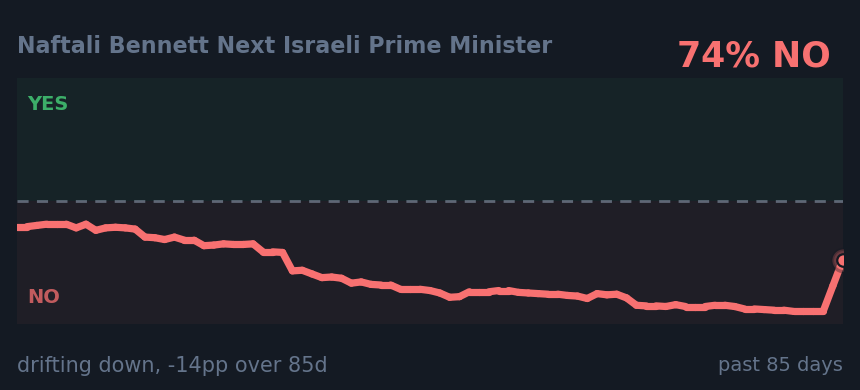
Connects to: Osnabrück Mayoral Election Winner; New Hampshire Senate Margin of Victory; Naftali Bennett Next Israeli Prime Minister
Source: FRED
Consumer sentiment
Warning
50
up from 45 a month ago, in the middle of its range for the past year.
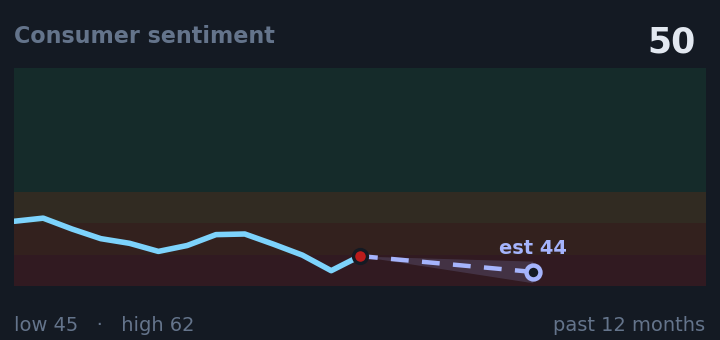
Consumer sentiment at 50 is severely depressed and historically signals that spending will contract as households tighten budgets.
Connects to: Osnabrück Mayoral Election Winner; New Hampshire Senate Margin of Victory; Naftali Bennett Next Israeli Prime Minister
Source: FRED
Market volatility (VIX)
Normal
14.6
down from 16.5 a month ago, near its lowest in the past year.
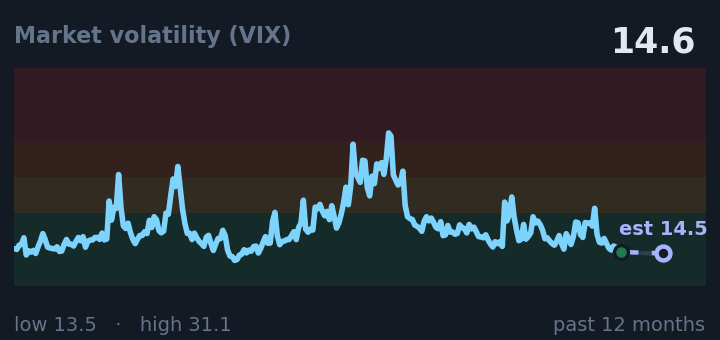
Market volatility at 14.6 is low, reflecting traders' expectation of calm ahead and minimal concern about financial disruption.
Connects to: Anthropic IPO Lead Bank Disagreement
Source: FRED
30-year mortgage rate
Caution
6.67%
up from 6.49% a month ago, near its highest in the past year.
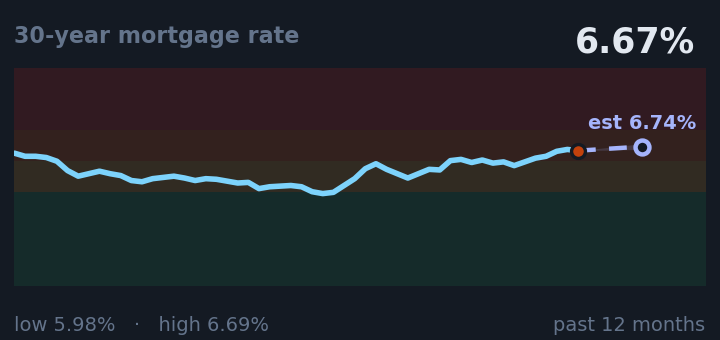
A 30-year mortgage rate of 6.67% sets the monthly payment a household makes on a home loan; at this level, it has significantly reduced housing demand.
Source: FRED
30-year Treasury rate
Warning
5.21%
up from 5.08% a month ago, near its highest in the past year.
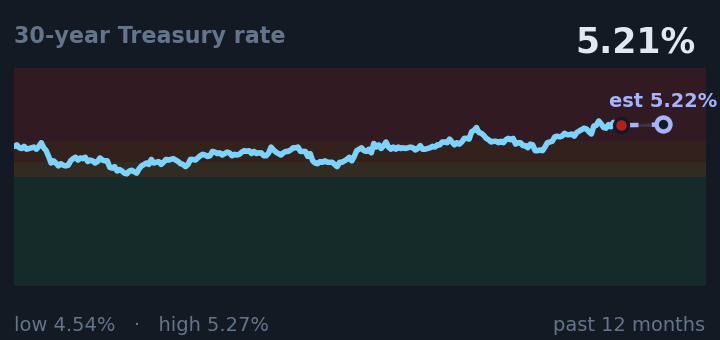
The 30-year Treasury yield at 5.21% reflects concerns about long-term fiscal sustainability; when yields rise this high, mortgage rates and all long-term borrowing costs rise with them.
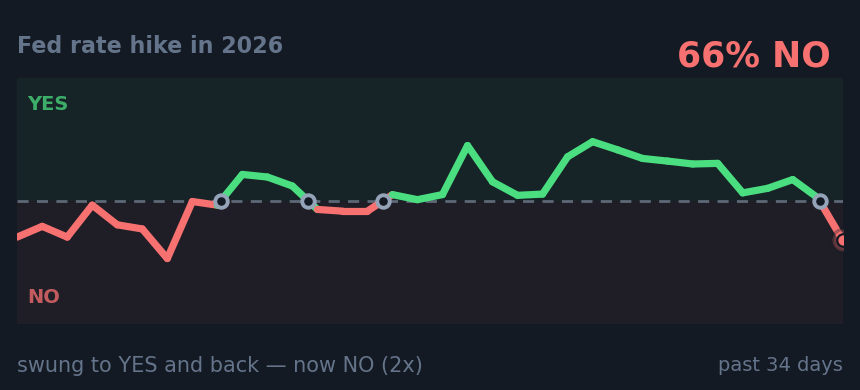
Connects to: Fed Rate Hike in 2026 Agreement; Anthropic IPO Lead Bank Disagreement
Source: FRED
Yield curve (10yr minus 2yr)
Watch
+0.51%
up from +0.42% a month ago, in the middle of its range for the past year.
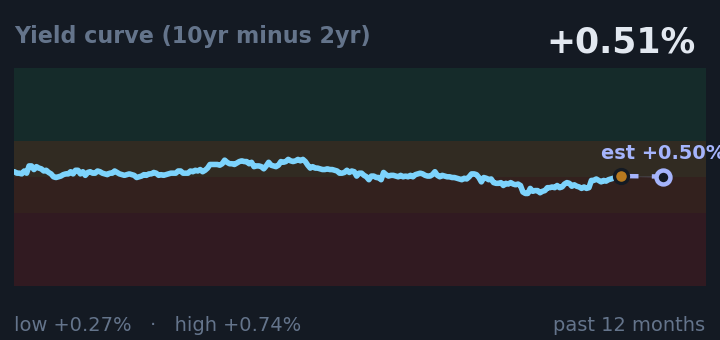
The yield curve spread of +0.51% is in the normal range; historically, when this curve inverts (goes negative), recessions have followed within a year or two.
Connects to: Fed Rate Hike in 2026 Agreement; Anthropic IPO Lead Bank Disagreement
Source: FRED
People filing for unemployment
Normal
209k
down from 217k a month ago, in the middle of its range for the past year.
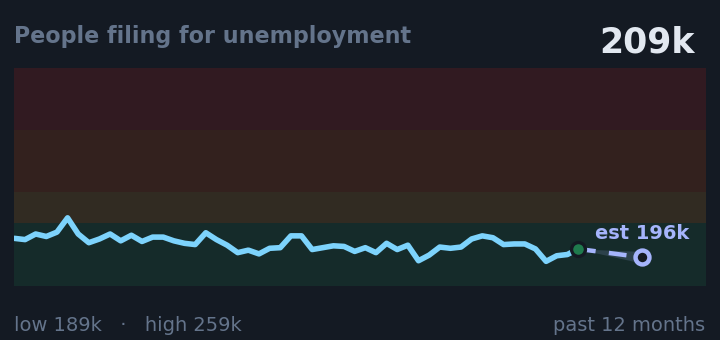
Jobless claims at 209,000 remain in the healthy range; when claims rise sharply, they signal economic stress and job losses ahead.
Source: FRED
10-year Treasury rate
Warning
4.63%
up from 4.58% a month ago, in the middle of its range for the past year.
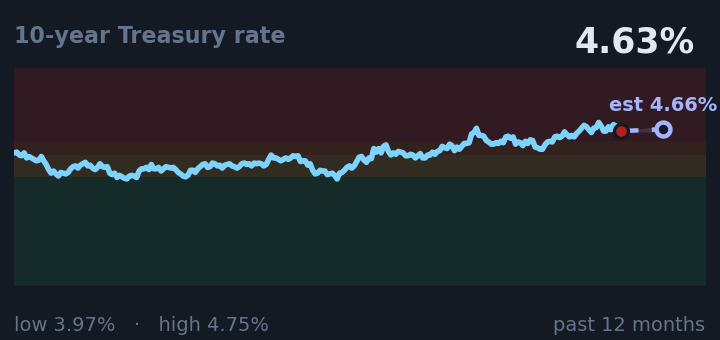
The 10-year Treasury yield at 4.63% sits in a zone where bond markets historically have forced policy reversals (the April 2025 tariff pause occurred at this level).
Connects to: Fed Rate Hike in 2026 Agreement; Anthropic IPO Lead Bank Disagreement
Source: FRED