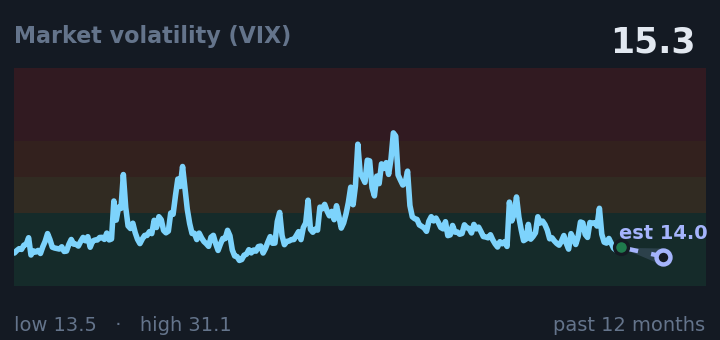
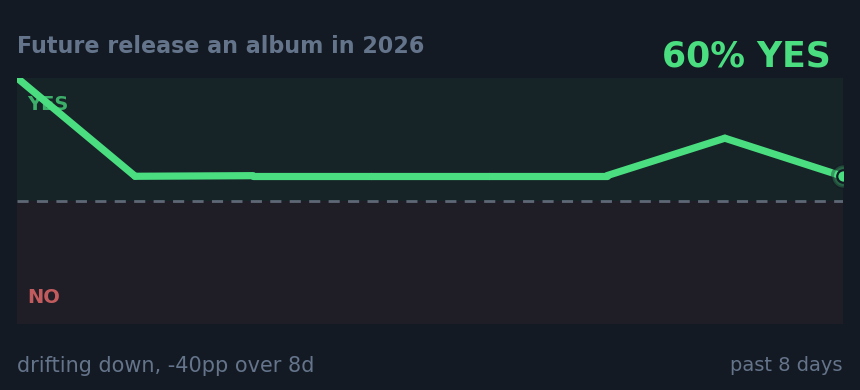
Market volatility at 15.3 is in the normal range, indicating investors are not panicking about the near-term outlook.
Source: FREDOn 2026-08-10 this brief named the North Carolina Senate race at 6% YES; traders moved it to 33%, a shift of 27 points in three days.
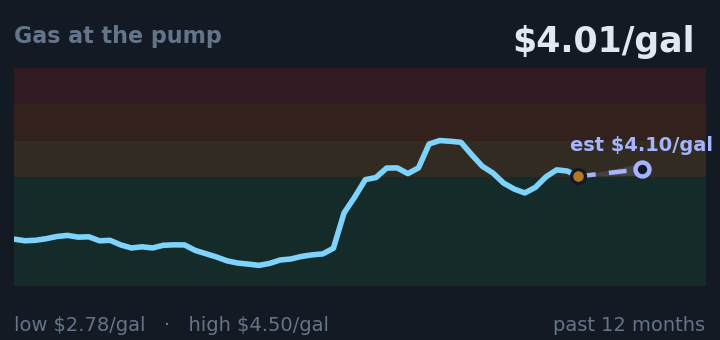
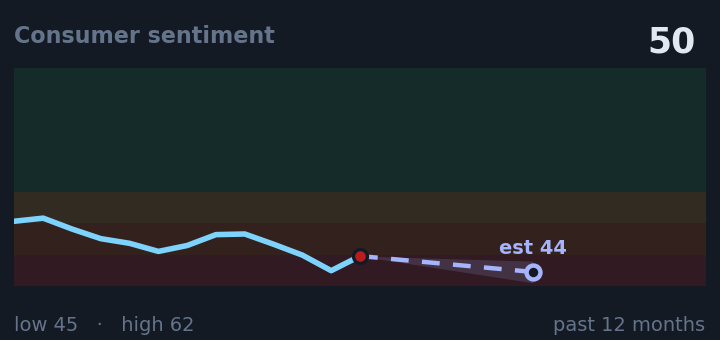
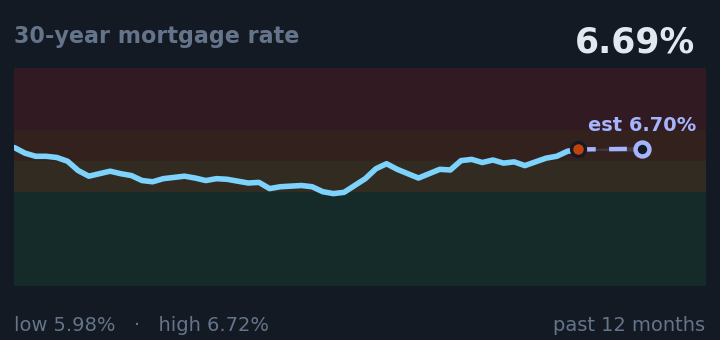
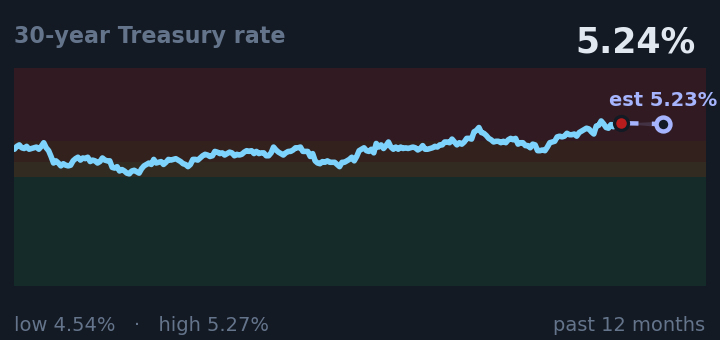
Four of the five biggest movers sit in the Americas: Senate races in North Carolina, Florida, and New Hampshire, plus a question about Federal Reserve rate hikes. With gas at $4.01 per gallon, thirty-year mortgages at 6.69%, and thirty-year Treasury yields at 5.24%, all rising over the past month and the bonds now in the fiscal-crisis zone, the household wallet continues to tighten. The Federal Reserve rate-hike market fell 11 points over the week, pulling traders back from expectations of a move. Consumer sentiment stands at 50, up from 45 a month ago. Market volatility sits at 15.3, within its normal range.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Market volatility at 15.3 is in the normal range, indicating investors are not panicking about the near-term outlook.
Source: FRED
Gas at $4.01 per gallon affects what you pay to fill your car and is an input to food prices through shipping costs.
Consumer sentiment at 50 shows households are severely anxious, a state that historically leads to spending cuts.
A thirty-year mortgage rate of 6.69% determines your monthly payment on a home loan.
Source: FRED
The thirty-year Treasury yield at 5.24% moves closely with mortgage rates; higher yields typically accompany higher monthly payments on home loans.
Source: FRED
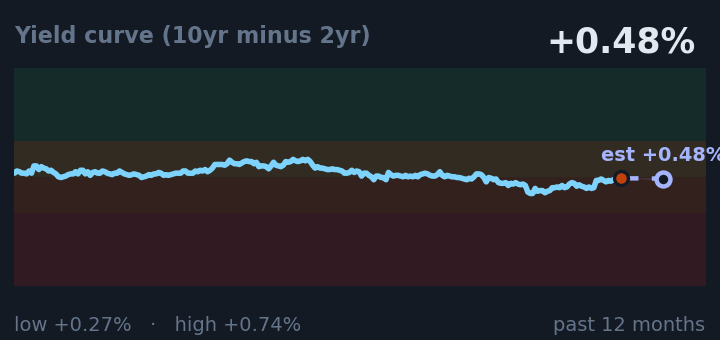
The yield-curve spread at +0.48% is flattening; historically, continued flattening has preceded recessions.
Source: FRED
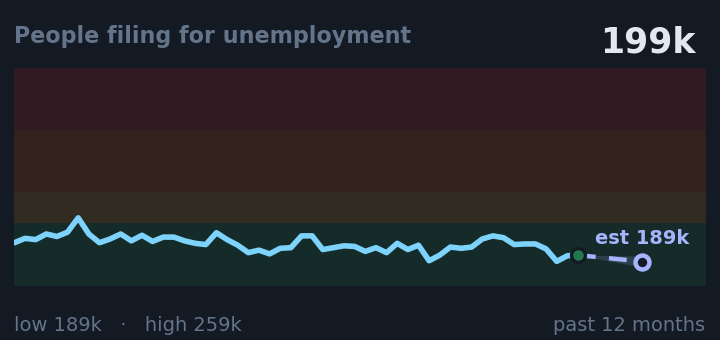
Initial jobless claims at 199k show very few people are filing for unemployment, indicating the job market remains solid.
Source: FRED
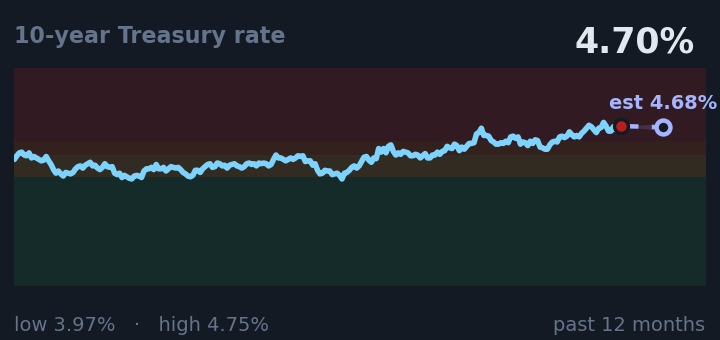
Ten-year Treasury yields at 4.70% affect credit costs across the economy and historically force policy reversals when this high.
Source: FRED
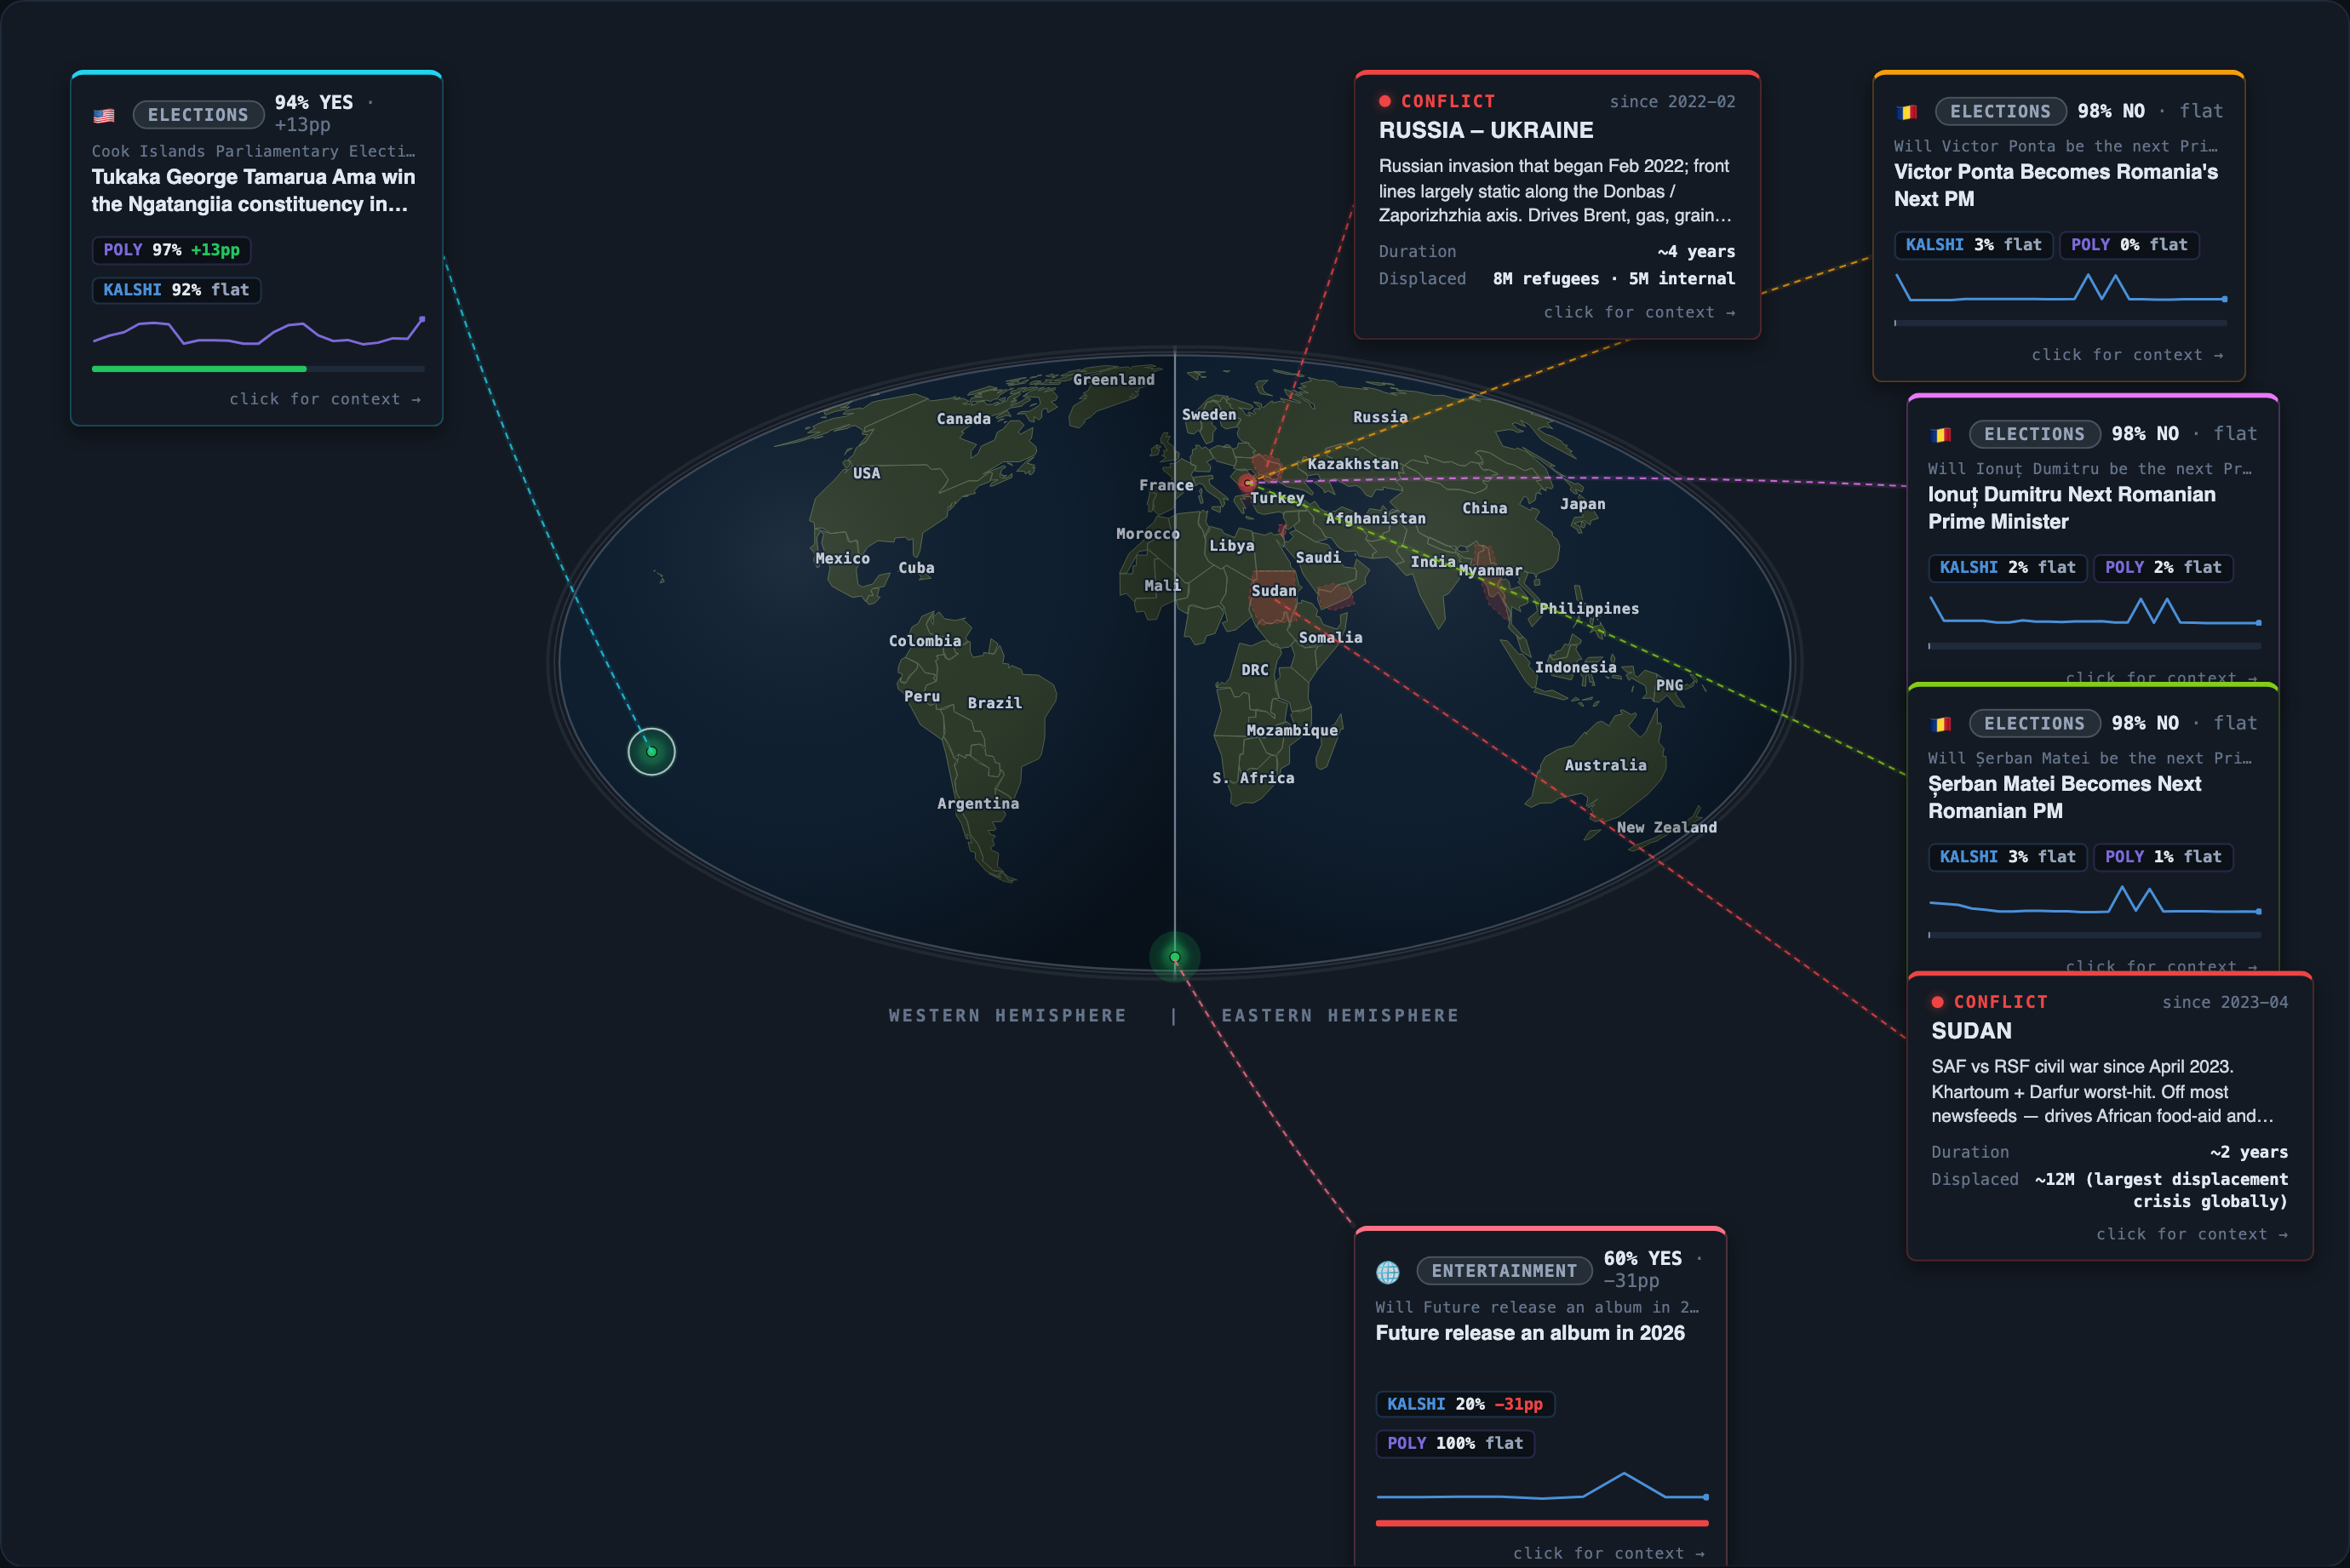
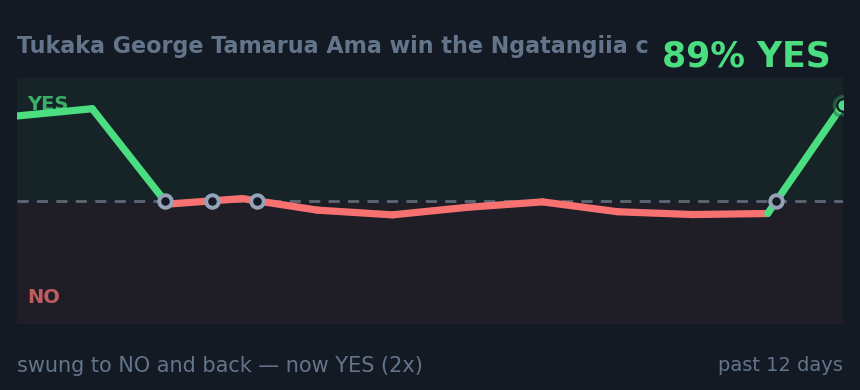
In plain terms: the public’s money is very confident this will happen, and grew more sure overnight.
The platforms agree on an 85% probability of Tukaka George Tamarua Ama winning the Ngatangiia constituency, indicating a high level of confidence in this outcome with no significant disagreement between them.
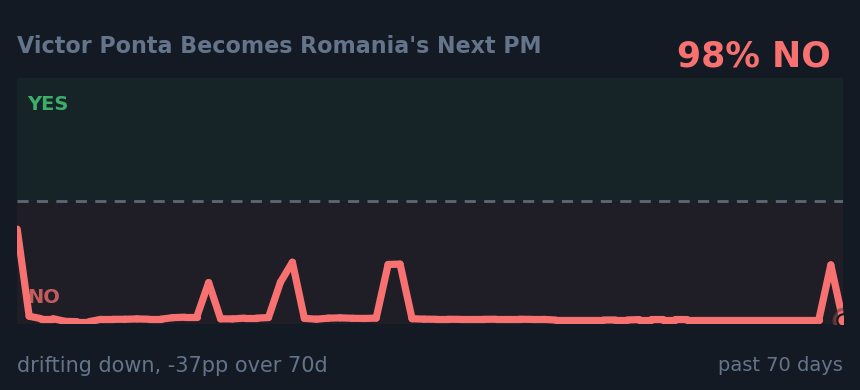
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Extreme 46-point spread (2% vs 48%) suggests fundamental disagreement on Ponta's viability as successor PM. Polymarket's deep underpricing versus Kalshi implies either hidden political intelligence favoring Ponta or market illiquidity driving the divergence—critical for identifyi
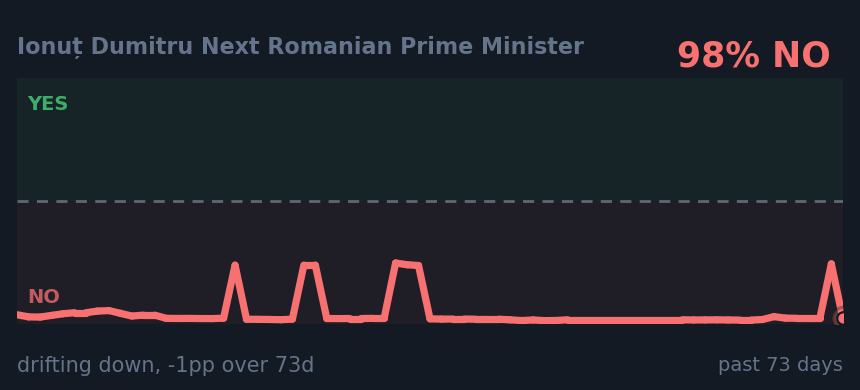
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Matched event shows tight 2-point spread (2% Polymarket vs 4% Kalshi) for a low-probability outcome. Agreement near 3% suggests minimal market conviction; depressed consumer sentiment (57) and elevated gas prices may constrain any anti-incumbent sentiment that could elevate an al
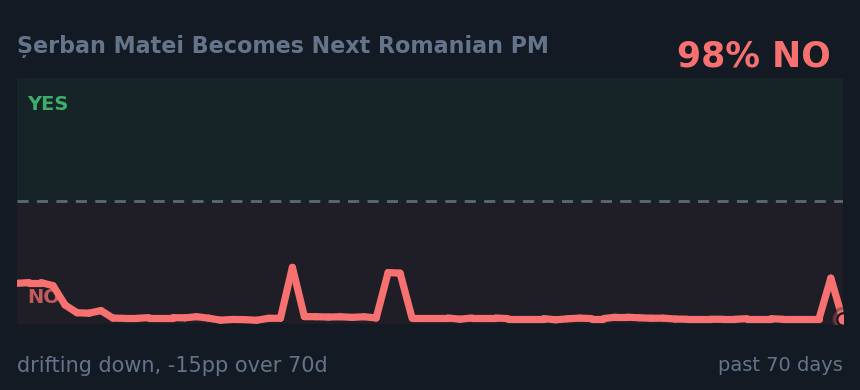
In plain terms: the public’s money is very confident this will not happen, and held steady overnight.
Tight 2-point spread (16-18%) across major platforms reflects genuine uncertainty about Matei's PM prospects. Depressed consumer sentiment (57) and elevated gas prices suggest challenging economic conditions that typically favor opposition challengers over incumbents.
In plain terms: the public’s money is close to a coin flip on whether this will happen, and grew less sure overnight.
Both platforms agree with an average probability of 100%, indicating no disagreement or uncertainty about Future releasing an album in 2026, as reflected by the 0 percentage points spread and Polymarket's price at 100%.
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 0 rose 0 fell 0 flat |
| EUROPE | 0 rose 0 fell 3 flat |
| ASIA | 1 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| AFRICA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |