Gas at the pump
Watch
$4.01/gal
up from $3.78/gal a month ago, in the middle of its range for the past year.
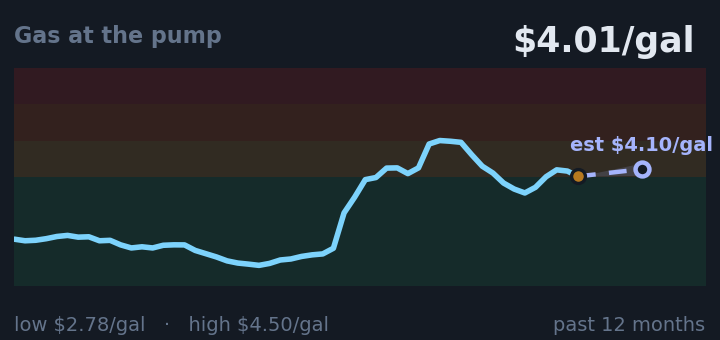
Gas at $4.01 per gallon directly sets what households pay for transportation and heating; prices this high historically drive spending cuts.
Connects to: North Carolina Senate Closest Race in 2026; Russell Fry South Carolina Senate Special Primary Round 1; New Hampshire Senate Margin of Victory
Source: FRED
30-year mortgage rate
Caution
6.69%
up from 6.43% a month ago, near its highest in the past year.
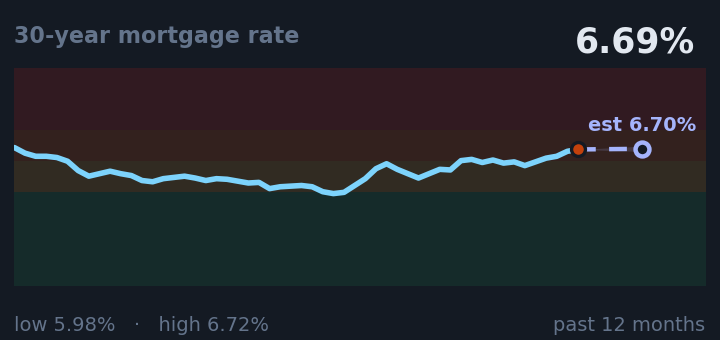
The 30-year mortgage rate of 6.69% determines monthly payments on home purchases; this level suppresses buying demand and locks existing borrowers into high costs.
Source: FRED
Consumer sentiment
Warning
50
up from 45 a month ago, in the middle of its range for the past year.
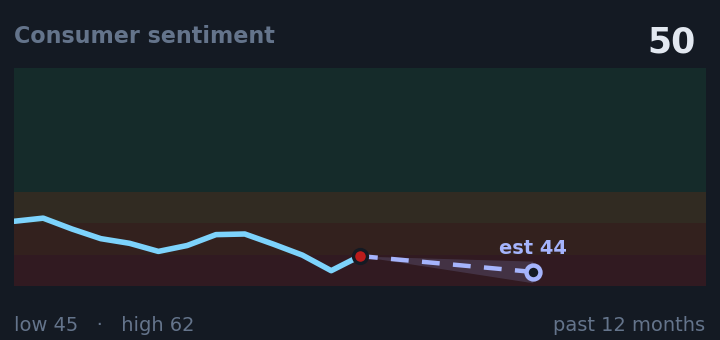
Consumer sentiment at 50 signals severe household anxiety; people are working but too cautious to spend freely.
Connects to: North Carolina Senate Closest Race in 2026; Russell Fry South Carolina Senate Special Primary Round 1; New Hampshire Senate Margin of Victory
Source: FRED
30-year Treasury rate
Warning
5.25%
up from 5.06% a month ago, near its highest in the past year.
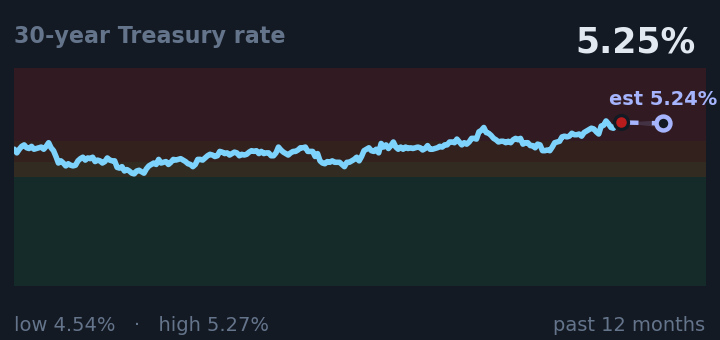
The 30-year Treasury yield of 5.25% marks the fiscal-crisis zone where government refinancing costs spike; policy reversals have historically followed at this level.
Connects to: Freddie Mac IPO Before 2027
Source: FRED
10-year Treasury rate
Warning
4.72%
up from 4.56% a month ago, near its highest in the past year.
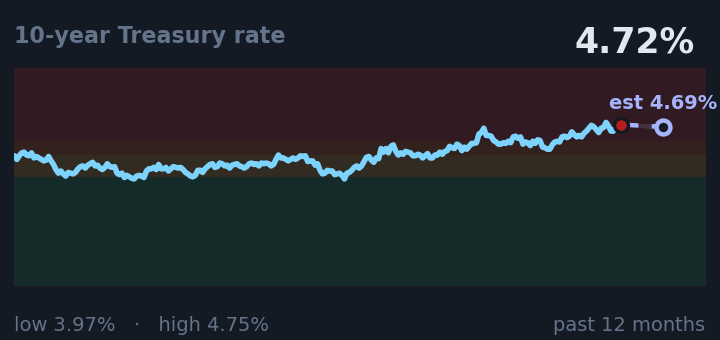
The 10-year Treasury yield of 4.72% sits in the bond-vigilante pressure zone; rates above 4.5% have forced tariff pauses in recent history.
Connects to: Freddie Mac IPO Before 2027
Source: FRED
People filing for unemployment
Normal
199k
down from 217k a month ago, near its lowest in the past year.
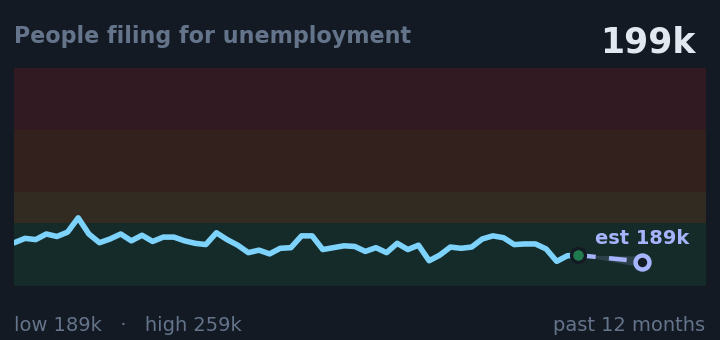
Unemployment filings at 199,000 sit near their lowest in a year, signaling strong hiring activity even as household confidence lags.
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.48%
up from +0.35% a month ago, in the middle of its range for the past year.
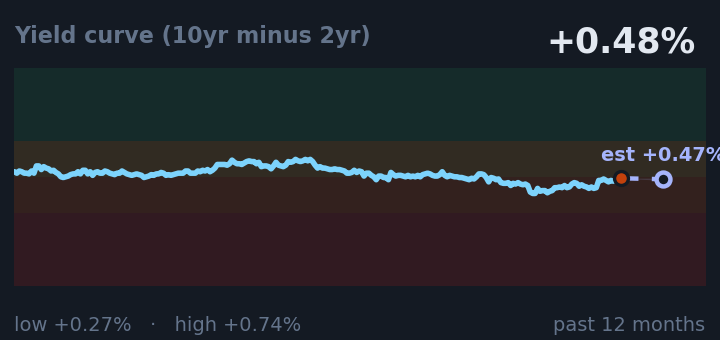
The yield curve spread of 0.48% continues flattening, a warning sign that precedes recessions; watch for it to turn negative.
Connects to: Freddie Mac IPO Before 2027
Source: FRED
Market volatility (VIX)
Normal
15.3
up from 15.0 a month ago, near its lowest in the past year.
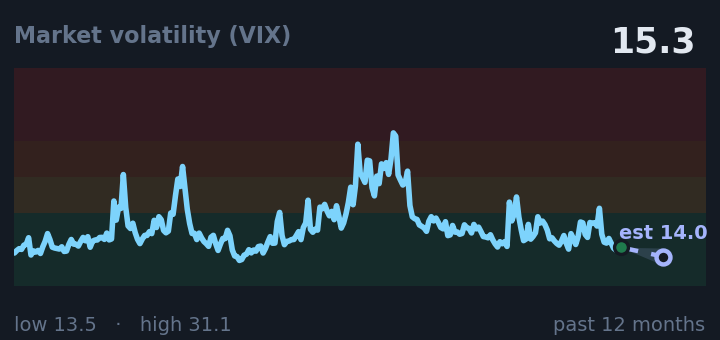
Market volatility at 15.5 remains in the normal range, suggesting traders see no immediate crisis despite a month of rising rates and fuel costs.
Connects to: Freddie Mac IPO Before 2027
Source: FRED