Gas at the pump
Normal
$3.78/gal
down from $4.30/gal a month ago, in the middle of its range for the past year.
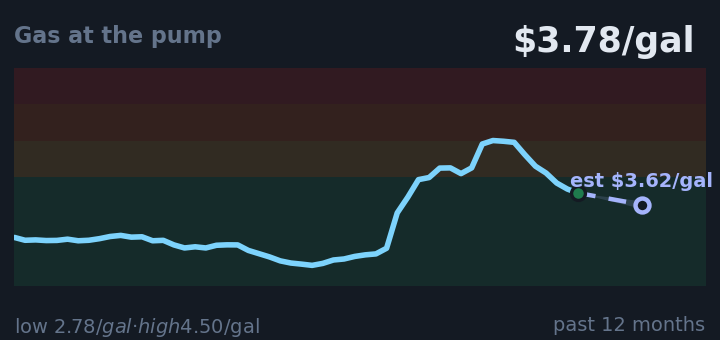
At $3.78, gas has eased but remains elevated; above $4.00, it historically crushes low-income budgets and constrains household spending.
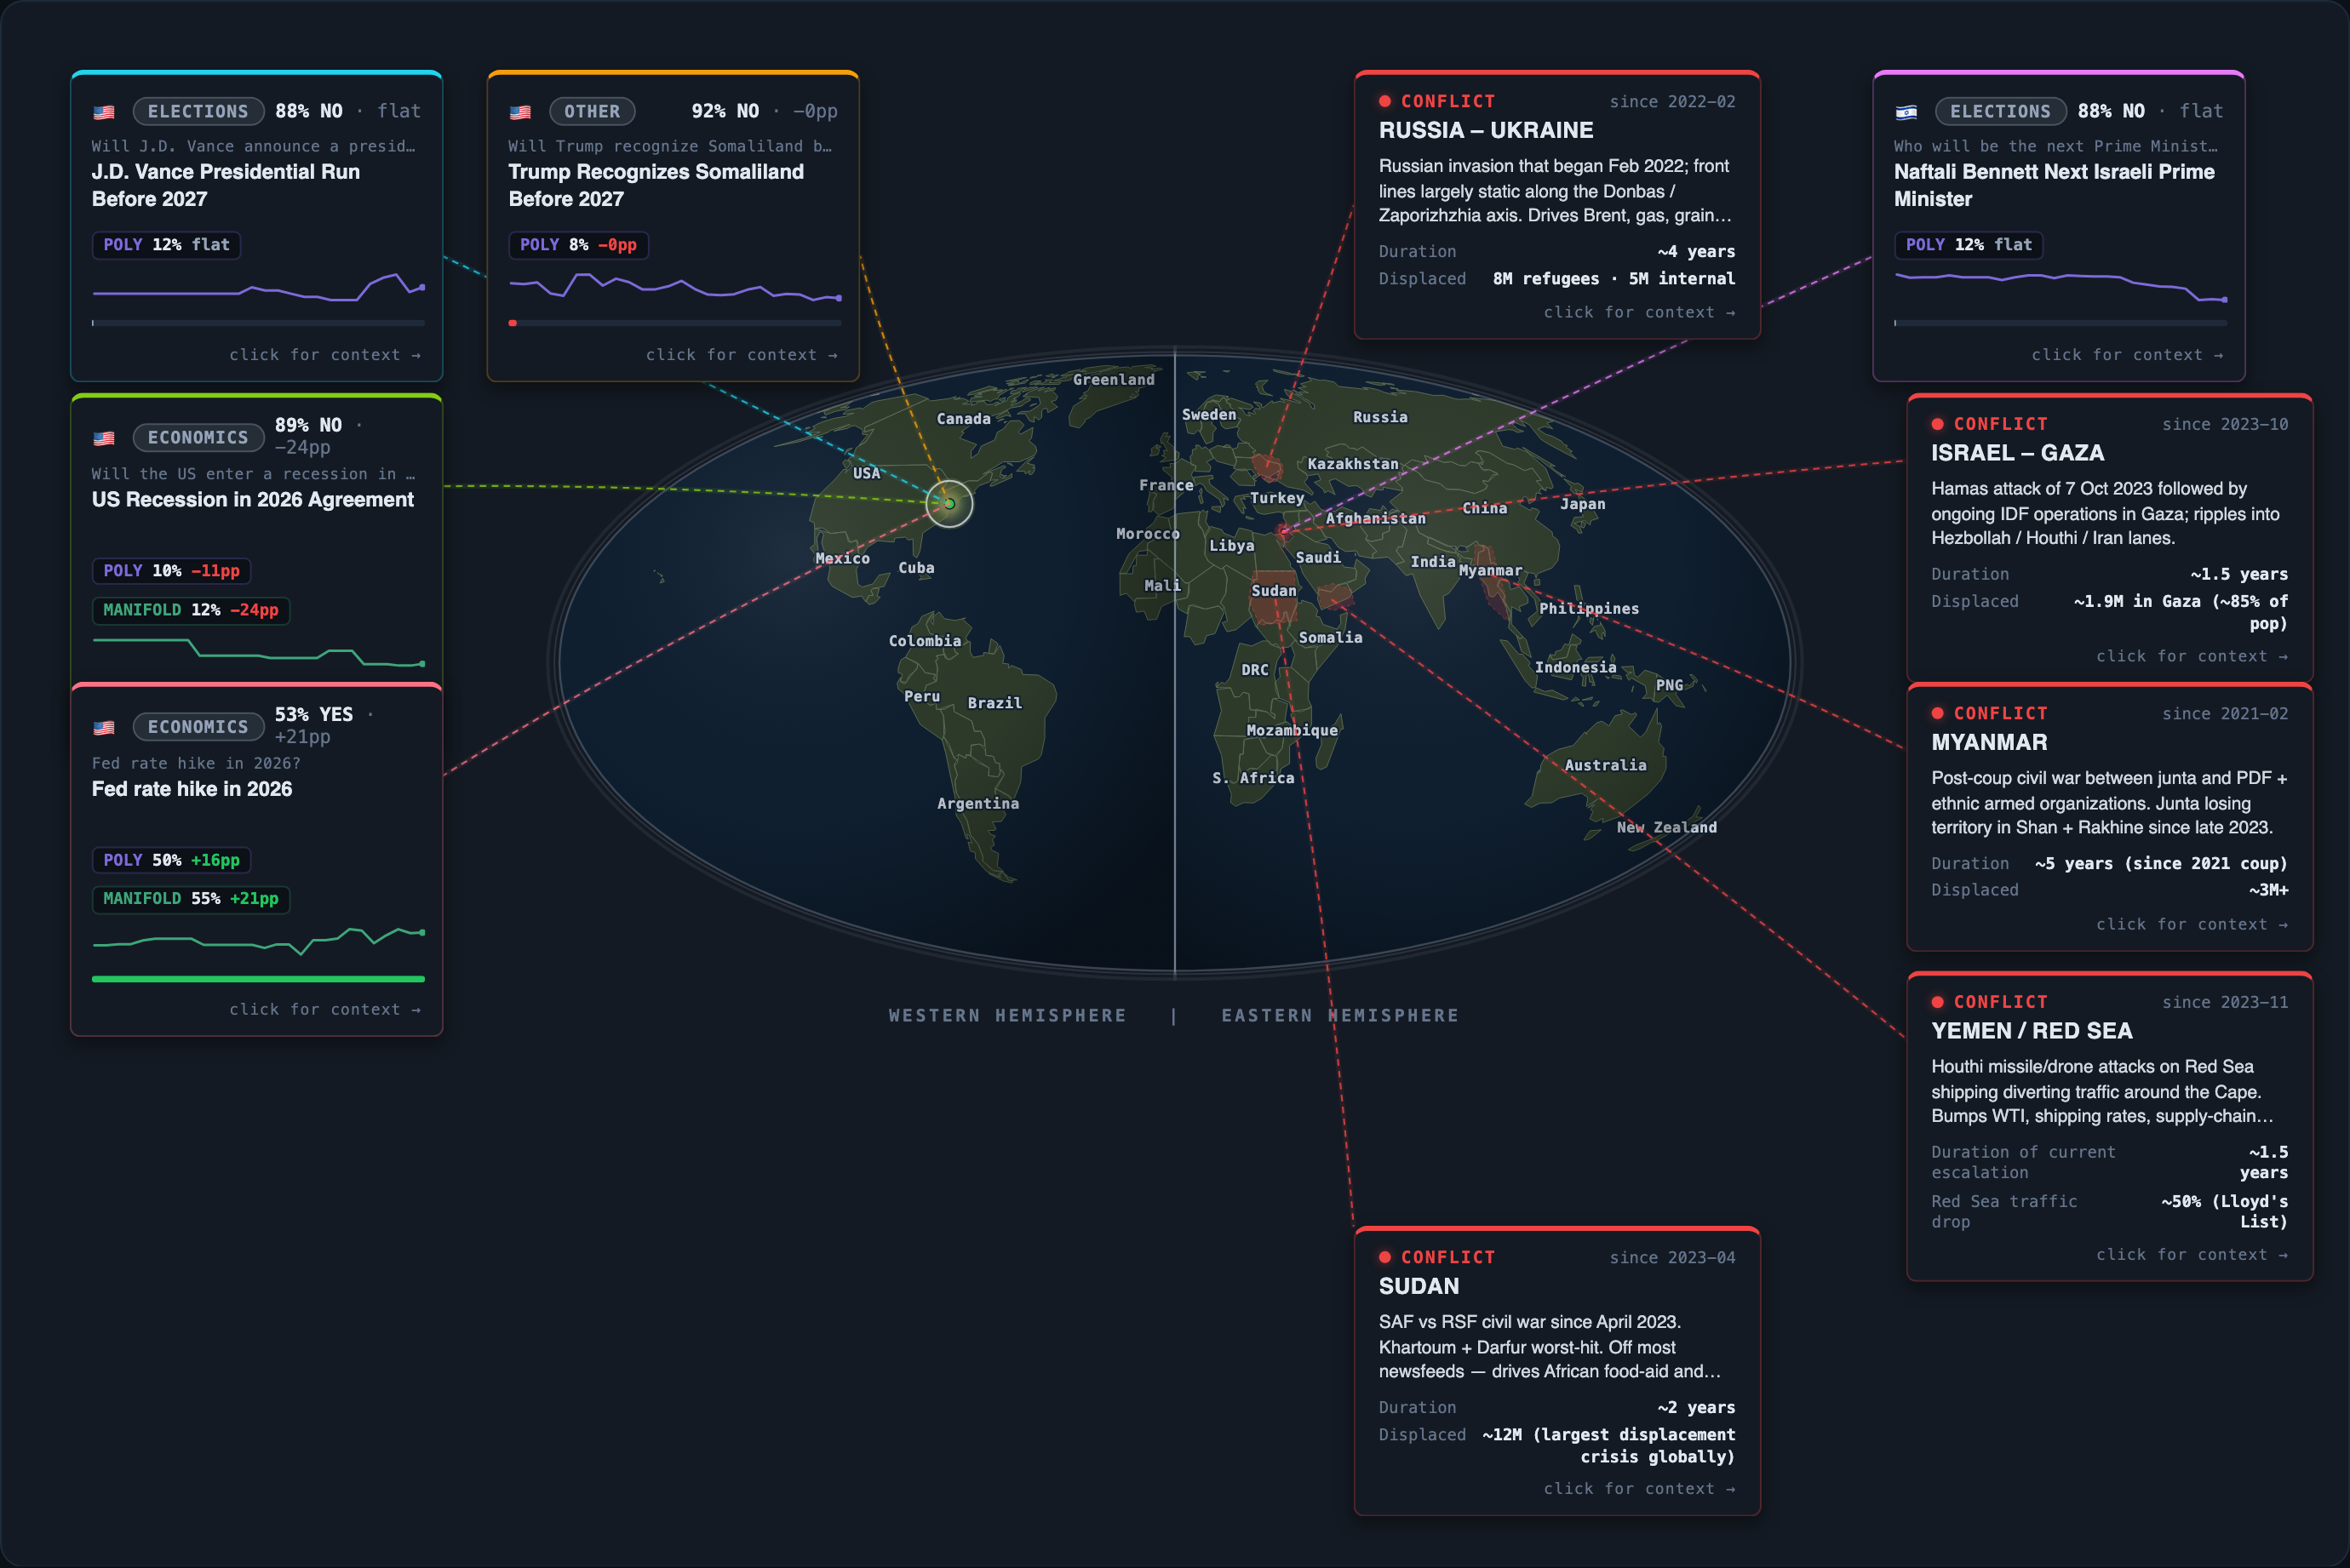
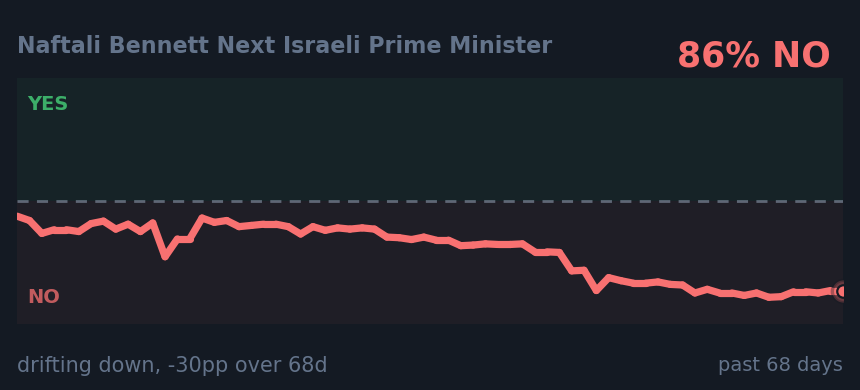
Connects to: J.D. Vance Presidential Run Before 2027; Naftali Bennett Next Israeli Prime Minister
Source: FRED
Consumer sentiment
Warning
45
down from 50 a month ago, near its lowest in the past year.
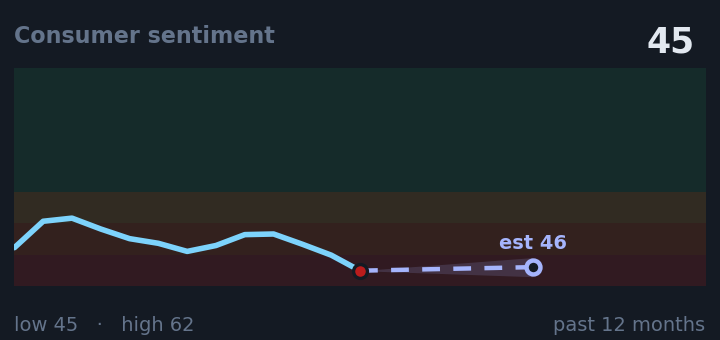
At 45, consumer sentiment is at recession-warning levels; families are genuinely scared and pulling back on spending and major purchases.
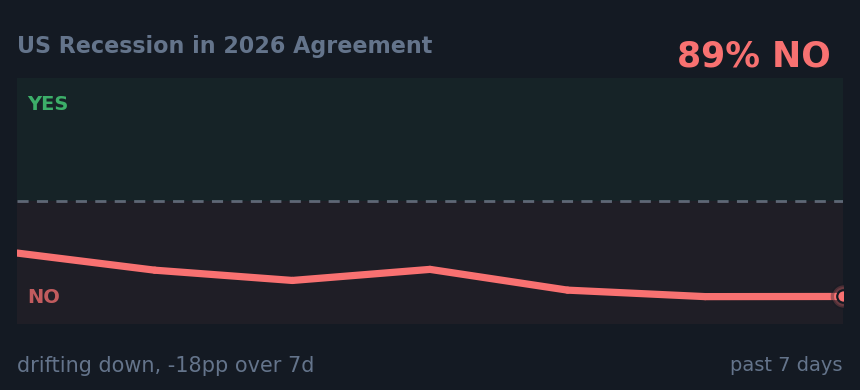
Connects to: J.D. Vance Presidential Run Before 2027; Naftali Bennett Next Israeli Prime Minister; US Recession in 2026 Agreement
Source: FRED
Market volatility (VIX)
Normal
16.9
down from 18.9 a month ago, in the middle of its range for the past year.
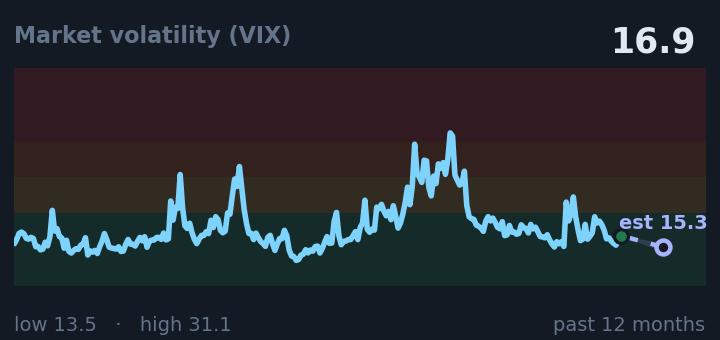
At 16.1, traders are calm and don't expect market shocks, creating a dangerous blind spot to household anxiety and economic weakness unfolding below.
Source: FRED
30-year Treasury rate
Warning
5.06%
about the same as a month ago, in the middle of its range for the past year.
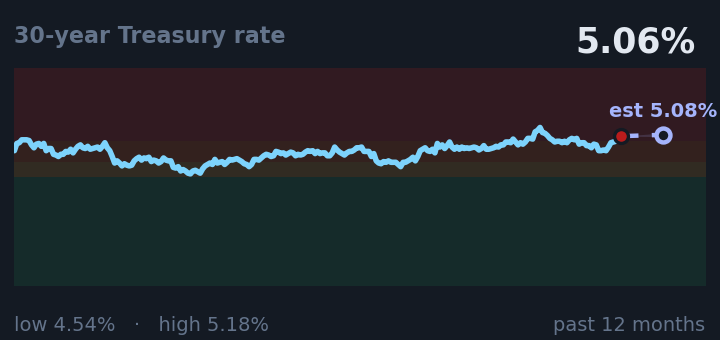
At 5.05%, the 30-year rate signals bond investors expect crisis-level government borrowing costs, constraining long-term growth and policy capacity.
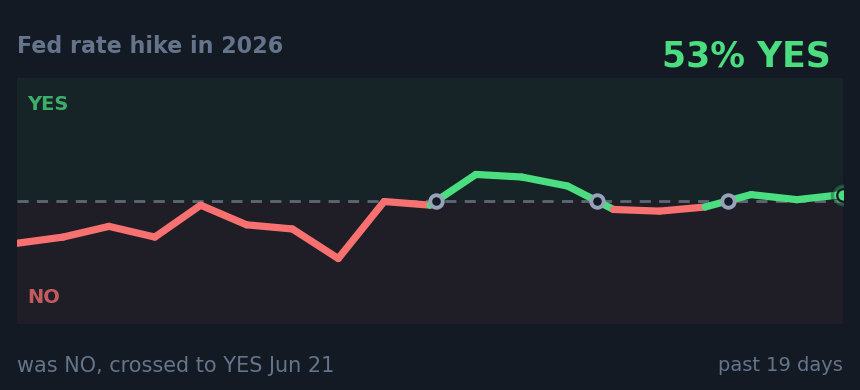
Connects to: US Recession in 2026 Agreement; Fed Rate Hike in 2026 Agreement
Source: FRED
Yield curve (10yr minus 2yr)
Caution
+0.38%
down from +0.40% a month ago, in the middle of its range for the past year.
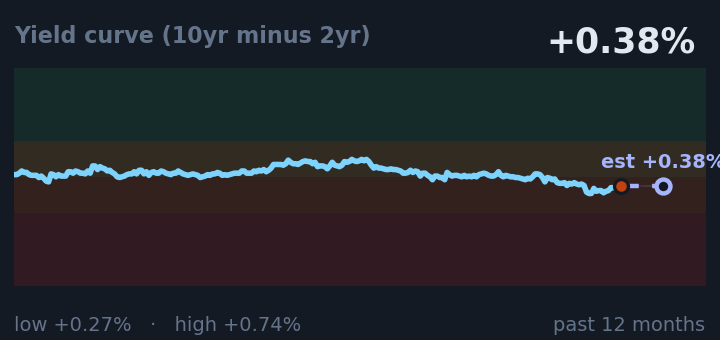
At 0.35% and flattening, the yield curve is moving toward inversion, a recession signal that has preceded every US slowdown in the past 40 years.
Connects to: Fed Rate Hike in 2026 Agreement
Source: FRED
30-year mortgage rate
Watch
6.49%
about the same as a month ago, in the middle of its range for the past year.
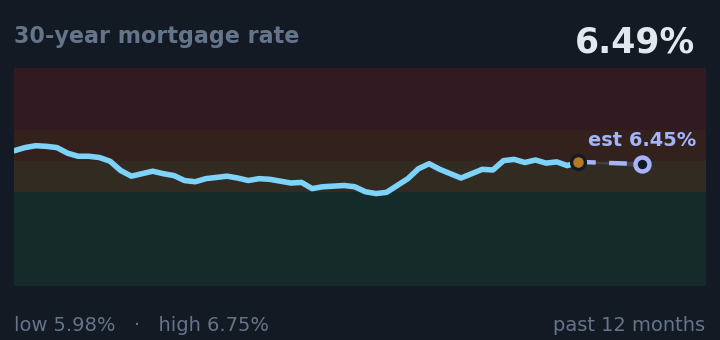
At 6.43%, mortgage rates keep home buying unaffordable and freeze the housing market, typically preceding broader economic slowdown.
Source: FRED
10-year Treasury rate
Warning
4.56%
about the same as a month ago, in the middle of its range for the past year.
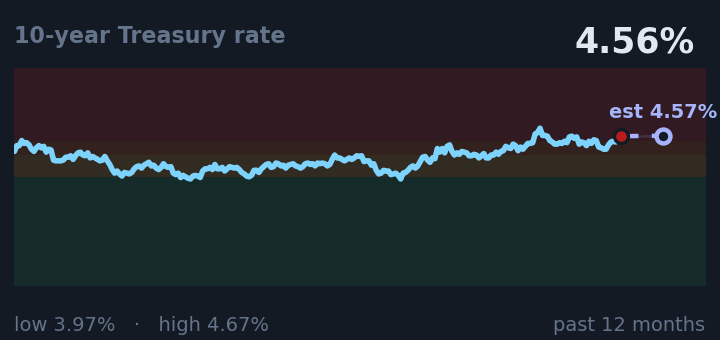
At 4.55%, the 10-year rate is at the level where government borrowing costs typically force policy reversals and constrain aggressive spending.
Connects to: US Recession in 2026 Agreement; Fed Rate Hike in 2026 Agreement
Source: FRED