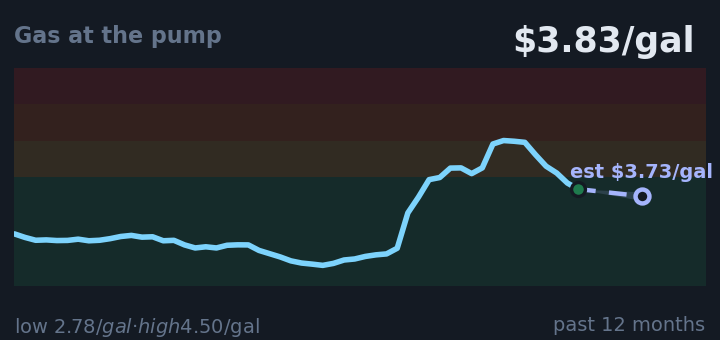
Gas prices at the pump affect household spending every week and the cost of goods shipped to stores.
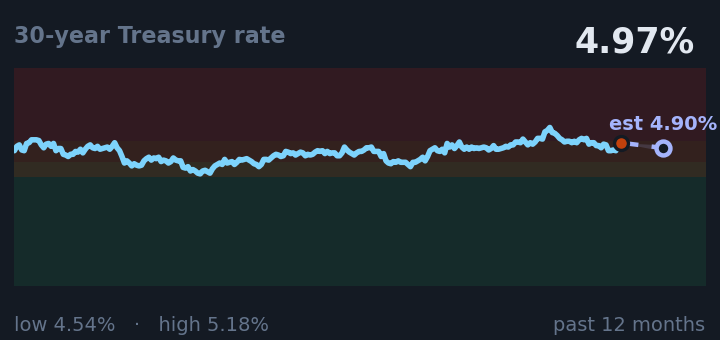
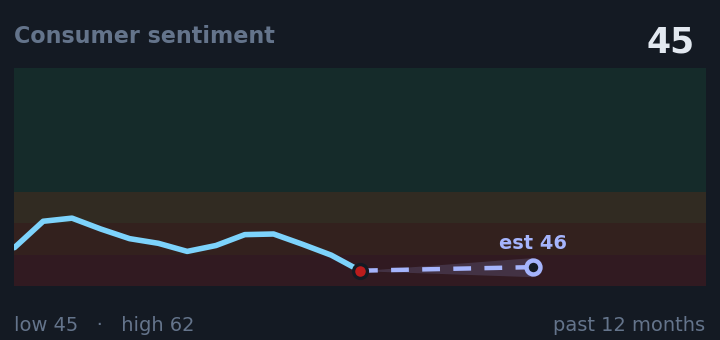
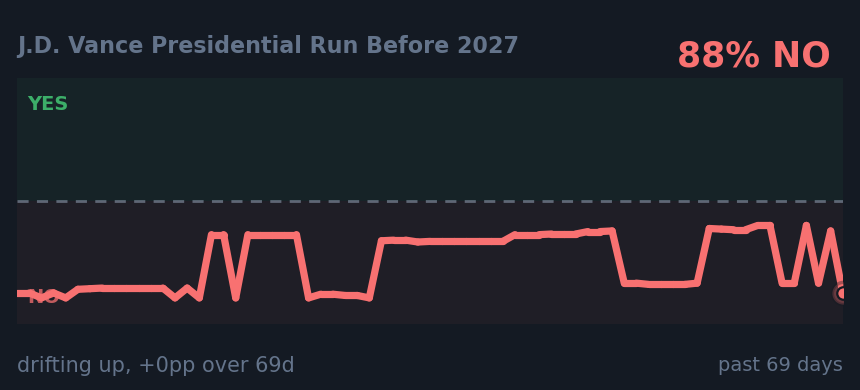
The economy is showing two warning signs that are making households and investors anxious. Consumer confidence has fallen to 45, its weakest level in months, which historically means families are pulling back on spending and saving instead. Meanwhile, gas prices are down from last month but still elevated at $3.83 per gallon, stretching household budgets further. On the borrowing side, Treasury yields are climbing toward levels that constrain government policy: the 30-year rate is at 4.97 percent, just below the 5 percent threshold where history shows fiscal strain typically forces spending cuts. Markets are reflecting this caution, with traders cutting back on bets that the current administration will make aggressive moves (J.D. Vance run odds fell 2pp overnight), while also accounting for geopolitical risks where disagreements between trading platforms suggest real uncertainty (Strait of Hormuz disruption odds rose 41pp as traders price in supply chain risk).
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Gas prices at the pump affect household spending every week and the cost of goods shipped to stores.
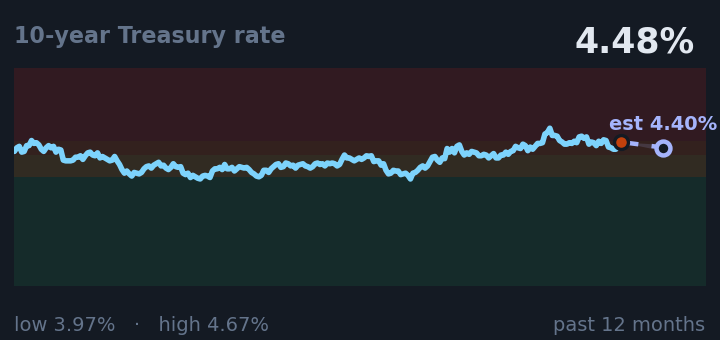
The 10-year rate is the interest cost that banks use to price mortgages and business loans.
Source: FRED
The 30-year rate affects the cost of long-term borrowing for home mortgages and government fiscal policy decisions.
Source: FRED
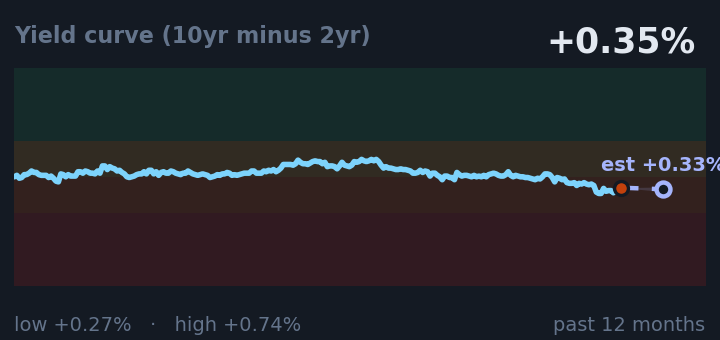
When this spread flattens, it historically signals that investors expect the economy to weaken in the year ahead.
Source: FRED
At 45, this reading means households are severely worried about jobs and finances, so they cut spending and the economy weakens.
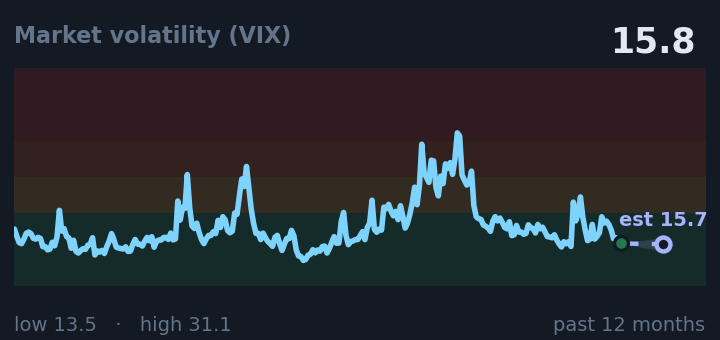
A reading of 16.6 means investors expect calm trading ahead rather than sudden market swings.
Source: FRED
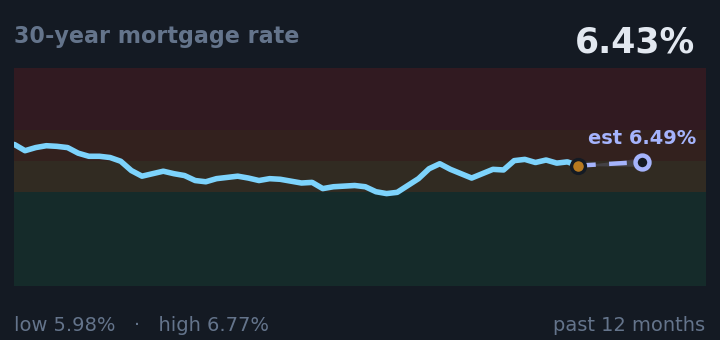
At 6.43 percent, this rate directly affects the monthly payment a family needs to afford a home.
Source: FRED
In plain terms: the public’s money is very confident this will not happen, and grew a little less sure overnight.
Market consensus at 10% reflects skepticism of a near-term announcement given Vance's current VP role and weak economic conditions (gas $4.12, consumer sentiment 57) that typically disfavor incumbent administration moves. Agreement across platforms suggests genuine uncertainty ra
In plain terms: the public’s money is very confident this will not happen, and grew much more sure overnight.
Polymarket and Manifold both price the event at 40%, indicating a neutral consensus with no clear bias towards or against Strait of Hormuz traffic returning to normal by the end of July.
In plain terms: the public’s money is very confident this will not happen, and grew more sure overnight.
Massive 48-point spread between Kalshi (63%) and Polymarket (15%) on U.S. recognition of breakaway Somaliland. Disagreement likely reflects different interpretations of Trump's foreign policy priorities, geopolitical constraints with Somalia, and whether recognition occurs via ex
In plain terms: the public’s money is very confident this will not happen, and grew much more sure overnight.
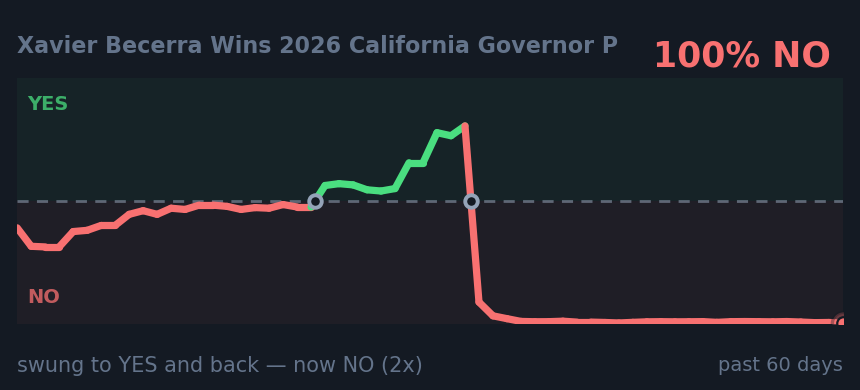
Markets are unified at 47-48% on Becerra's primary victory chances, suggesting genuine uncertainty rather than mispricing. Headwinds from depressed consumer sentiment and elevated gas prices create headwinds for the incumbent-aligned candidate, explaining the below-even probabili
In plain terms: the public’s money is close to a coin flip on whether this will not happen, and grew much less sure overnight.
Markets unified at 12% for former IDF chief Eizenkot to become PM next, suggesting low consensus probability despite his political profile. Tight spread indicates confidence in valuation, though depressed consumer sentiment and elevated energy costs create macro headwinds for inc
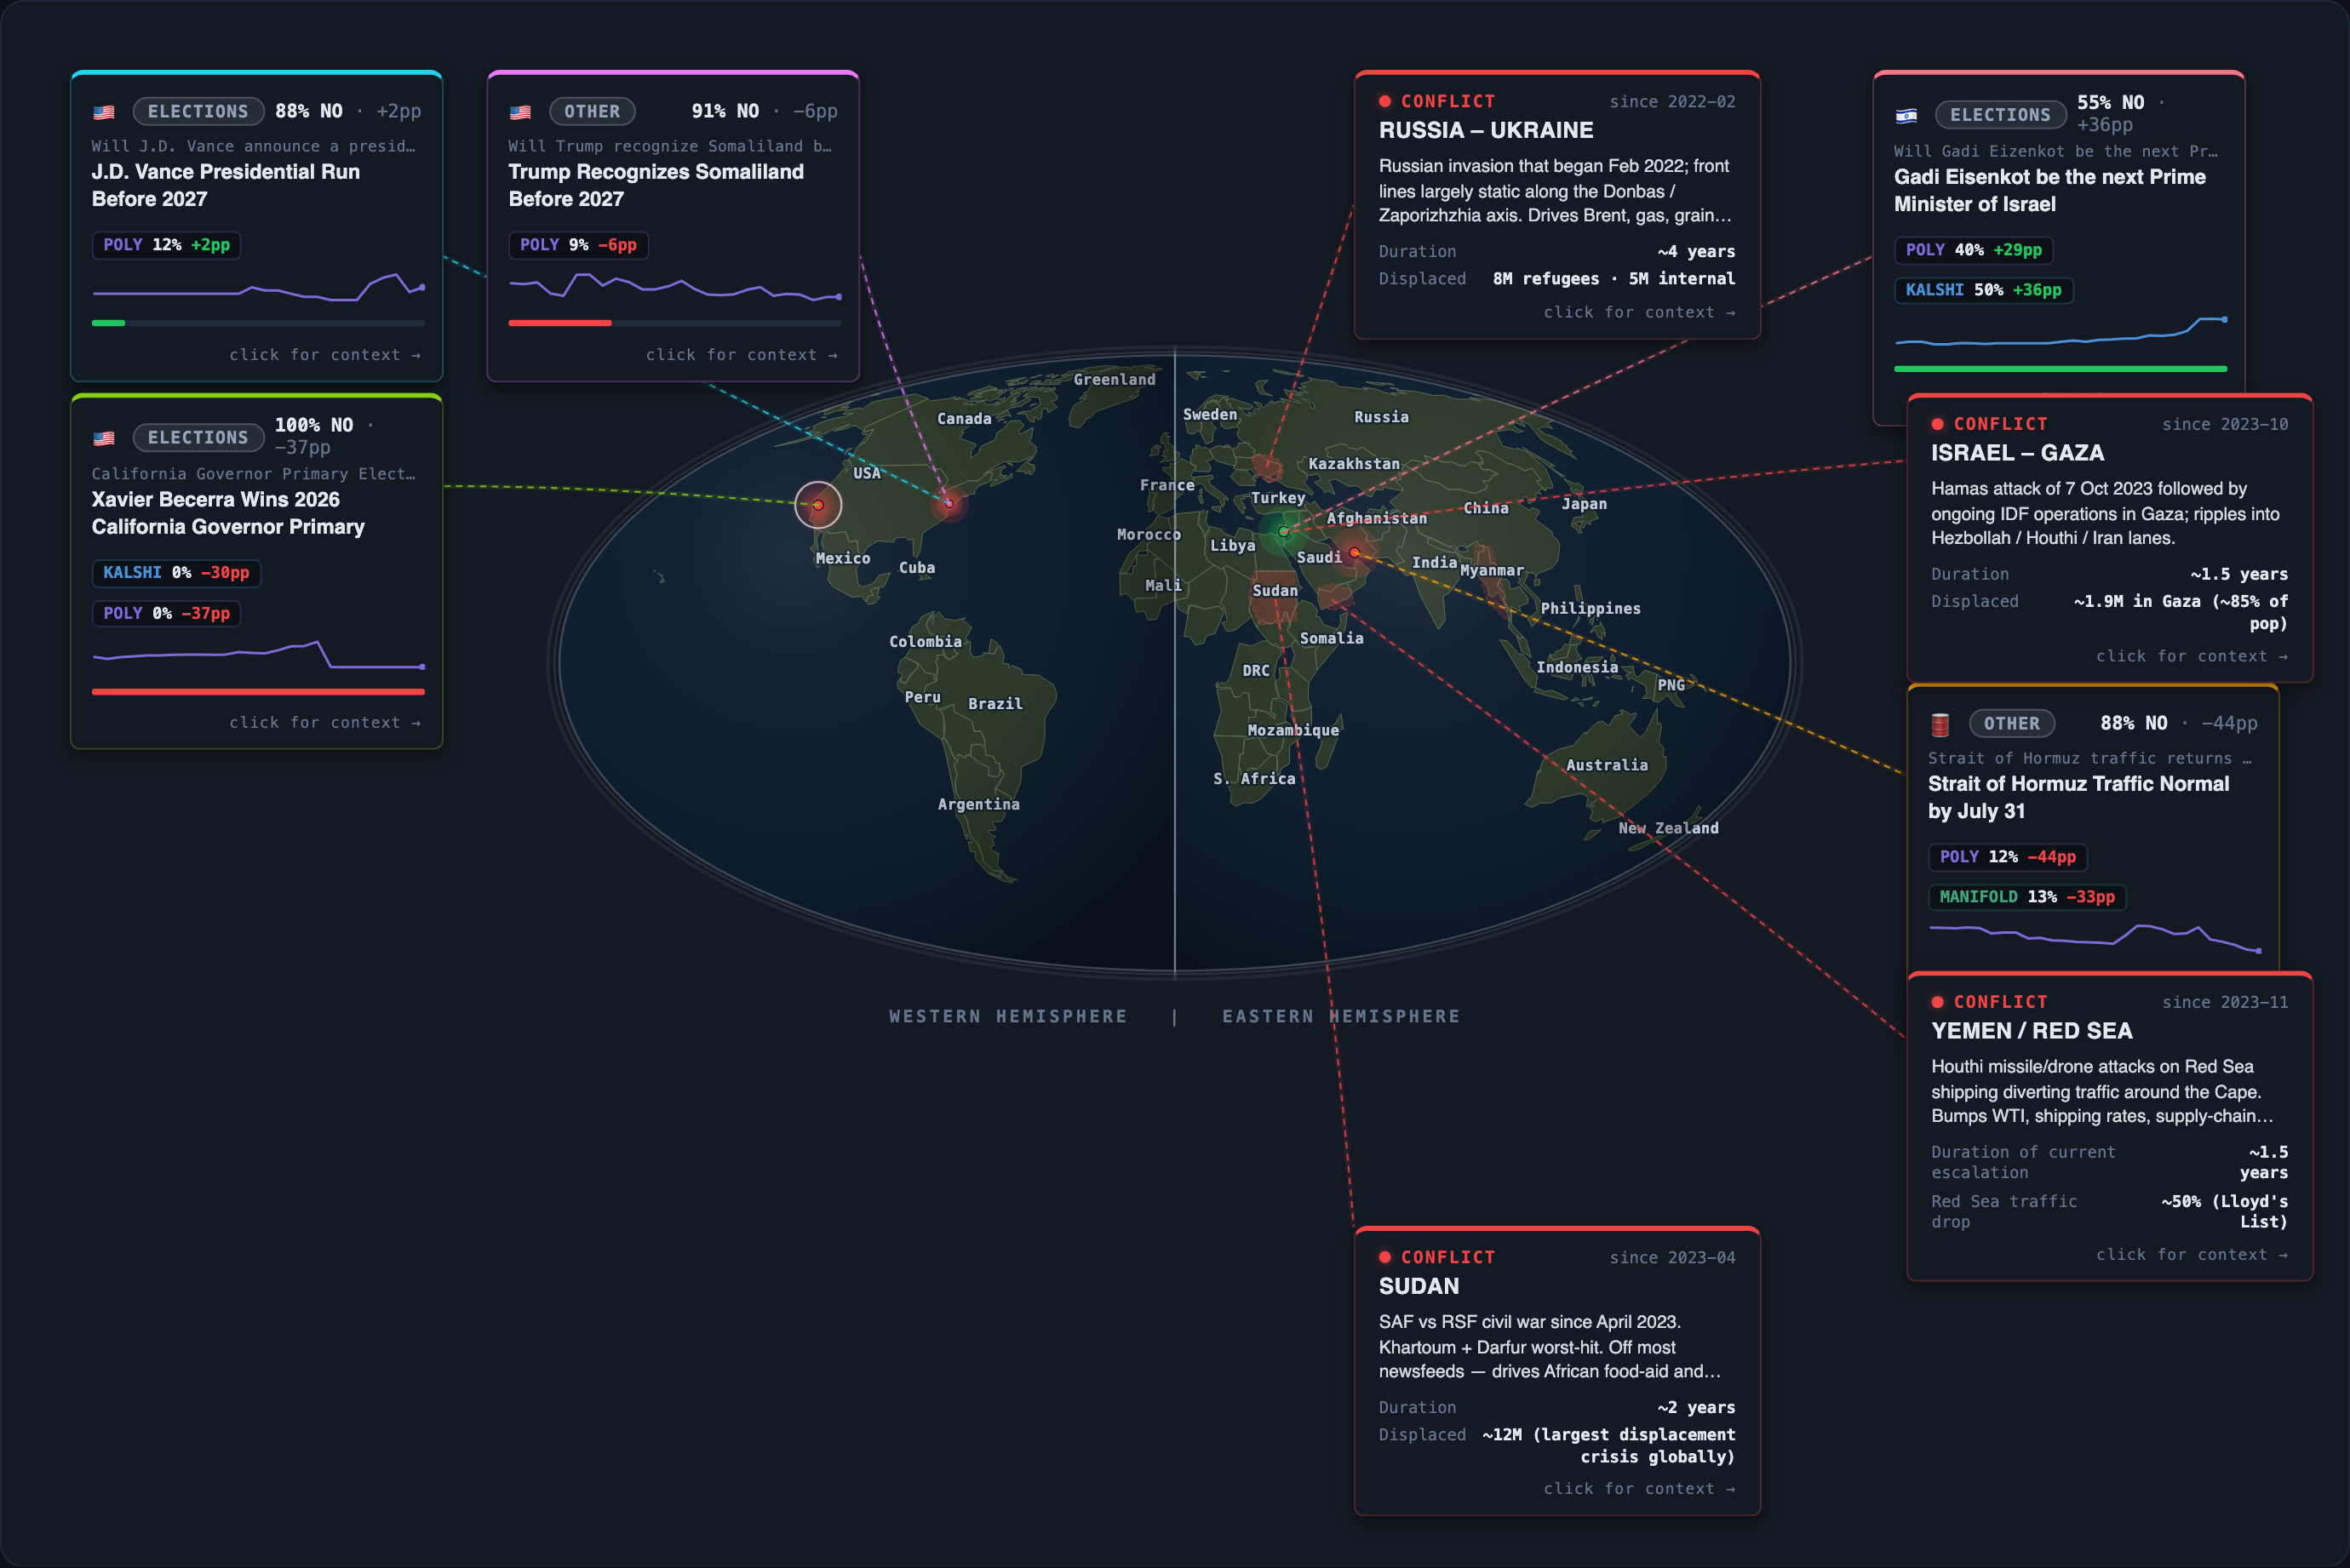
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 1 rose 2 fell 0 flat |
| EUROPE | 0 rose 0 fell 0 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |