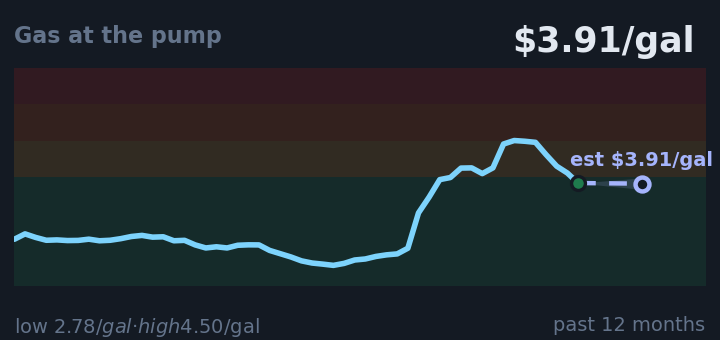
Gas at the pump is the single number families notice most, and historically it's one of the strongest predictors of how voters feel about an administration.
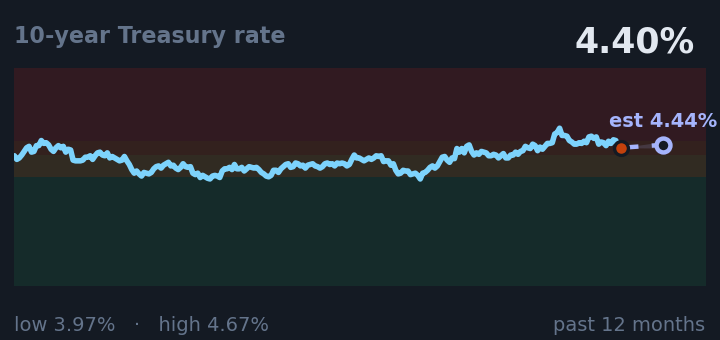
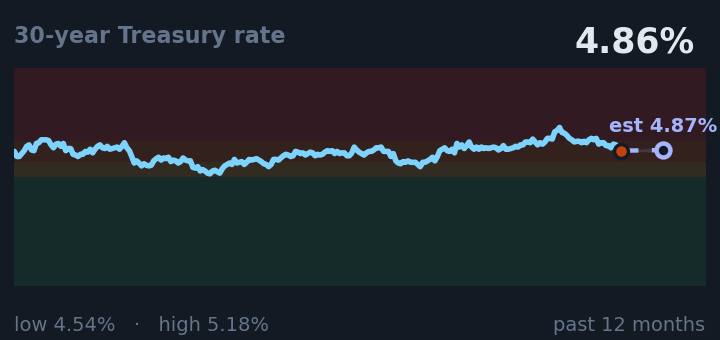
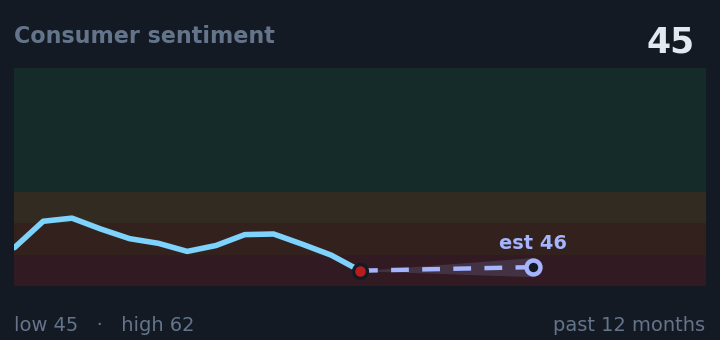
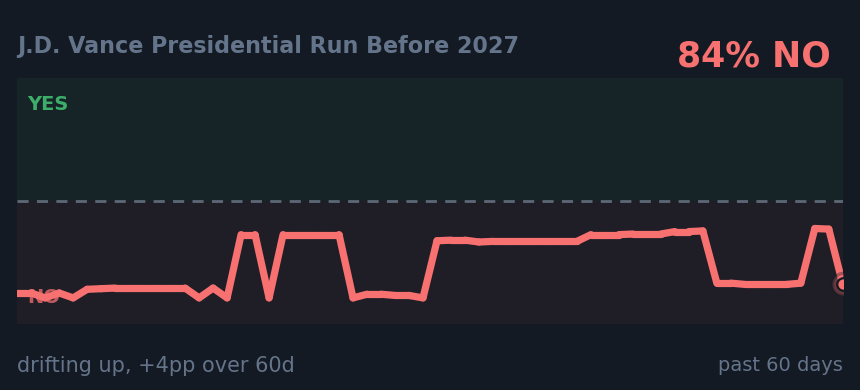
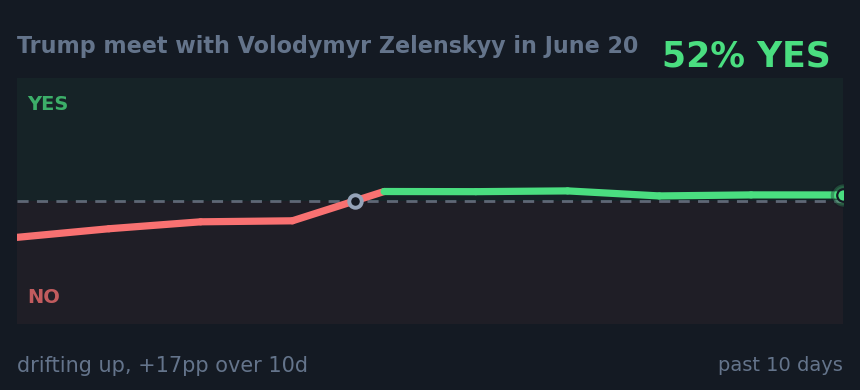
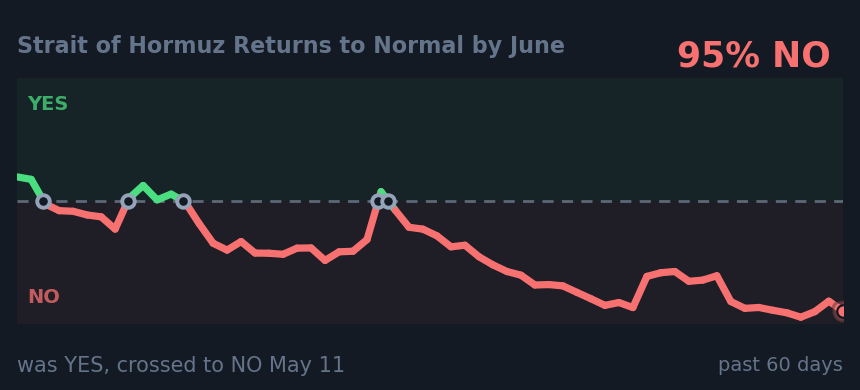
Consumer confidence just fell to 45, near its lowest in a year. That depressed mood is historically toxic for sitting administrations, and it's probably why traders downgraded J.D. Vance's chances of a 2027 presidential run, pricing him at 84% NO, down 5 points overnight. Gas dropped from $4.49 to $3.91 a gallon, a real relief, but it's still in the middle of its yearly range and approaching the price where it historically affects voting. The bigger concern is building in government borrowing costs: the 10-year rate is at 4.40%, close to 4.5% where policy makers historically get pressured to change course, and the 30-year is at 4.86%, nearing the 5% threshold where analysts say policy breaks down. Overnight, markets jumped sharply on geopolitical risk: shipping through the Strait of Hormuz (the chokepoint for Middle East trade) jumped to 95% likely to stay disrupted through June, and talks between Trump and Zelenskyy jumped 18 points to 52% likely to happen this month.
→ Open the live interactive board
Get this every morning
Delivered to your inbox at 6:30, with the full archive, alerts, and the live board →
Gas at the pump is the single number families notice most, and historically it's one of the strongest predictors of how voters feel about an administration.
When the 10-year Treasury rate approaches 4.5%, it means investors are getting nervous about government debt, and that pressure usually forces policy makers to back off big spending plans.
Source: FRED
The 30-year rate reflects how high investors think inflation will stay for the next generation, and it feeds directly into the mortgage rates banks offer.
Source: FRED
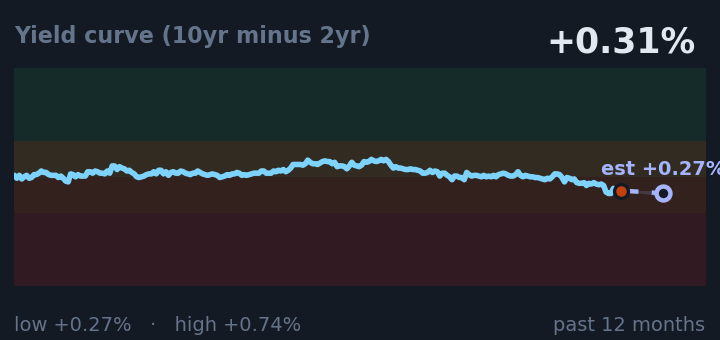
When the difference between the 10-year and 2-year rates gets smaller, it's a historical warning sign that the economy is slowing down.
Source: FRED
Consumer confidence this low (45) historically precedes slower hiring and the start of economic downturns, because families stop spending when they're worried.
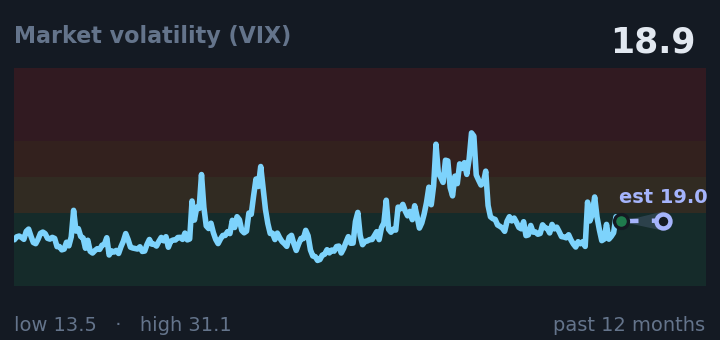
The VIX measures how nervous stock traders are; at 18.9 it's in the normal calm range, not a panic signal.
Source: FRED
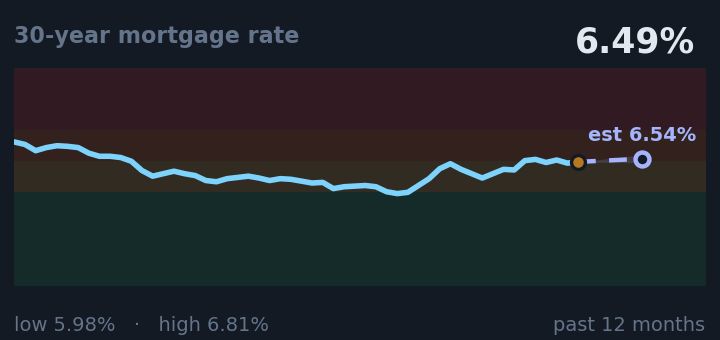
Mortgage rates at 6.49% mean monthly payments are high, and when rates stay elevated for months, fewer families can afford new homes, which eventually cools both prices and construction.
Source: FRED
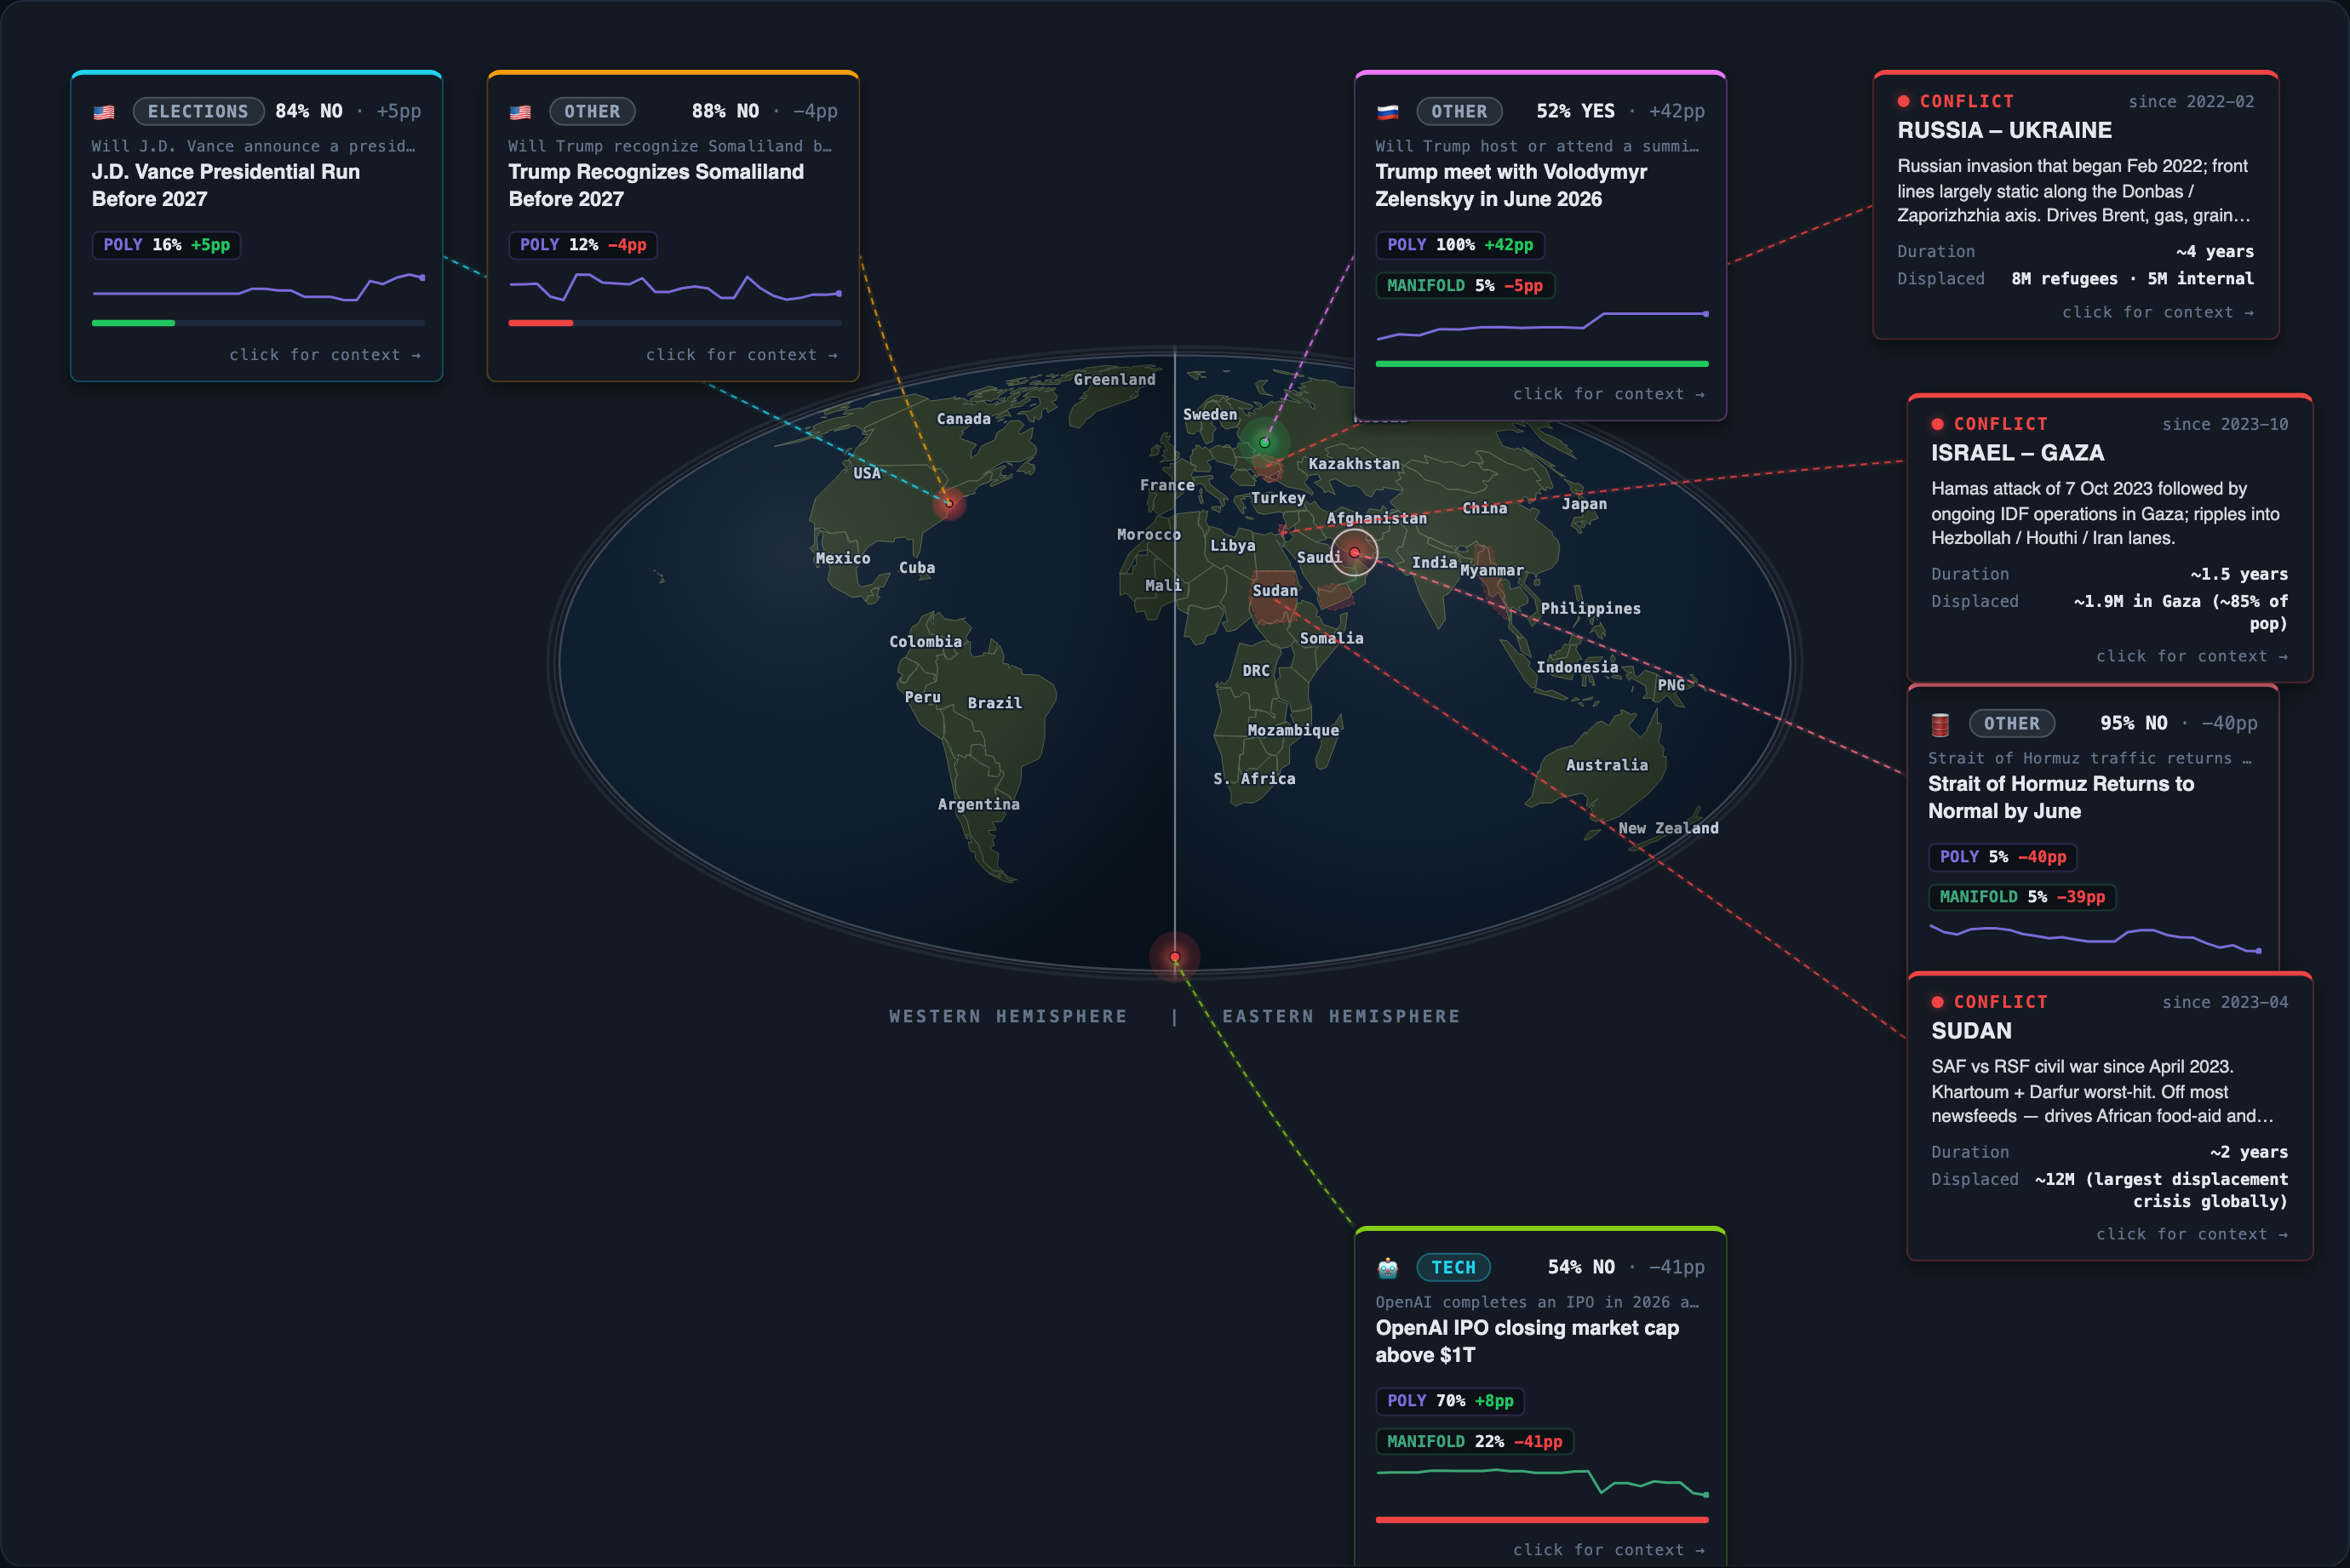
In plain terms: the public’s money is leaning that this will not happen, and grew less sure overnight.
Market consensus at 10% reflects skepticism of a near-term announcement given Vance's current VP role and weak economic conditions (gas $4.12, consumer sentiment 57) that typically disfavor incumbent administration moves. Agreement across platforms suggests genuine uncertainty ra
In plain terms: the public’s money is very confident this will not happen, and grew a little more sure overnight.
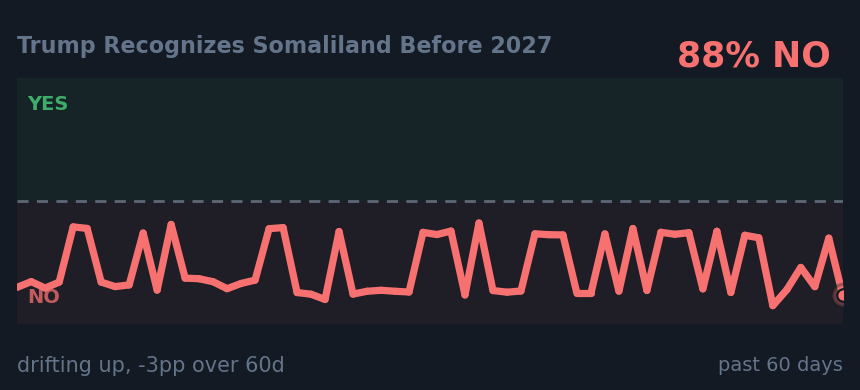
Massive 48-point spread between Kalshi (63%) and Polymarket (15%) on U.S. recognition of breakaway Somaliland. Disagreement likely reflects different interpretations of Trump's foreign policy priorities, geopolitical constraints with Somalia, and whether recognition occurs via ex
In plain terms: the public’s money is close to a coin flip on whether this will happen, and grew more sure overnight.
—
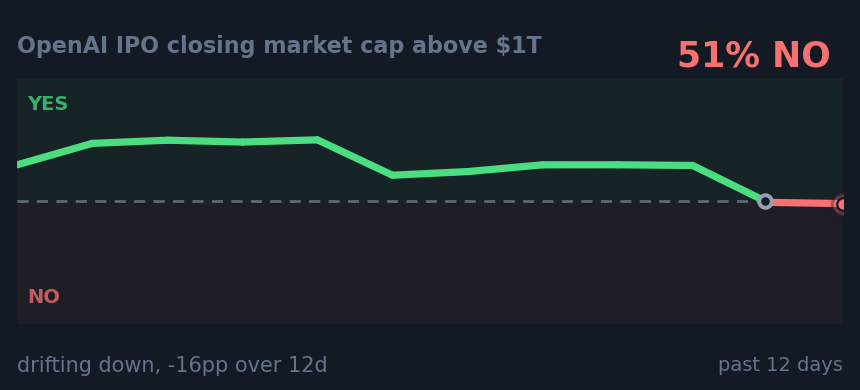
In plain terms: the public’s money is close to a coin flip on whether this will not happen, and grew more sure overnight.
Both major prediction markets converge on 62% probability that OpenAI will go public in 2026 at a $1T+ valuation. The agreement suggests confidence in near-term IPO timing and sustained AI market dominance, though regulatory uncertainty (FTC commissioner changes) and execution ri
In plain terms: the public’s money is very confident this will not happen, and grew much more sure overnight.
Markets disagree sharply on whether shipping disruptions in the Strait of Hormuz resolve by mid-to-end June, with Polymarket pricing much lower (14%) than Manifold (36%). The 22-point spread suggests uncertainty about geopolitical de-escalation timelines and what "normal" operati
Hamas attack of 7 Oct 2023 followed by ongoing IDF operations in Gaza; ripples into Hezbollah / Houthi / Iran lanes.
Russian invasion that began Feb 2022; front lines largely static along the Donbas / Zaporizhzhia axis. Drives Brent, gas, grain, defense-stock pricing.
SAF vs RSF civil war since April 2023. Khartoum + Darfur worst-hit. Off most newsfeeds — drives African food-aid and gold-flow markets.
Houthi missile/drone attacks on Red Sea shipping diverting traffic around the Cape. Bumps WTI, shipping rates, supply-chain timing markets.
Post-coup civil war between junta and PDF + ethnic armed organizations. Junta losing territory in Shan + Rakhine since late 2023.
| AMERICAS | 1 rose 1 fell 0 flat |
| EUROPE | 0 rose 0 fell 0 flat |
| ASIA | 0 rose 0 fell 0 flat |
| MENA | 0 rose 0 fell 0 flat |
| CRYPTO | 0 rose 0 fell 0 flat |